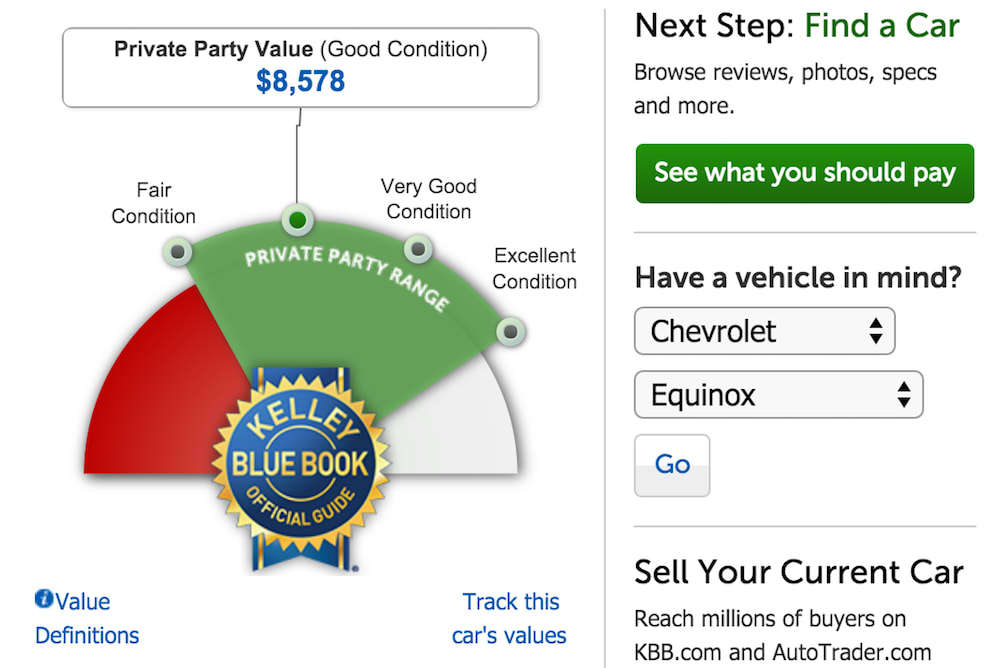
7 Things Worth Knowing About How to Calculate Car Value for Net Worth
The process of figuring out car value for net worth isn’t one-size-fits-all. It’s a mix of data-driven estimation and practical adjustments. Here’s what separates a rough guess from a precise valuation.1. Depreciation Curves Aren’t Linear—and They Vary by Vehicle Type
Most cars lose 60% of their value in the first three years, but the rate isn’t uniform. Luxury vehicles often depreciate faster than mainstream models due to rapid obsolescence, while commercial trucks or fleet cars might hold value longer because of high demand in specific sectors. A Tesla Model 3 might drop from $40,000 to $25,000 in 24 months, while a Toyota Tacoma could retain 55% of its value over the same period. How to calculate car value for net worth starts with identifying your vehicle’s depreciation trajectory. Industry tools like NADA Guides or Black Book provide baseline curves, but these should be adjusted for actual mileage, accident history, and market segment. The mistake many make is assuming depreciation slows after year five. In reality, the rate of decline often stabilizes but doesn’t halt. A 2018 Honda Civic with 80,000 miles might be worth 30% of its original price, but a similar car with 120,000 miles could fetch only 15%. The key is cross-referencing depreciation tables with your vehicle’s specific usage patterns.2. Mileage Matters More Than You Think—But Context Is Everything
A car’s odometer reading is the single most influential factor after age, yet it’s often misinterpreted. While high mileage typically correlates with lower value, a well-maintained vehicle with 150,000 miles might still command a premium in rural markets where alternatives are scarce. Conversely, a low-mileage car in an urban area with poor public transit could be overvalued if demand for reliability outweighs the need for low odometer numbers. When calculating car value for net worth, factor in: - Average annual mileage (e.g., 12,000 vs. 25,000 miles/year). - Local commuting norms (e.g., a 100,000-mile car in Los Angeles may be worth less than one in Des Moines). - Service records (oil changes, timing belt replacements, or lack thereof). The rule of thumb? Every 10,000 miles beyond the average for a vehicle’s age can shave 3–7% off its value, but this varies by make and model.3. Condition Reports Are Non-Negotiable for Accuracy
A car’s physical state can swing its value by 20–30% compared to industry averages. A pristine interior with no stains, a fully functional infotainment system, and no bodywork flaws will always outperform one with visible wear. Yet, many sellers (and net worth trackers) overlook subtle issues like: - Tire tread depth (bald tires can reduce value by up to 10%). - Rust or corrosion (especially in snowy climates). - Electrical gremlins (flickering lights, dead sensors). Professional inspection services like Carfax or AutoCheck provide condition scores, but these are often skewed toward recent accidents. For accurate car valuation in net worth calculations, a hands-on assessment—or at least high-resolution photos of all angles—is essential. Even a single dent in a luxury car can drop its resale value by $1,000–$3,000, depending on the brand.4. Location Adjustments Can Swing Values by 15–25%
A car’s worth isn’t just about the vehicle itself; it’s about what buyers are willing to pay in your area. A 2019 Subaru Outback might sell for $22,000 in Boston but only $18,000 in Houston, even after adjusting for local cost of living. Factors like: - Tax rates (high-tax states may see lower used car prices). - Weather patterns (snow tires add value in Minnesota; A/C systems in Arizona). - Local supply/demand (a flooded market in Florida vs. a shortage in Nevada). To calculate car value for net worth with precision, use tools like Kelley Blue Book’s "Trade-In Value" calculator, which factors in ZIP code data. Alternatively, check recent sold listings on Autotrader or Cars.com in your region—actual sale prices are more reliable than estimated values.5. Financing Status Changes Everything
If your car is still under a loan, its net contribution to your worth isn’t the trade-in value—it’s the trade-in value minus the remaining balance. For example: - Trade-in value: $15,000 - Loan balance: $18,000 - Net worth impact: -$3,000 (a liability, not an asset). This is where many people trip up. They list the car’s value as $15,000 but forget the $18,000 debt attached to it. When figuring out car value for net worth, always subtract: - Outstanding loan balances. - Lease payoff amounts (if applicable). - Any liens or secured debts. Even if you’re upside-down on the loan, the car’s market value is still its fair valuation—just one that reduces your net worth.6. Seasonality and Market Trends Require Timing
Car values aren’t static; they fluctuate with seasons, economic cycles, and even geopolitical events. For instance: - Spring and summer see higher demand for SUVs and trucks (good for sellers). - Holiday seasons (November–January) often mean discounts for older models. - Recessions can drop used car prices by 5–10% as buyers delay purchases. To calculate car value for net worth at the right time, monitor: - Monthly price trends (Kelley Blue Book tracks these). - Inventory levels (high supply = lower prices). - Interest rate climates (high rates reduce demand for financing). A car that’s worth $20,000 in May might dip to $18,500 by October if inventory rises.7. Special Circumstances Demand Custom Calculations
Not all cars fit standard valuation models. How to calculate car value for net worth gets complex with: - Classic or collector cars (where condition, provenance, and rarity matter more than mileage). - Modified or tuned vehicles (performance upgrades can add value, but insurance companies may not recognize them). - Electric or hybrid vehicles (battery degradation requires specialized assessments). - Fleet or rental cars (high mileage is expected, but commercial use history affects value). For these cases, consult niche appraisers or industry-specific guides. A 1967 Mustang might be worth $50,000 based on its originality, while a modified Camaro with aftermarket parts could be worth $35,000—but only if the modifications are documented and desirable.
How These Facts Connect
The interplay between depreciation, condition, location, and market trends means calculating car value for net worth is less about plugging numbers into a formula and more about assembling a puzzle. Ignore one piece—like mileage or regional demand—and your valuation could be off by $5,000 or more. The most accurate approach combines: 1. Baseline depreciation data (from NADA or Black Book). 2. Vehicle-specific adjustments (mileage, condition, modifications). 3. Geographic and seasonal modifiers. 4. Financial liabilities (loans, leases). The result isn’t just a number; it’s a snapshot of your car’s true economic contribution to your net worth—whether it’s an asset, a liability, or somewhere in between. Here’s how the key factors stack up side by side:| Factor | Impact on Valuation | How to Adjust |
|---|---|---|
| Depreciation Curve | 60% loss in first 3 years; varies by type | Use NADA Guides or Black Book; adjust for age/mileage |
| Condition | Can add/subtract 20–30% | Professional inspection or detailed photos |
| Location | 15–25% regional variance | Check local sold listings; use ZIP-code tools |
Conclusion
How to calculate car value for net worth isn’t a one-time task—it’s an ongoing process that evolves with your vehicle’s age, your local market, and even your financial goals. The biggest mistake isn’t underestimating depreciation; it’s assuming your car’s value is static. A car that was worth $25,000 last year might be worth $20,000 today, and if you’re not adjusting your net worth tracking accordingly, you’re misrepresenting your financial health. For most people, cars are their second-largest asset after their home. Getting the valuation right ensures your net worth reflects reality—not wishful thinking. Start with industry tools, then layer in the specifics of your vehicle and market. The difference between a rough estimate and a precise calculation could mean the gap between qualifying for a loan and being denied, or between feeling financially secure and stressing over an inflated asset.Comprehensive FAQs
Q: Should I use the trade-in value or private-party sale value when calculating car value for net worth?
A: Use the private-party sale value for the most accurate reflection of your car’s worth, as trade-in offers are often 10–20% lower due to dealer markups. However, if you’re planning to trade in soon, the trade-in value may be a closer estimate of what you’d realistically receive. Always check recent sold listings in your area for the fairest comparison.
Q: Does leasing a car affect my net worth calculation differently than owning?
A: Yes. With a lease, you’re not building equity—you’re paying for the depreciation period of the car. Your net worth impact is the lease payoff amount (a liability) minus any equity you’ve built (usually minimal). If you’re upside-down on a lease, it’s a net negative. Ownership, however, allows the car’s value to (however slowly) contribute to your assets—though you must still account for depreciation.
Q: How often should I recalculate my car’s value for net worth purposes?
A: At least annually, but more frequently if: - Your car is 5+ years old (depreciation accelerates). - You’ve added significant mileage (e.g., 10,000+ miles in a year). - Market conditions have shifted (e.g., recession, supply chain issues). For high-value or classic cars, consider quarterly checks due to higher volatility.
Q: Can I deduct my car’s depreciation on taxes when calculating net worth?
A: Only if you use the car exclusively for business (e.g., rideshare, freelance work). For personal use, depreciation isn’t tax-deductible, but you can claim actual expenses (gas, maintenance, insurance) if you meet IRS mileage logs requirements. If you’re tracking net worth for personal finance—not taxes—depreciation is still a critical adjustment, even if non-deductible.
Q: What’s the best tool for calculating car value for net worth if I don’t want to do it manually?
A: Kelley Blue Book’s "Trade-In Value" tool is the most widely used, but for private-party accuracy, Edmunds True Market Value or NADA Guides are stronger. For niche vehicles (classic, modified, EVs), consult specialized appraisers or forums like Bring a Trailer (for muscle cars) or EV Marketplace (for electric vehicles). Always cross-reference with local sold listings—no tool is perfect without real-world data.
