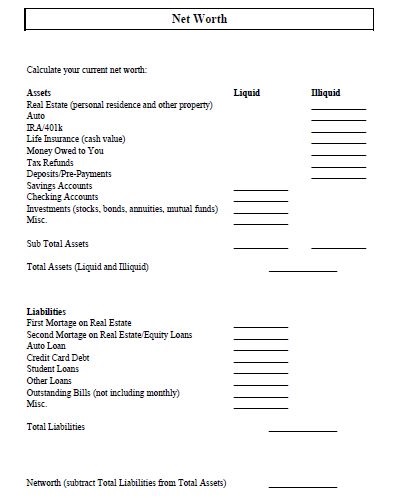
7 Things Worth Knowing About the personal net worth worksheet
The personal net worth worksheet isn’t a static document. It’s a living tool that evolves with life’s stages—from student loans to homeownership to retirement accounts. Below are seven truths about how it works, why it’s often misunderstood, and how to use it effectively.1. It’s the only financial metric that matters beyond income
Income tells you how much you earn, but a net worth statement shows what you’ve accumulated. A high salary doesn’t guarantee wealth if debt or poor spending habits erode savings. Conversely, someone with modest earnings but disciplined asset growth can build significant net worth over time. The worksheet forces this distinction: it separates those who manage money from those who merely earn it. The mistake? Assuming net worth is only for the wealthy. A first-time homebuyer with a mortgage and modest savings still has a net worth—even if it’s negative. Tracking it early reveals whether lifestyle choices align with long-term goals.2. Assets aren’t just what you think they are
Most people list obvious items—cash, real estate, retirement accounts—but overlook others. A personal net worth worksheet should include: - Intangible assets: Business equity, patents, or even a valuable skill set (if monetizable). - Illiquid assets: Collectibles, fine art, or cryptocurrency (valued conservatively). - Human capital: Future earning potential, especially for younger professionals. Excluding these distorts the picture. An entrepreneur with a thriving side hustle but no traditional savings might underestimate their wealth—until they quantify their business’s net worth separately.3. Liabilities include more than just debt
Debt is obvious, but liabilities extend further. A net worth calculator should account for: - Future obligations: Childcare costs, aging parents’ care, or upcoming tuition. - Opportunity costs: Money tied up in low-yielding accounts instead of investments. - Tax liabilities: Unpaid taxes or deferred compensation that reduce take-home pay. Ignoring these turns the worksheet into a partial truth. A family with a paid-off mortgage but no emergency fund might feel secure—until an unexpected expense hits.4. It reveals your financial leverage ratio
Net worth alone doesn’t tell the full story. Divide total liabilities by total assets to uncover your leverage ratio. A ratio under 0.5 (liabilities are less than half of assets) signals financial flexibility. Above 1.0 means liabilities exceed assets—a red flag unless the debts are low-interest (e.g., a mortgage). This ratio is why some ultra-high-net-worth individuals carry debt: if their assets (investments, real estate) grow faster than the interest on the debt, leverage works in their favor. For most, however, high leverage is a ticking time bomb.5. The worksheet exposes hidden spending leaks
A personal net worth tracker isn’t just for assets and debts—it’s a spending audit. By comparing year-over-year net worth, you spot: - Inflation erosion: Are savings losing purchasing power? - Lifestyle creep: Did a raise go toward bigger expenses instead of investments? - Tax inefficiencies: Are high-income earners paying too much in taxes without optimizing deductions? One couple realized their net worth stagnated because subscription services and "treat yourself" purchases added up to thousands annually. The worksheet made it visible.6. It’s not just for individuals—businesses use it too
While personal finance focuses on individuals, a business net worth worksheet follows the same logic: assets minus liabilities equals equity. Startups use it to attract investors, while established firms track it for tax planning. The principle is identical—just the scale changes. For solopreneurs, blending personal and business net worth can be risky. A personal net worth worksheet should separate the two to avoid confusion, especially during tax season or when seeking funding.7. The most valuable insight isn’t the number—it’s the trend
A single net worth figure is useless. What matters is the trajectory. Is it growing, stagnating, or declining? A dip might signal overspending, while steady growth suggests alignment with goals. Tools like YNAB (You Need A Budget) or Mint automate tracking, but even a manual worksheet updated quarterly provides clarity. The trend also highlights external factors: market downturns, career changes, or unexpected expenses. Without tracking, these become invisible until they’re crises.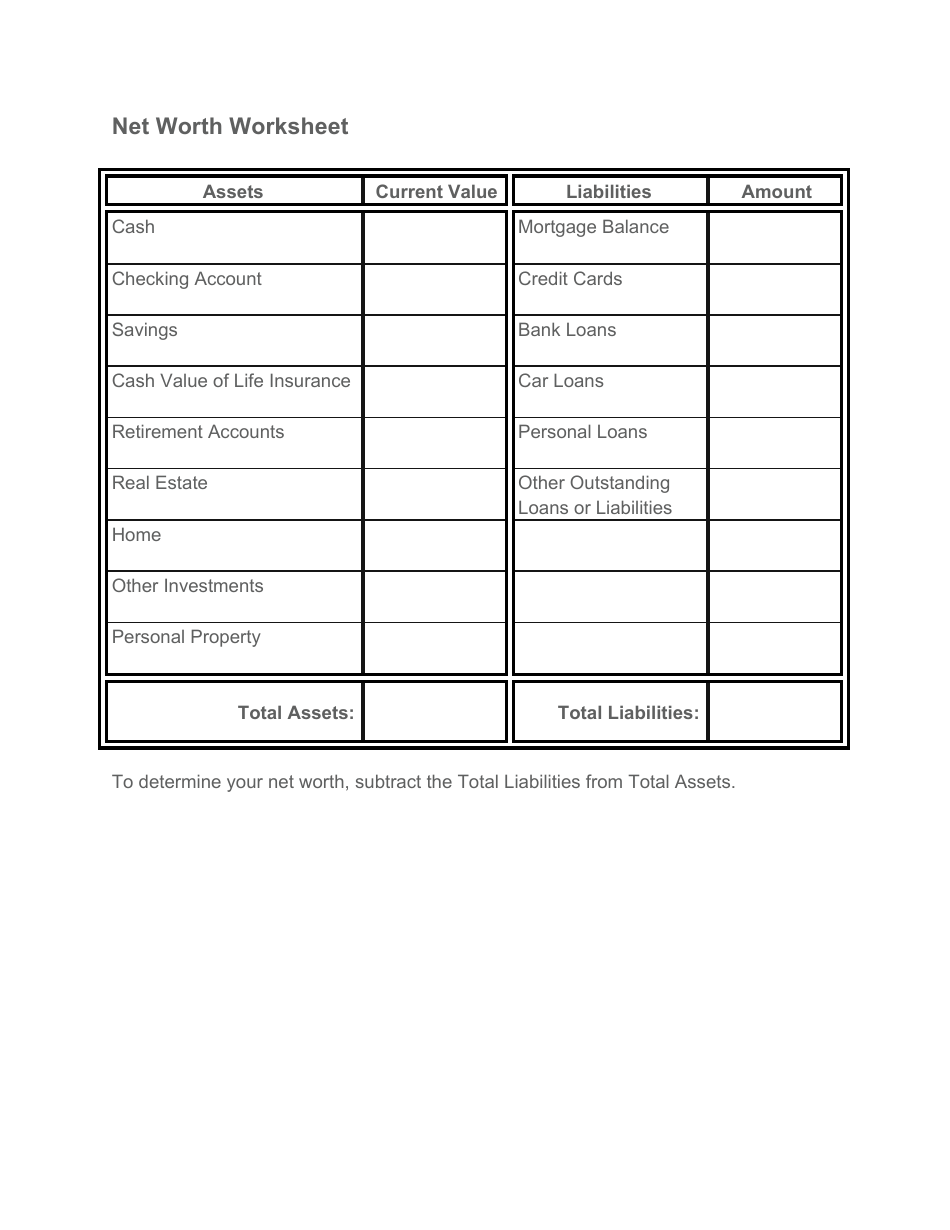
How These Facts Connect
The personal net worth worksheet isn’t a one-dimensional tool. It’s a system that ties together income, spending, debt, and asset growth. The leverage ratio, for example, depends on both asset valuation and liability management—two areas often treated separately. Similarly, hidden spending leaks (fact #5) directly impact the trend (fact #7), creating a feedback loop. | Fact | Key Insight | Actionable Takeaway | |------------------------|------------------------------------------|-------------------------------------------------| | Assets beyond cash | Intangibles and human capital matter | Audit non-obvious assets annually | | Liabilities > debt | Future obligations are real costs | Factor in caregiving or education expenses | | Leverage ratio | High debt relative to assets is risky | Aim for liabilities < 50% of total assets | | Spending leaks | Small expenses compound over time | Cap discretionary spending at 10% of net worth | | Business net worth | Personal and business finances interact | Keep records separate to avoid tax confusion | | Trend over snapshot | Growth matters more than a single number | Review net worth quarterly, not annually | The worksheet’s true value lies in its ability to connect dots most people miss. A rising net worth with high leverage might indicate risky growth. A flat net worth with low debt could signal missed investment opportunities. The tool doesn’t judge—it reveals.
Conclusion
A personal net worth worksheet is the financial equivalent of a health checkup. It doesn’t cure problems, but it identifies them early. The difference between those who retire comfortably and those who scramble in their 60s often comes down to whether they tracked their net worth consistently. The barrier isn’t complexity—it’s discipline. Updating the worksheet requires confronting uncomfortable truths: Are you saving enough? Are debts manageable? Are assets growing faster than inflation? The answers might not be what you want to hear, but they’re necessary. Start with a simple template, refine it over time, and let it guide decisions. The alternative—flying blind—is a recipe for financial stress.Comprehensive FAQs
Q: How often should I update my personal net worth worksheet?
A: Quarterly is ideal for most people, especially if your financial situation changes frequently (e.g., job shifts, market volatility). Annual updates suffice for stable incomes with minimal debt or investments. The key is consistency—even rough estimates help track trends.
Q: Do I need to include my car in the assets section?
A: Yes, but with a caveat. List its current market value (not what you paid), and subtract any remaining loan balance. Cars depreciate rapidly, so this asset often turns into a liability if financed long-term. Consider whether holding onto it aligns with your net worth goals.
Q: What if my net worth is negative? Is that normal?
A: Negative net worth is common early in life, especially for students or young professionals with loans. It’s not inherently bad—what matters is the trajectory. If your net worth is improving (e.g., student loans decreasing while savings grow), you’re on the right path. The goal is to move toward positive net worth as income and assets outpace liabilities.
Q: Should I include my pension or retirement accounts in the worksheet?
A: Absolutely. Retirement accounts (401(k)s, IRAs, pensions) are critical assets. List their current balances, but note that some (like traditional IRAs or 401(k)s) are pre-tax—withdrawals may affect taxable income. If you have employer matches, track those separately as they compound over time.
Q: Can I use a free online tool instead of a manual worksheet?
A: Yes, but with trade-offs. Tools like Personal Capital, Mint, or even Google Sheets templates automate calculations and categorize transactions. However, they may not capture intangible assets (e.g., business equity) or future liabilities (e.g., caregiving costs). A hybrid approach—using software for tracking but manually adjusting for non-financial factors—often works best.
Q: How do I handle assets with fluctuating values, like stocks or cryptocurrency?
A: For volatile assets, use conservative valuations. For stocks, average the last 3–6 months’ values. For crypto, take the lowest recent price if you’re risk-averse or the highest if you’re optimistic—but be consistent. The goal is accuracy, not wishful thinking. Reassess quarterly to avoid overestimating gains.
Q: What’s the difference between net worth and liquid net worth?
A: Net worth includes all assets (house, car, investments) minus liabilities. Liquid net worth subtracts illiquid assets (e.g., a primary residence, collectibles) and focuses only on cash, easily sellable investments, or low-effort assets. Liquid net worth is a better stress-test metric—it shows how much you could access quickly in an emergency.
Q: Can a personal net worth worksheet help with estate planning?
A: Indirectly, yes. By documenting assets and liabilities, you clarify what you’re passing on. For estate planning, you’ll need to dig deeper—listing beneficiaries, valuing non-financial assets (e.g., heirlooms), and accounting for taxes. But the worksheet is the first step in understanding the total picture before consulting a lawyer or financial advisor.
