
5 Things Worth Knowing About the Peak of Bill Gates’ Wealth
The conversation around "what was the most of billd gate net worth" often overlooks the context that made it possible. Five key elements define that moment—and why it remains a landmark in modern finance.1. The Microsoft Stock Surge of 1999–2000
The late 1990s were Microsoft’s golden age. The company’s stock, which had traded around $20 in the early 1990s, soared to $140 per share by January 2000—a 700% increase in less than a decade. Gates, who held a majority stake in Microsoft through restricted stock and options, saw his personal fortune balloon accordingly. Industry estimates place his peak net worth around $101 billion in January 1999, according to Forbes—a figure that would later be surpassed but never matched in the same way. What’s often missed is that this wasn’t just about Microsoft’s profits. It was about the dot-com bubble’s halo effect: investors treated tech stocks as a class, bidding up valuations regardless of fundamentals. Gates’ wealth wasn’t just tied to Microsoft’s revenue; it was inflated by the broader market’s irrational exuberance. When the bubble burst in 2000–2001, Microsoft’s stock dropped 40%, and Gates’ net worth plummeted by roughly $30 billion in a matter of months.2. The Role of Restricted Stock and Options
Gates’ wealth wasn’t built on cash flow from Microsoft’s operations. It was structurally dependent on stock appreciation. As Microsoft’s co-founder, he held a mix of Class A shares (with 10 votes each) and Class B shares (with one vote), along with stock options that vested over time. The restricted stock—shares he couldn’t sell immediately—meant his wealth was a lagging indicator of Microsoft’s performance. By the late 1990s, Gates had millions of shares locked up, and their value was amplified by the company’s aggressive buyback program. When Microsoft repurchased shares, it reduced the float, pushing the price higher. This created a feedback loop: higher stock price → more buybacks → higher price. Gates benefited disproportionately because his stake was so large. The peak of "what was the most of billd gate net worth" wasn’t just about Microsoft’s success; it was about the architecture of his ownership.3. The Media’s Amplification of the Number
The first Forbes 400 list in 1982 didn’t include Gates, but by 1995, he was the richest person in the world. The media’s obsession with "what was the most of billd gate net worth" wasn’t just reporting—it was a feedback mechanism. Headlines like "Gates Worth $101 Billion" in 1999 became self-fulfilling prophecies. Analysts and investors fixated on the number, assuming Microsoft’s stock would keep rising to justify it. There’s a psychological dimension here. When a figure like Gates reaches $100 billion, the market treats it as a new threshold—like breaking the sound barrier. The attention distorted reality: Microsoft’s actual revenue growth couldn’t sustain such a valuation indefinitely. The peak of his wealth became a cultural artifact, not just a financial one.4. The Philanthropic Shift and Wealth Redistribution
By the mid-2000s, Gates had shifted focus from Microsoft to philanthropy. The Bill & Melinda Gates Foundation, launched in 2000, began receiving annual contributions of $1–2 billion from his personal fortune. This wasn’t just charity; it was a strategic divestment. By selling shares, he reduced his stake in Microsoft, which diluted his ownership but also lowered his net worth on paper. The irony? The more he gave away, the more his publicly reported net worth fluctuated. In 2007, he dropped from the Forbes list’s top spot after selling $5.3 billion in Microsoft stock. Yet his real wealth—his ability to influence global health and education—grew. The peak of "what was the most of billd gate net worth" wasn’t just a financial milestone; it was the moment he redefined what wealth could do.5. The 2013–2014 Comeback and the Berkshire Hathaway Factor
Gates’ wealth hit another inflection point in 2013 when he reinvested in the market. A $4.5 billion stake in Canadian National Railway and a $1.5 billion investment in Moelis & Company signaled his return to active investing. But the real catalyst was his $44 billion investment in Berkshire Hathaway stock (Class B shares) between 2013 and 2014. This wasn’t just about money—it was about leverage. Berkshire’s stock, managed by Warren Buffett, had historically outperformed the S&P 500. By the time Gates sold his Berkshire shares in 2018, they were worth $50 billion. This transaction alone pushed his net worth back into the top 10, proving that even after his Microsoft peak, he could reconstruct wealth using different strategies.
How These Facts Connect
The story of "what was the most of billd gate net worth" isn’t linear. It’s a series of interlocking cycles: Microsoft’s stock performance, media narratives, personal divestment, and reinvestment. Each factor reinforced the others. The 1999–2000 peak wasn’t just about Microsoft’s success; it was about the perfect storm of ownership structure, market psychology, and timing. What’s striking is how Gates’ wealth became a proxy for broader economic trends. When the dot-com bubble burst, his net worth dropped—not because Microsoft failed, but because the market’s collective imagination collapsed. Later, his philanthropy and reinvestments showed that wealth isn’t static; it’s a tool to be reshaped. The table below compares the key drivers of his peak:| Factor | Peak Impact | Long-Term Effect |
|---|---|---|
| Microsoft Stock Surge | $101 billion (1999) | Volatility post-bubble; diluted ownership |
| Restricted Stock & Options | 70% of wealth tied to MSFT | Forced divestment to reduce stake |
| Media Amplification | Headlines drove valuation | Created expectations unsustainable in reality |
| Philanthropic Shift | Reduced net worth on paper | Increased global influence |
| Berkshire Hathaway Reinvestment | $50B gain from Buffett’s stock | Proved wealth can be rebuilt strategically |
Conclusion
Bill Gates’ peak net worth remains one of the most scrutinized financial milestones of the modern era. It wasn’t just a personal achievement; it was a symptom of an era where tech monopolies could create fortunes that dwarfed national economies. Yet the story doesn’t end at $101 billion. It continues through his philanthropy, his reinvestments, and the way his wealth was repurposed rather than hoarded. The lesson in "what was the most of billd gate net worth" is this: Wealth at this scale isn’t an endpoint. It’s a platform. Gates’ journey shows how fortunes are made, amplified, and then redirected—sometimes for profit, sometimes for impact. For anyone studying power in the 21st century, his peak isn’t just a number. It’s a blueprint.Comprehensive FAQs
Q: When exactly did Bill Gates reach his highest net worth?
Industry estimates place the peak of "what was the most of billd gate net worth" at January 1999, when Forbes valued him at $101 billion. This followed Microsoft’s stock surge in the late 1990s and predated the dot-com crash.
Q: How did Microsoft’s stock performance directly affect his wealth?
Gates held a majority stake in Microsoft, including restricted shares that vested over time. When Microsoft’s stock price rose—especially due to the dot-com bubble—his net worth mirrored those gains almost directly. For example, a $1 increase in Microsoft’s stock value could add hundreds of millions to his personal fortune.
Q: Did Gates’ philanthropy reduce his net worth?
Yes, but strategically. Donations to the Gates Foundation required selling shares, which lowered his publicly reported net worth. However, this wasn’t a loss—it was a reallocation of capital toward global health and education initiatives.
Q: Has he ever surpassed his 1999 peak?
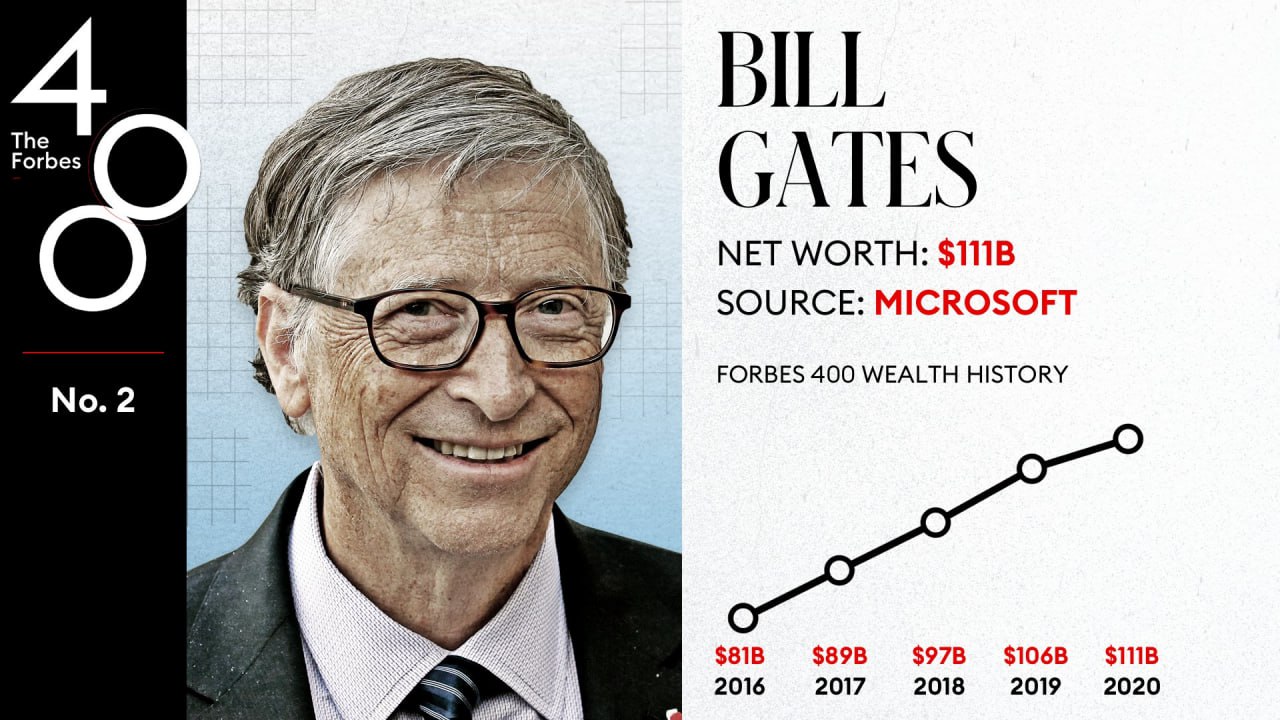
No. While his net worth has fluctuated—hitting $90 billion in 2013 and $120 billion in 2017 (briefly surpassing Warren Buffett)—the 1999 figure of $101 billion remains the highest verified point in "what was the most of billd gate net worth" history.
Q: What role did Warren Buffett play in his later wealth?
Buffett’s influence was indirect but significant. Gates’ $44 billion investment in Berkshire Hathaway between 2013–2014 leveraged Buffett’s track record. When he sold those shares in 2018, they were worth $50 billion, proving that even after his Microsoft peak, he could rebuild wealth through different assets.
Q: Why do some sources list different peak figures?
Net worth estimates vary due to valuation methods. Forbes and Bloomberg Billionaires Index use different approaches—some include private holdings, others don’t. The $101 billion figure is the most widely cited peak, but adjustments for inflation or alternative calculations (e.g., including real estate) can yield slightly different numbers.
