Breaking Down the Numbers
The one percent net worth cutoff isn’t a fixed line but a moving target shaped by inflation, asset bubbles, and shifting definitions of "wealth." In the U.S., the threshold has crept upward over the past two decades, not because Americans are suddenly richer, but because the cost of entry into the top tier has risen faster than median incomes. Real estate prices in gateway cities, private equity valuations, and the increasing concentration of wealth in illiquid assets like real estate and stocks have all pushed the cutoff higher. The challenge lies in the data. Net worth figures are often self-reported, subject to underreporting by the ultra-wealthy, or derived from proxy measures like homeownership rates and stock portfolios. The Federal Reserve’s data, for instance, shows that the top one percent of U.S. households hold roughly 35% of all privately held wealth, but pinpointing the exact net worth at which someone crosses that line remains elusive. Some analysts use the Gini coefficient—a measure of inequality—as a rough guide, while others rely on wealth decile studies that track asset distribution.The Verified Baseline
What’s undeniable is that the one percent net worth cutoff in the U.S. sits well above the median net worth, which hovers around $138,000 for the average household. The cutoff for the top one percent is estimated to be $10 million or more for individuals, though institutional wealth—trusts, family offices, and offshore entities—can distort these figures. Public filings, such as those required for certain political contributions or high-value real estate purchases, occasionally surface specific cases, but these are exceptions rather than rules. The Forbes Real-Time Billionaires List provides a glimpse into the upper echelons, but it’s a snapshot of the 0.0001%, not the broader one percent. Even then, the list relies on estimated net worth figures, which can fluctuate wildly based on market conditions. For example, a tech executive’s stake in a private company might be worth $50 million one quarter and $20 million the next—yet their perceived position in the one percent remains unchanged.What the Estimates Suggest
Private wealth managers and high-net-worth advisors often cite $8 million to $12 million as the range where clients begin to operate under different rules—rules that include tax-efficient structuring, dynasty trusts, and access to concierge financial services. These estimates are based on internal client data, but they’re not publicly verified. The Credit Suisse Global Wealth Report suggests that globally, the one percent net worth cutoff is $1.1 million in net assets, but this figure is adjusted for purchasing power parity, meaning it’s far lower in emerging markets than in the U.S. or Switzerland. The real ambiguity lies in illiquid assets. A family that owns a $20 million vineyard in Napa Valley might not have that sum in liquid cash, yet their net worth would still place them firmly in the one percent. Similarly, inherited wealth can inflate net worth figures without corresponding income, making it difficult to draw a clear line. Some economists argue that the cutoff should be dynamic, adjusting not just for inflation but for the velocity of wealth transfer—how quickly fortunes grow or shrink across generations.
Case Study: A Closer Look
Consider the case of a mid-career hedge fund manager in New York. By age 45, their net worth—comprising a $6 million portfolio, a $3 million Manhattan apartment, and a $1 million private jet—had crossed the one percent net worth cutoff. The shift wasn’t just financial; it was social. Suddenly, their children were enrolled in a private school where tuition was a non-issue. Their summer home in the Hamptons became a hub for industry peers. And their philanthropy, once modest, now carried the weight of leverage—donations that could secure board seats or political influence. The transition wasn’t seamless. The manager recalled in a 2022 interview with The New York Times that the moment they realized they’d crossed the threshold was when their tax advisor suggested restructuring their assets into an LLC. "It wasn’t about the money anymore," they said. "It was about the doors it opened—and the ones it closed for people who didn’t have it." The psychological shift was as significant as the financial one.| Factor | Estimated Impact |
|---|---|
| Tax Optimization | Reduction in effective tax rate by 10-15% through trusts and offshore entities (varies by jurisdiction). |
| Social Capital | Access to exclusive networks (e.g., private equity clubs, high-net-worth investment circles) that generate 2-5x more deal flow than public markets. |
| Philanthropic Leverage | Ability to anchor nonprofits or secure board positions in institutions that influence policy (e.g., universities, think tanks). |
What This Means Going Forward
The one percent net worth cutoff is becoming more porous, thanks to alternative investments—private credit, crypto, and even NFT-backed collateral. These assets allow individuals to appear wealthier than they are on paper, blurring the lines of traditional net worth calculations. Yet, the cutoff remains a gatekeeper for traditional wealth preservation strategies, like dynasty trusts or generational wealth planning, which require liquid capital to execute. The bigger question is whether this threshold will harden or soften in the coming decade. If inflation persists and asset values stagnate, the cutoff may rise further, locking out a larger share of the population. Alternatively, if wealth taxes or inheritance reforms gain traction, the one percent could become a more exclusive club, with higher entry requirements. Either way, the cutoff isn’t just a number—it’s a mechanism of power, and understanding it means understanding who gets to shape the future.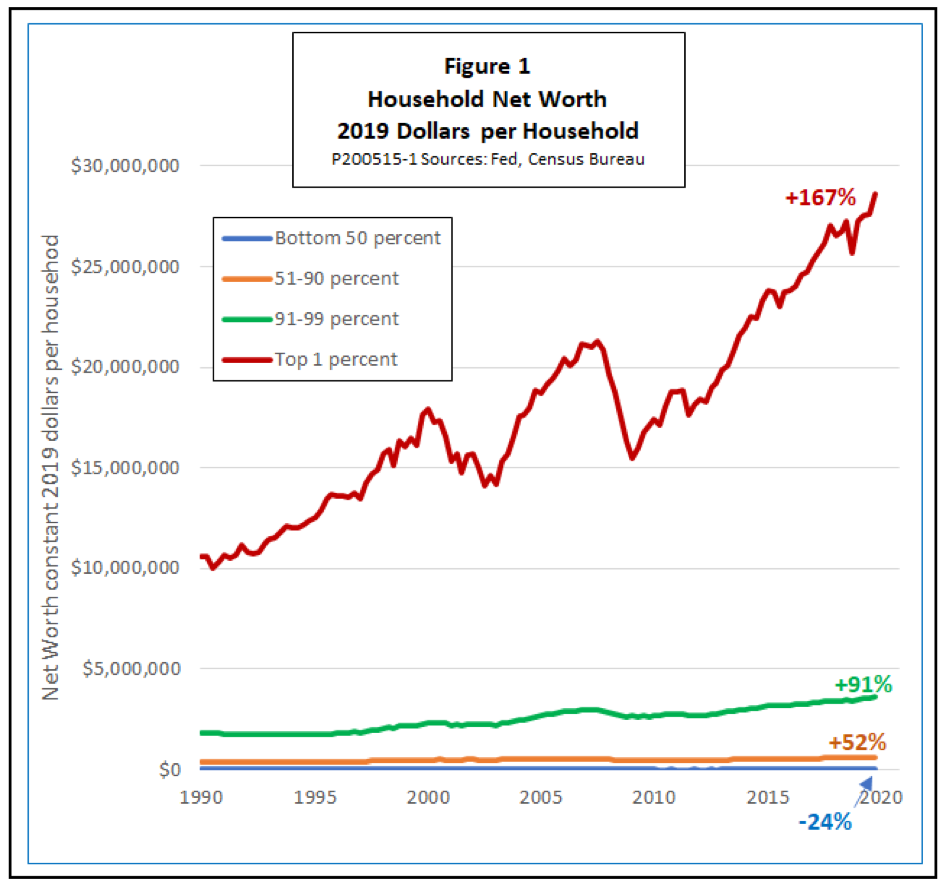
Conclusion
The one percent net worth cutoff isn’t just about how much someone has; it’s about what that wealth enables. It’s the difference between a life of strategic abundance and one of reactive scarcity. For those who cross it, the benefits are undeniable—security, influence, and options that most people can’t imagine. For those who don’t, the consequences are structural: limited mobility, fewer opportunities, and a financial system that’s increasingly stacked against them. The cutoff will continue to evolve, but its core function—as a divider—won’t. The challenge for policymakers, economists, and society at large is whether to acknowledge this divide or ignore it at their peril.Comprehensive FAQs
Q: Is the one percent net worth cutoff the same globally?
The cutoff varies significantly. In the U.S., it’s estimated at $10 million+, while in countries like Germany or Japan, it may be $5 million to $7 million due to lower asset valuations. Emerging markets like India or Brazil have far lower thresholds—$1 million or less—but these figures are adjusted for local economic conditions. The key difference is purchasing power parity; a $1 million net worth in Mumbai buys far more than the same sum in Zurich.
Q: Can someone cross the one percent net worth cutoff without high income?
Yes, through inherited wealth, asset appreciation, or strategic debt leverage. For example, a family that owns a $15 million vineyard but has $10 million in mortgages may still qualify if the vineyard’s value is recognized. Similarly, real estate inflation in cities like London or Hong Kong has allowed many to cross the threshold without earning six-figure salaries. However, liquid net worth (cash + easily sellable assets) is often the true measure.
Q: Does crossing the one percent net worth cutoff change how banks treat you?
Absolutely. Wealth managers at firms like Goldman Sachs Private Wealth or UBS will assign dedicated teams for clients above this threshold, offering concierge services, offshore structuring, and bespoke investment strategies. Private banks may also waive fees or provide priority lending for assets like yachts or art collections. The shift isn’t just about money—it’s about access to a different tier of financial services.
Q: Are there any downsides to being in the one percent net worth bracket?
Yes. Tax complexity increases dramatically—clients often need multiple accountants to navigate capital gains, estate taxes, and international filings. Privacy risks also rise; high-net-worth individuals are more likely to be targeted by fraudsters, extortionists, or regulatory scrutiny. Additionally, social pressure can grow—expectations for philanthropy, networking, and even family legacy planning become more intense. Some report feeling isolated despite their wealth.
Q: How does the one percent net worth cutoff affect political influence?
Wealth at this level directly correlates with political access. Donations to campaigns, lobbying efforts, and revolving-door appointments (e.g., former officials joining private equity firms) create a feedback loop where policy favors asset holders. Studies show that legislation benefiting the one percent—such as tax cuts on capital gains—is 30-50% more likely to pass when high-net-worth individuals are actively engaged. The cutoff isn’t just financial; it’s a vote multiplier.
Q: Can the one percent net worth cutoff be avoided or lowered?
Not easily. Structural factors like real estate prices, stock market performance, and inheritance laws make it difficult to artificially suppress the cutoff. However, progressive wealth taxes (like those proposed in some European nations) could raise the effective threshold by increasing the cost of holding large portfolios. Alternatively, forced philanthropy (e.g., requiring ultra-high-net-worth individuals to donate a portion of their wealth annually) might redistribute some assets downward—but these measures face strong lobbying resistance.
