
Common Myths About NFL Teams Ranked by Revenue
The narrative around NFL teams ranked by revenue often oversimplifies the drivers of success. Many assume that market size alone dictates a franchise’s financial health, ignoring the role of ownership acumen, local economic conditions, and even luck. For example, the Las Vegas Raiders—once a perennial also-ran—have surged in valuation since relocating to Sin City, proving that geography isn’t destiny. Another persistent myth is that small-market teams are doomed to financial irrelevance. The Buffalo Bills, with a population base smaller than many NFL cities, have repeatedly punched above their weight by maximizing every revenue stream, from luxury suites to international partnerships.
Equally misleading is the idea that revenue equals on-field success. The Jacksonville Jaguars, despite multiple playoff disappointments, have climbed the revenue charts thanks to aggressive stadium upgrades and naming-rights deals. Conversely, the Detroit Lions—long a financial laggard—have seen their fortunes rise not because of wins, but because of a new ownership group’s willingness to invest in fan experience. The confusion stems from conflating short-term performance with long-term financial engineering. Revenue in the NFL is as much about infrastructure as it is about the game itself.
Myth 1: Big Markets Guarantee Big Revenue
On paper, the logic is airtight: more fans, higher demand, greater spending power. Yet the reality is nuanced. The New York Giants and Jets, despite sharing the same market, generate wildly different revenue figures—proof that even in the same city, execution matters. The Giants’ revenue advantage stems from a more aggressive approach to luxury seating, corporate partnerships, and international expansion. Meanwhile, the Jets’ struggles highlight how poor management can erode even the most promising market advantages. Small-market teams like the Tennessee Titans have also defied expectations by leveraging Nashville’s booming economy and a savvy focus on regional sponsorships.
The counterpoint? Some "big-market" teams underperform. The Cleveland Browns, despite being in a city with NFL’s second-largest media market, have historically lagged because of decades of ownership missteps and a lack of investment in fan-facing amenities. Revenue isn’t just about where you play—it’s about how you play the business. The NFL’s revenue-sharing model obscures some disparities, but the top-tier teams in NFL teams ranked by revenue prove that market size is a tool, not a guarantee.
Myth 2: Stadiums Are the Primary Revenue Driver
The allure of a shiny new stadium is undeniable, but its impact on revenue is often overstated. The Atlanta Falcons’ Mercedes-Benz Stadium was a marvel of modern architecture, yet its financial returns have been mixed—partly because the Falcons’ revenue growth predated the stadium’s opening. Meanwhile, the San Francisco 49ers’ Levi’s Stadium became a blueprint for ancillary revenue (concerts, corporate events) but required decades of planning and a relentless focus on non-game-day income. Smaller-market teams like the Indianapolis Colts have thrived not by building megastadiums, but by maximizing the value of their existing facility through creative naming-rights deals and dynamic pricing.
The bigger truth? Stadiums are just one piece of a larger puzzle. The Dallas Cowboys’ AT&T Stadium is a revenue juggernaut, but its success is tied to the Cowboys’ global brand, not the structure itself. Teams like the New Orleans Saints have turned their stadium into a cultural landmark, hosting festivals and concerts that extend their reach beyond football season. Revenue in the NFL isn’t about bricks and mortar—it’s about turning every asset, from merchandise to digital content, into a profit center.
Myth 3: Revenue Sharing Levels the Playing Field
The NFL’s revenue-sharing model is often cited as the great equalizer, ensuring that even the smallest-market teams receive a fair slice of the pie. In theory, this should mitigate the advantages of big-market franchises. Yet the data tells a different story. While revenue sharing does soften the blow for teams like the Arizona Cardinals or the Houston Texans, it doesn’t erase the structural advantages of the league’s elite. The Cowboys, for instance, generate so much in local revenue that even after sharing, they remain in a financial stratosphere. Meanwhile, small-market teams must fight harder to justify their share of the league’s windfalls, often facing skepticism from owners who question their "marketability."
The disparity becomes clearer when examining NFL teams ranked by revenue after sharing. The gap narrows, but it doesn’t disappear. Teams like the Green Bay Packers—where community ownership means profits are reinvested locally—benefit from a different kind of leverage. Others, like the Jacksonville Jaguars, have used shared revenue to fund stadium upgrades that, in turn, boost local revenue. The system isn’t broken, but it’s not a perfect equalizer either. Revenue sharing is a safety net, not a level playing field.

What Holds Up to Scrutiny
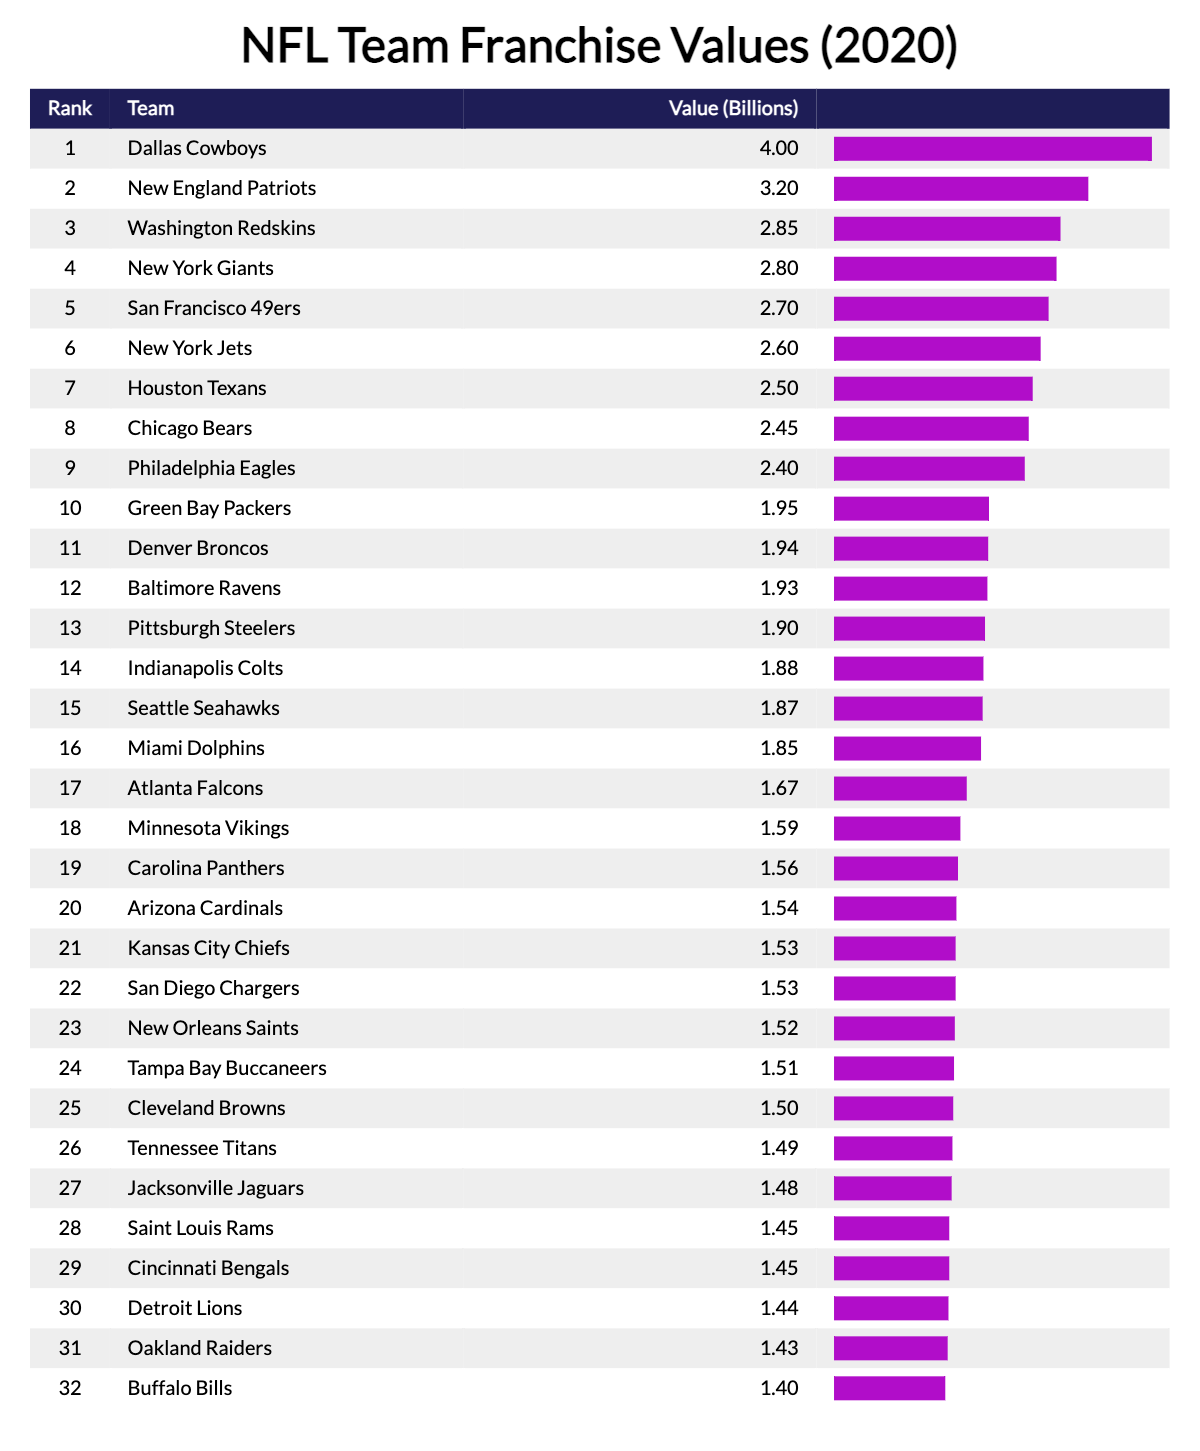
At its core, the hierarchy of NFL teams ranked by revenue reflects two immutable truths: market potential and operational excellence. The top franchises—Cowboys, Giants, 49ers—combine unparalleled local demand with a ruthless focus on monetization. Their playbooks include aggressive luxury seating strategies, global sponsorship activations, and vertical integration (think the Packers’ beer empire or the Patriots’ Gillette Stadium events). These teams don’t just sell tickets; they sell experiences, and the numbers reflect that. The gap between them and the rest isn’t just about money—it’s about how they think.
What’s less discussed is the role of ownership philosophy. The Green Bay Packers’ unique model, where profits are reinvested into the community, creates a self-sustaining cycle of fan loyalty and revenue growth. Meanwhile, teams like the Rams and Raiders have shown that relocation can be a financial reset button—if executed with precision. The evidence suggests that revenue isn’t just a byproduct of success; it’s a driver of it. Teams that invest in fan engagement, digital innovation, and smart partnerships don’t just survive—they dominate.
"Revenue in the NFL isn’t about the game anymore. It’s about treating football like a media company, a retail empire, and a hospitality business all at once."
— Former NFL CFO Andrew Brandt, in a 2023 industry panel
What Holds Up to Scrutiny
| Common Belief | What the Evidence Says |
|---|---|
| Big-market teams always lead in revenue. | Market size matters, but execution—luxury sales, sponsorships, digital—often decides the winner. |
| Stadiums are the biggest revenue driver. | Stadiums are critical, but ancillary revenue (events, merchandise, media) now surpasses game-day income for top teams. |
| Revenue sharing makes all teams equal. | It softens disparities, but the top 5–10 teams still generate so much locally that sharing doesn’t close the gap. |
| Winning teams make more money. | Correlation exists, but revenue growth often outpaces on-field success (e.g., Jaguars’ stadium deal pre-playoff runs). |
Why the Confusion Persists
The NFL’s financial opacity is by design. Unlike publicly traded companies, most teams operate as private entities, shielded from full transparency. Owners, league officials, and even analysts often downplay the role of non-football revenue—sponsorships, licensing, and digital media—because these streams are harder to quantify. The league’s revenue-sharing model also obscures individual team performance, making it difficult to separate hype from reality. When a team like the Bills announces a record-setting season-ticket waitlist, the narrative focuses on fan passion, not the $200 million in luxury suite upgrades that made it possible.
Another layer of confusion stems from timing. A team’s revenue in a given year may spike due to a one-time deal (e.g., a stadium naming rights renewal) or dip because of a slowdown in corporate sponsorships. The Dallas Cowboys’ revenue, for example, isn’t just about football—it’s about their global brand partnerships, which fluctuate with market conditions. Without real-time, granular data, outsiders are left piecing together a fragmented picture. The result? A league where perception often outpaces reality, and where the true drivers of revenue—beyond wins and losses—remain a closely guarded secret.
Conclusion
NFL teams ranked by revenue are more than ledgers; they’re a reflection of the league’s evolution from a regional sport to a global entertainment juggernaut. The top franchises don’t just benefit from their markets—they engineer them, turning every asset into a revenue stream. Yet the story isn’t just about the haves. Teams like the Bills and Titans prove that ingenuity and fan connection can offset geographic limitations. The NFL’s financial ecosystem is a delicate balance: market power, ownership vision, and the ability to adapt to an ever-changing consumer landscape.
The next frontier? International expansion and digital monetization. As the NFL pushes into global markets and explores new revenue models—subscription services, esports adjacencies, and even crypto partnerships—the traditional hierarchy of NFL teams ranked by revenue may shift. One thing is certain: the teams that thrive won’t just ride the wave of success. They’ll shape it.
Comprehensive FAQs
#### Q: How often are NFL team revenues recalculated or disclosed?
NFL team revenues are typically updated annually, though exact figures are rarely made public due to the league’s private ownership structure. Industry estimates—from sources like Forbes, Team Values, and the NFL’s own financial reports—provide snapshots, but these are often lagging indicators. The most recent comprehensive rankings (e.g., Forbes’ 2023 valuations) reflect data from the 2021–2022 seasons, with projections for 2023–2024. The league itself releases aggregated revenue figures (e.g., total league revenue) but not team-specific breakdowns.
####Q: Do NFL teams disclose their revenue sources to fans or the public?
No. While teams occasionally highlight major deals (e.g., a stadium naming rights agreement or a lucrative sponsorship), the bulk of revenue streams—local media rights, luxury suite sales, digital subscriptions, licensing—remain confidential. The NFL’s collective bargaining agreement and private ownership model protect these details. Fans and analysts rely on third-party estimates, industry leaks, and occasional owner interviews to piece together the picture. Even then, figures are often rounded or speculative.
####Q: Can a team’s revenue drop if it relocates?
Relocation can be a double-edged sword. The Raiders’ move to Las Vegas, for example, initially suppressed revenue due to construction delays and a smaller local fanbase, but long-term projections suggest a rebound as the team builds its market. Conversely, the Oakland Raiders’ pre-relocation revenue was stagnant, partly due to the team’s financial mismanagement. The key variable is market development: teams like the Rams in Los Angeles or the Panthers in Charlotte saw revenue surges post-relocation because they invested in growing their new cities’ football cultures. Without that effort, revenue can stagnate or decline.
####Q: How do NFL teams ranked by revenue compare to other sports leagues?
The NFL’s revenue disparity is starker than in other major U.S. leagues. In the NBA, for instance, the top teams (Warriors, Lakers) generate 2–3x more than the bottom (Nets, Hornets), but the gap is narrower because of revenue sharing and smaller market differences. The MLB’s model is even more fragmented, with teams like the Yankees and Dodgers operating as quasi-corporations while small-market clubs rely heavily on local media deals. The NFL’s revenue-sharing system is more aggressive, but the top franchises still pull away due to their scale. For context: the Cowboys’ revenue reportedly exceeds that of entire NBA teams.
####Q: What’s the biggest wild card in NFL revenue today?
The rise of alternative revenue streams—particularly digital and international. The NFL’s streaming deals (e.g., Amazon’s Thursday Night Football) and global expansion (e.g., London games, international series) are reshaping how teams monetize. The top franchises are already leveraging these trends, but smaller markets may struggle to compete without similar infrastructure. Another wild card? Ownership activism. As more teams face pressure from activist shareholders (e.g., the Rams’ sale process), revenue strategies may shift from long-term growth to short-term liquidity—potentially destabilizing the league’s financial hierarchy.
