The Complete Overview of How Much House Can You Afford Based on Net Worth
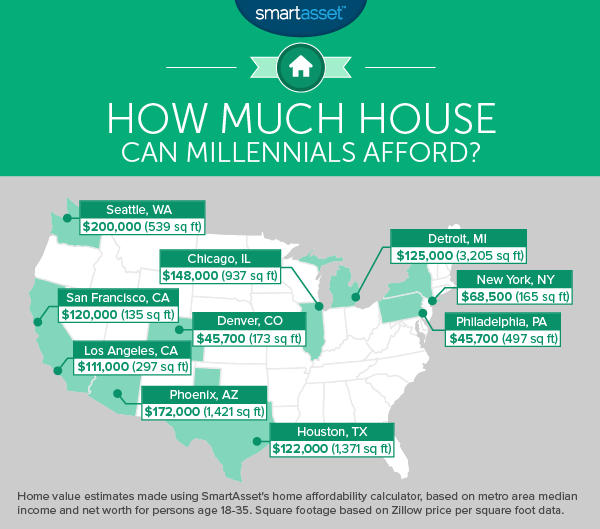
The relationship between net worth and home affordability is a study in financial trade-offs. While lenders fixate on monthly payments, buyers must weigh capital efficiency—how much of their wealth remains accessible after purchase. A $10 million net worth doesn’t mean you can buy a $10 million home; it means you can structure financing to preserve liquidity, diversify risk, or even leverage the property for tax-advantaged cash flow. The key variable is asset allocation: A buyer with 60% in illiquid real estate may need to scale back compared to someone with 70% in publicly traded securities. Industry estimates suggest that for primary residences, buyers with net worths between $1 million and $3 million typically target homes priced 1.5x to 2.5x their liquid net worth, assuming a 20% down payment. Above $5 million, the multiplier often drops to 1x to 1.5x, reflecting the need to maintain diversified portfolios. Yet these figures are fluid. A 30-year-old entrepreneur might afford a larger home than a 60-year-old retiree with identical net worths, simply because their income streams and risk tolerance differ. The question isn’t just "how much house can you afford based on net worth"—it’s "how much house can you afford without derailing your financial plan?"Historical Background and Evolution
Before the 2008 financial crisis, lenders routinely approved mortgages exceeding 100% of a borrower’s home value, assuming property prices would always rise. The aftermath forced a reckoning: net worth became a critical underwriting factor. Today, high-net-worth borrowers (those with $1 million+ in assets) face stricter scrutiny on loan-to-value ratios and cash reserves, even if their income justifies larger loans. The shift reflects a broader trend—banks now prioritize wealth preservation over speculative leverage. Data from the Federal Reserve shows that homeownership rates among the wealthiest 10% of households have stabilized around 75%, down from 85% in the 1980s. The decline isn’t due to affordability alone; it’s a deliberate choice by affluent buyers to optimize asset allocation. A 2022 study by the Urban Institute found that households with net worths above $2 million were 30% more likely to rent long-term in high-cost cities, preferring to deploy capital in private equity or hedge funds. This behavior underscores a fundamental truth: how much house you can afford based on net worth is less about lending limits and more about opportunity cost.Core Mechanisms: How It Works
The math behind "how much house can you afford based on net worth" hinges on three pillars: liquid net worth, debt leverage, and cash-flow sustainability. Liquid net worth—the portion of your assets easily convertible to cash—dictates how much you can put down without disrupting investments. A rule of thumb: Aim for a down payment of 30% to 50% to avoid private mortgage insurance (PMI) and preserve liquidity. For example, a buyer with $2 million in liquid assets might target a $4 million home, using $1.2 million down while keeping $800,000 in reserve for emergencies or market downturns. Debt leverage introduces complexity. While a 30-year mortgage might stretch your budget, a 15-year loan could be more affordable for a high-net-worth buyer due to lower interest costs. However, the trade-off is higher monthly payments, which may conflict with other financial goals like funding a business or charitable giving. Cash-flow sustainability is where most buyers miscalculate. A $5 million home in Miami might have a $25,000 monthly mortgage, but property taxes, insurance, and maintenance could add another $10,000—eating into income that might otherwise generate higher returns elsewhere.Key Benefits and Crucial Impact
The primary advantage of aligning home purchases with net worth is financial flexibility. A buyer who purchases a home priced at 1x to 1.5x their liquid net worth can weather market volatility without liquidating investments. This approach also mitigates the risk of overleveraging, where a single economic shock (job loss, divorce, or divorce) forces asset sales at a loss. Historically, households that adhered to this principle fared better during the 2008 crash, as they retained equity in other assets to cover mortgage shortfalls. Yet the impact isn’t just defensive. Strategic homeownership can enhance wealth accumulation. A primary residence in a high-appreciation market may outperform cash equivalents over decades, while rental properties generate passive income. The catch? Not all real estate is an investment. A buyer’s primary goal—whether it’s lifestyle, legacy, or liquidity—must dictate the purchase. A $3 million penthouse in New York might be a status symbol, but a $1.5 million fixer-upper in Austin could be a cash-flow machine."The best home purchase isn’t the one that maximizes your mortgage—it’s the one that maximizes your options. A high net worth gives you choices, but poor leverage can turn choices into chains." — Jane D. Parker, Wealth Strategist, Parker Capital Advisors
Major Advantages
- Capital preservation: Buying within your liquid net worth ensures you retain access to emergency funds and investment opportunities.
- Tax efficiency: Primary residences offer capital gains exemptions (up to $500,000 for couples), while rental properties provide depreciation deductions.
- Diversification: Real estate correlates poorly with stocks, reducing portfolio volatility over time.
- Legacy planning: A well-structured home purchase can simplify estate transfers, avoiding probate or forced sales.
Comparative Analysis
| Factor | Traditional Lending (DTI-Based) | Net Worth-Based Approach |
|---|---|---|
| Primary Focus | Monthly income and debt payments | Total asset liquidity and long-term goals |
| Down Payment Requirement | Typically 3%–20% | 30%–50% (to preserve cash reserves) |
| Risk Tolerance | Assumes stable employment | Accounts for market downturns and career shifts |
| Opportunity Cost | Ignores alternative investments | Weighs real estate vs. stocks, private equity, etc. |
| Best For | Middle-class buyers with stable incomes | High-net-worth individuals and entrepreneurs |
Future Trends and Innovations
The next decade will see algorithm-driven underwriting that integrates net worth data more deeply into loan approvals. Fintech firms are already experimenting with real-time portfolio analysis, where lenders evaluate a borrower’s entire asset mix—not just their pay stubs. This shift could democratize access to net worth-based mortgages, currently dominated by private banks and wealth managers. Another trend is the rise of "liquidity mortgages," where buyers pledge a portion of their portfolio (e.g., stocks or crypto) as collateral, reducing the need for traditional down payments. While risky, these products appeal to younger high-net-worth individuals who prioritize flexibility over leverage. Meanwhile, geographic arbitrage—buying in lower-cost markets to deploy capital in higher-yield assets—will grow as urban home prices outpace inflation. The question "how much house can you afford based on net worth" will increasingly hinge on global mobility and digital asset integration.
Conclusion
The answer to "how much house can you afford based on net worth" isn’t a fixed percentage or a one-size-fits-all rule. It’s a dynamic calculation that balances liquidity, risk, and opportunity. High-net-worth buyers who treat home purchases as financial tools—not just lifestyle upgrades—will emerge stronger in volatile markets. The goal isn’t to maximize home size but to optimize wealth deployment, ensuring that real estate serves your broader financial strategy. As markets evolve, so too must the conversation around affordability. The days of stretching for the largest mortgage are fading, replaced by a net worth-centric approach that prioritizes resilience over short-term gains. For the affluent, the question isn’t "Can I afford this house?"—it’s "Does this house afford me the future I want?"Comprehensive FAQs
Q: How does age affect how much house I can afford based on net worth?
A: Younger buyers (under 40) can often afford larger homes relative to their net worth because they have longer time horizons to recover from market downturns. Retirees or near-retirees, however, may limit purchases to 1x liquid net worth to avoid depleting savings. Lenders also scrutinize retirement-age borrowers more closely due to reduced income stability.
Q: Should I use my entire net worth to buy a home, or keep some liquid?
A: Financial advisors recommend keeping 6–12 months of living expenses in liquid assets, even after a home purchase. For high-net-worth individuals, this buffer should expand to 18–24 months, especially if you rely on rental income or private equity distributions. Using 100% of your net worth for a down payment leaves no margin for error.
Q: Does buying a home reduce my net worth immediately?
A: Yes, but the impact depends on how you structure the purchase. If you take out a mortgage, your net worth drops by the home’s value minus the loan. However, if you pay all cash, your net worth technically decreases by the full purchase price—though you gain a non-liquid asset with potential appreciation. The key is whether the home’s future returns exceed those of alternative investments.
Q: Can I afford a luxury home if my net worth is high but my income is low?
A: It depends on asset liquidity and cash flow. Some lenders offer asset-depletion mortgages, where they evaluate your ability to sell other assets (e.g., stocks, rental properties) to cover payments. However, this strategy is risky—markets can drop, and selling investments may trigger capital gains taxes. A safer approach is to limit home prices to 1.5x–2x your annual income, even with high net worth.
Q: How does a second home or investment property change the calculation?
A: Investment properties require higher down payments (25%–35%) and are evaluated based on rental income coverage ratios (typically, rent should cover 125%–150% of the mortgage). Your net worth must account for vacancy risks, maintenance costs, and financing gaps. A common rule: Never allocate more than 20%–30% of your liquid net worth to rental properties unless you’re an experienced landlord.
Q: What’s the biggest mistake high-net-worth buyers make when calculating affordability?
A: Overestimating home equity as liquidity. Many assume they can tap home equity via HELOCs or refinancing, but lenders impose strict limits (usually 80% loan-to-value). Additionally, relying on future appreciation to fund lifestyle expenses is dangerous—markets don’t always rise. The safest approach is to treat your primary residence as both a home and a long-term investment, not an ATM.
