
Common Myths About the Net Worth of the US vs. Its Citizens
The most persistent myth is that the net worth of the US can be divided evenly among its population to gauge prosperity. This oversimplification ignores that wealth isn’t distributed like a pie at a dinner table—some slices are far larger, and many are missing entirely. The second falsehood is that the US’s gross domestic product (GDP) is synonymous with its net worth. GDP measures annual economic output, not accumulated assets minus debts. The third misconception treats household wealth as synonymous with national wealth, failing to account for corporate holdings, government assets, or the liabilities that offset them. These myths thrive because they serve political narratives. Critics of wealth inequality point to the net worth of the US as proof of systemic failure, while proponents argue that high national wealth justifies tax cuts for the wealthy. Neither side engages with the messy reality: that the US’s total net worth is a composite of wildly disparate financial ecosystems, and that the number of US citizens doesn’t account for who controls the wealth or how it’s leveraged.Myth 1: "The US’s net worth per capita is proof of broad prosperity."
If you divide the US’s estimated $140 trillion in net worth by its 335 million citizens, you arrive at a figure around $418,000 per person—a number that sounds impressive until you realize it’s a statistical illusion. This calculation includes the value of corporate equities, real estate, and even the Federal Reserve’s holdings, many of which are concentrated in the hands of a tiny fraction of the population. The median net worth, by contrast, is less than $20,000 for the bottom 50% of households. The per capita figure obscures the fact that the net worth of the US is dominated by assets held by the top 10%, while the majority struggle with debt or stagnant wages. The error lies in treating net worth as a linear measure of well-being. A single billionaire’s portfolio can skew national averages without lifting a single worker’s standard of living. Even the Federal Reserve’s own data shows that the bottom 50% of US families hold just 2.6% of all liquid assets. When you strip away the outliers, the number of US citizens in poverty or near-poverty becomes the dominant story—not the headline-grabbing per capita net worth.Myth 2: "The US’s high national wealth means everyone benefits from economic growth."
Economic growth doesn’t trickle down evenly, and the net worth of the US doesn’t guarantee that citizens share in its gains. Since the 1980s, wage growth for the bottom 90% has stagnated, while corporate profits and executive compensation have soared. The S&P 500’s total market capitalization alone exceeds $50 trillion—more than the combined net worth of all US households. Yet stock ownership is concentrated among the wealthy, meaning that even as corporate assets grow, the number of US citizens with direct equity stakes remains a minority. The result? A disconnect where national wealth expands, but individual financial security does not. This myth ignores the role of debt in modern economies. Student loans, mortgages, and credit card debt have ballooned, offsetting the paper gains in home equity or retirement accounts. The net worth of the US might be rising, but for many, that wealth exists only on balance sheets—not in their bank accounts. The Federal Reserve’s Survey of Consumer Finances shows that the median net worth of families under 35 is negative when including student debt. Growth in national wealth doesn’t translate to growth in personal wealth for everyone.Myth 3: "The US’s wealth gap is just a matter of personal responsibility."
Blaming individuals for wealth inequality ignores structural factors tied to the net worth of the US and its distribution. The top 1% own more than the bottom 90% combined, a disparity driven by tax policies, inheritance, and access to capital. The US’s progressive tax system in the mid-20th century shrank inequality, but since the 1980s, tax cuts for the wealthy and deregulation have widened the gap. Meanwhile, the number of US citizens in the middle class has shrunk, with automation and globalization displacing jobs that once provided stable incomes. This myth also overlooks how wealth compounds. A family that inherits $1 million can invest it, generating passive income that further increases their net worth. A family starting from zero must save aggressively, face higher effective tax rates on earnings, and contend with rising costs of living. The net worth of the US may be vast, but its distribution is rigged against those without existing capital.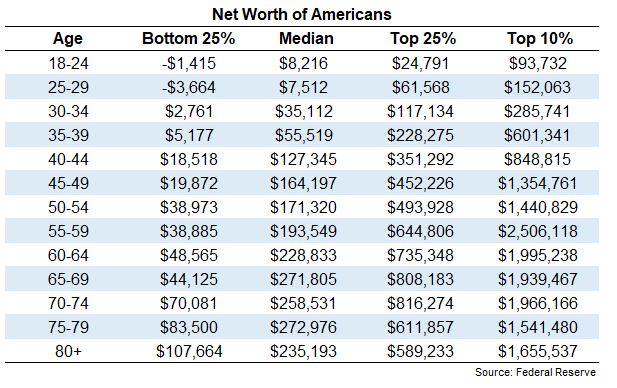
What Holds Up to Scrutiny
The only verifiable truth is that the net worth of the US is a composite of three distinct layers: household wealth, corporate assets, and government holdings. Household net worth—what most people think of when discussing personal finance—accounts for about 60% of the total. Corporate net worth (including equities and real estate) makes up roughly 30%, while the federal government’s net worth (assets minus debts) is negative, offsetting some of the private-sector gains. When you adjust for these layers, the picture becomes clearer: the US’s wealth is concentrated in assets that benefit owners more than workers. The data also confirms that the number of US citizens in poverty or near-poverty has remained stubbornly high despite economic growth. The Supplemental Poverty Measure shows that nearly 37 million Americans lived in poverty in 2022, a figure that doesn’t budge significantly even when GDP rises. This persistence suggests that growth in the net worth of the US isn’t translating to broader prosperity—it’s being captured by those who already hold wealth."Wealth inequality is not an accident. It is the result of policy choices that have systematically favored capital over labor for decades." — Thomas Piketty, Capital in the Twenty-First Century
| Common Belief | What the Evidence Says |
|---|---|
| The US’s net worth per capita reflects individual prosperity. | It’s skewed by corporate and government assets; median net worth is far lower. |
| Most Americans own significant equity in the stock market. | Only about 55% of households own stocks, and holdings are concentrated among the wealthy. |
| Rising GDP means rising living standards for all. | Wage growth has lagged GDP growth since the 1980s, especially for the bottom 90%. |
| Debt is a personal failing, not a systemic issue. | Student loan and mortgage debt have risen alongside stagnant wages, reflecting structural barriers. |
Why the Confusion Persists
The gap between the net worth of the US and the financial reality of its citizens is maintained by two forces: political rhetoric and methodological obfuscation. Politicians on both sides use national wealth statistics to justify their agendas without addressing distribution. Republicans point to high GDP as proof of economic success, while Democrats highlight stagnant wages to argue for wealth redistribution. Neither side engages with the fact that the number of US citizens in financial distress has grown alongside national wealth. Methodologically, the confusion stems from how net worth is measured. The Federal Reserve’s Flow of Funds accounts include corporate equities, real estate, and even the value of intellectual property—categories that don’t directly benefit most citizens. Meanwhile, household surveys focus on liquid assets, ignoring how wealth is concentrated in illiquid forms like homes or private business ownership. The result is a disconnect where the net worth of the US appears robust, but individual financial security remains fragile.
Conclusion
The net worth of the US is a useful metric for macroeconomic analysis, but it tells us little about the financial health of its 335 million citizens. The data reveals a nation where wealth is concentrated in the hands of a few, while the majority grapples with debt, stagnant wages, and eroding social mobility. The myth that national wealth translates to individual prosperity ignores the structural barriers that prevent upward mobility. Without policy changes—such as progressive taxation, stronger labor protections, and investment in public education—the divide between the net worth of the US and the well-being of its people will only widen. The solution isn’t to dismiss the importance of national wealth, but to recognize that its distribution matters more than its total. The US’s economic strength should be measured not just by GDP or net worth, but by whether those gains lift all citizens—or just the elite. Until that changes, the numbers will remain a distraction from the real issue: a system that rewards ownership over effort, and wealth over work.Comprehensive FAQs
Q: How is the net worth of the US calculated?
The Federal Reserve’s Flow of Funds accounts estimate national net worth by summing household assets (cash, stocks, real estate), corporate net worth (equities, intellectual property), and government net worth (assets minus debts). The total is adjusted for liabilities, including mortgages and corporate debt. Unlike GDP, which measures annual output, net worth reflects accumulated wealth over time.
Q: Why does the US’s net worth per capita seem so high?
Because the calculation includes corporate assets (like Apple’s cash reserves) and government holdings, which are concentrated among a small percentage of the population. The median household net worth is far lower—around $188,000—because most Americans don’t own significant equity stakes or large real estate portfolios. The per capita figure is a statistical artifact, not a measure of individual prosperity.
Q: How does wealth inequality affect the US’s net worth?
Extreme inequality distorts the net worth of the US by concentrating assets in the hands of the top 1%. This reduces economic mobility, as wealth begets more wealth through inheritance and investment returns. It also weakens consumer demand, since the middle class—who drive 70% of economic activity—see stagnant wages. High inequality means that even as national wealth grows, the benefits accrue disproportionately to a small group.
Q: Can the US’s net worth decline while the economy grows?
Yes. The net worth of the US can fall if asset prices drop (e.g., during a stock market crash) or if liabilities rise (e.g., increased government debt). Meanwhile, GDP can continue to grow if productivity or consumption remains strong. The two metrics track different things: net worth is a snapshot of accumulated wealth, while GDP measures ongoing economic activity. A recession can shrink net worth while GDP still expands in the short term.
Q: What’s the biggest misconception about the number of US citizens in poverty?
The biggest myth is that poverty is primarily a rural or minority issue. While poverty rates are higher among Black and Hispanic households, nearly 12% of white Americans also live below the poverty line. Additionally, many working families fall into "asset poverty"—lacking savings, retirement accounts, or emergency funds—even if their income technically exceeds the poverty threshold. The number of US citizens in precarious financial situations is far larger than official poverty statistics suggest.
