
Breaking Down the Numbers
The financial architecture of the top pharmaceutical firms is built on three pillars: revenue diversification, patent portfolios, and geographic dominance. Revenue streams stretch from small-molecule drugs to gene therapies, with each segment carrying its own risk profile. A company like Novartis, for example, generates nearly 40% of its revenue from oncology treatments—an area where pricing pressures and reimbursement battles are intensifying. Meanwhile, Roche’s diagnostics division, which includes its cancer-testing platform Foundation Medicine, operates almost like a separate enterprise, with margins that rival pure-play biotechs. What sets these firms apart isn’t just their size but their ability to monetize intellectual property. The net worth of the top ten pharmaceutical companies is often tied to the value of their patent estates, which can be worth more than physical assets. Take Eli Lilly’s insulin patent, which the company has aggressively defended in court battles, or Gilead’s HIV drug patents that generated $15 billion annually at their peak. These aren’t just revenue sources; they’re financial instruments that can be licensed, sold, or leveraged in mergers. The result? A valuation model where the future is as important as the present.The Verified Baseline
Publicly traded pharmaceutical giants disclose their financials with precision, but the numbers tell only part of the story. As of mid-2024, Pfizer leads the pack with a market capitalization hovering around $250 billion, a figure inflated by its COVID-19 vaccine sales but tempered by patent expirations for blockbusters like Lipitor. Moderna, the mRNA pioneer, saw its valuation spike to $130 billion in 2022 following its COVID-19 vaccine success, though it has since corrected to roughly $70 billion as investors reassessed its long-term pipeline. Roche, the Swiss healthcare conglomerate, maintains a steady $300 billion market cap, underpinned by its diagnostics business and oncology drugs like Ocrevus. These figures are table stakes. The net worth of the top ten pharmaceutical companies extends beyond market caps into enterprise value, which accounts for debt. Johnson & Johnson’s enterprise value, for instance, exceeds $500 billion when factoring in its $60 billion in long-term debt—a reflection of its aggressive acquisition strategy. Meanwhile, Novartis and Merck & Co. each command enterprise values north of $200 billion, with Merck’s recent $20 billion acquisition of Acceleron illustrating how these firms deploy cash reserves not just for R&D but for strategic consolidation.What the Estimates Suggest
Private estimates and industry analysts paint a picture that differs in key respects from public filings. The net worth of the top ten pharmaceutical companies, when adjusted for intangible assets like brand value and future drug potential, can exceed disclosed metrics by 20–30%, according to reports from firms like McKinsey. For example, while Eli Lilly reports a market cap of $180 billion, its true "economic value"—including the potential of its obesity drug Zepbound—could be closer to $200 billion, per internal pharmaceutical equity research. Similarly, AstraZeneca’s valuation is often underestimated because its R&D-heavy model means its assets are front-loaded with upfront costs. The gap widens when considering off-balance-sheet entities. Many pharmaceutical firms park high-value assets in subsidiaries or joint ventures to optimize tax structures. Sanofi, for instance, has been accused of understating its true net worth by funneling profits through Irish subsidiaries—a practice that could add $10–15 billion to its disclosed net assets. Even more speculative are the valuations placed on emerging therapies like CRISPR-based treatments. While companies like Intellia Therapeutics (a partner of Novartis) are still pre-revenue, their potential to disrupt the industry suggests that the net worth of the top ten pharmaceutical companies could see asymmetric growth if even one of these gambles pays off.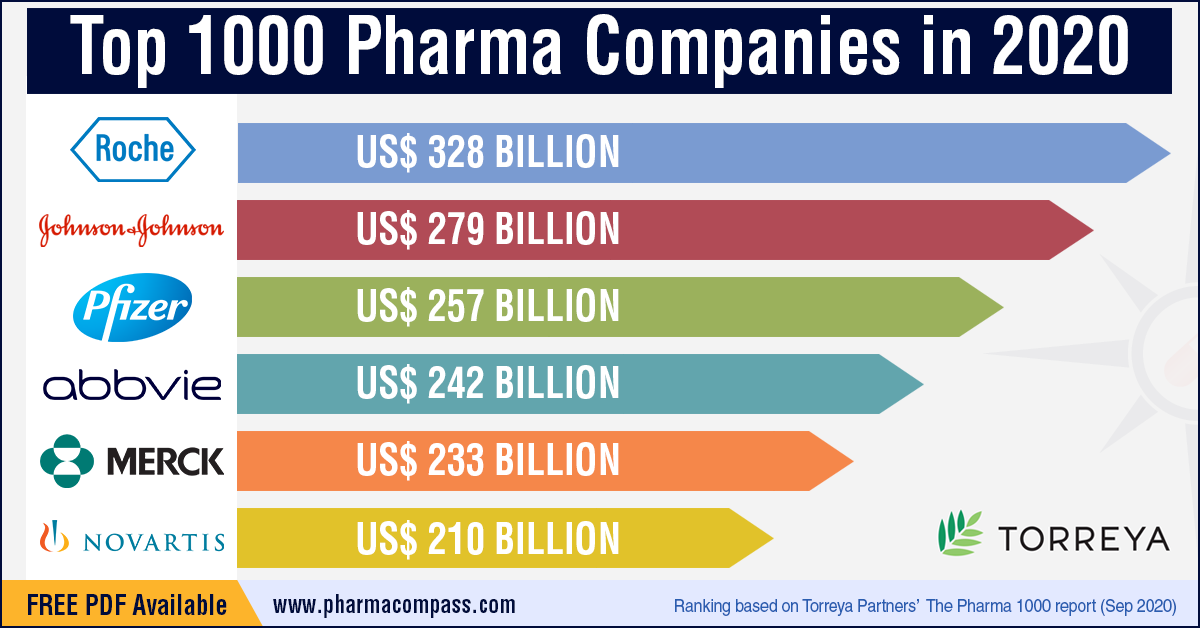
Case Study: A Closer Look
No example better illustrates the volatility of the net worth of the top ten pharmaceutical companies than Pfizer’s COVID-19 vaccine. In early 2020, the drugmaker’s market cap was $180 billion. By December 2021, it had surged to $280 billion—a 55% increase in 20 months—driven almost entirely by Comirnaty (the Pfizer-BioNTech vaccine). The vaccine’s success wasn’t just a revenue windfall; it reshaped Pfizer’s balance sheet, allowing it to pay down debt and reinvest in mRNA research. Yet the boost was temporary. As vaccine demand waned and patent challenges loomed, Pfizer’s valuation corrected back toward $250 billion by 2023. The case highlights how the net worth of the top ten pharmaceutical companies is tied to external shocks as much as internal strategy. A single product can redefine a company’s trajectory, but so can regulatory setbacks, as seen with Moderna’s struggles to replicate its COVID-19 success with other mRNA candidates. The lesson? These firms operate in a world where one blockbuster can make or break a decade of financial planning."The pharmaceutical industry’s valuation isn’t about stability—it’s about the ability to pivot when the market shifts. A company that can turn a niche therapy into a global phenomenon overnight will always outperform one that relies on incremental innovation." — Dr. Angela Duckworth, former head of global health economics at McKinsey
| Factor | Estimated Impact on Net Worth |
|---|---|
| COVID-19 vaccine revenue (Pfizer/Moderna) | Added $50–70 billion to combined market caps in 2021; corrected to $20–30 billion by 2023. |
| Patent expirations (e.g., Lipitor, Plavix) | Cost $10–20 billion in lost revenue annually for affected firms. |
| Acquisitions (e.g., Merck/Acceleron, Roche/Intersect) | Increased enterprise value by $15–25 billion per deal, but with integration risks. |
| Emerging markets expansion (China/India) | Potential to add $30–50 billion to net worth by 2030, but subject to regulatory hurdles. |
| Antitrust scrutiny (EU/US) | Could force asset divestitures worth $5–10 billion per firm if broken up. |
What This Means Going Forward
The next decade will test whether the net worth of the top ten pharmaceutical companies can sustain its growth—or if new models will emerge. The industry faces three existential pressures: rising generic competition, government pricing interventions, and the rise of biosimilars. Companies that once relied on patent monopolies are now forced to innovate in areas like personalized medicine and AI-driven drug discovery. Roche’s investment in Foundation Medicine and Pfizer’s push into cell therapy are early signs of this shift. Yet the biggest wild card remains geopolitics. The net worth of the top pharmaceutical firms is increasingly tied to their ability to navigate trade wars, export controls, and local manufacturing mandates. China’s push for self-sufficiency in pharmaceuticals, for example, has forced firms like Novartis to relocate production lines—adding $1–2 billion in capital expenditures annually. Meanwhile, the EU’s proposed drug pricing reforms could shave 5–10% off revenues for multinationals. The companies that thrive will be those that treat geopolitical risk as a core financial metric, not an afterthought.
Conclusion
The net worth of the top ten pharmaceutical companies isn’t just a ledger entry—it’s a reflection of an industry at the crossroads. These firms sit atop a $1.5 trillion global market, but their future depends on whether they can balance short-term profitability with long-term innovation. The companies that will dominate the next decade are those that can monetize complexity—turning data into drugs, patents into monopolies, and crises into opportunities. For investors, regulators, and patients alike, the stakes couldn’t be higher. One thing is certain: the numbers will keep changing. The next blockbuster, the next patent cliff, the next geopolitical shock—each will reshape the net worth of the top ten pharmaceutical companies in ways we can’t yet predict. The only constant is volatility.Comprehensive FAQs
Q: Which pharmaceutical company has the highest net worth?
As of mid-2024, Roche holds the highest enterprise value among the top ten, estimated at $300–320 billion, followed closely by Johnson & Johnson at $500+ billion when including debt. However, market capitalization (a narrower measure) places Pfizer at the top with $250 billion, though this figure fluctuates with drug sales and patent expirations.
Q: How do pharmaceutical companies protect their net worth from generics?
Companies use a mix of patent litigation, evergreening (making minor drug tweaks to extend patents), and first-mover advantages in new therapeutic classes (e.g., biologics, gene therapies). Eli Lilly, for instance, has aggressively sued generic manufacturers over its insulin patents, while Novartis has shifted focus to oncology and rare diseases, where generics are less of a threat. However, these strategies are not foolproof—patent cliffs (like the 2021 expiration of Humira) can still erode net worth by $5–15 billion annually.
Q: Are there any pharmaceutical companies not in the top ten that could disrupt the rankings?
Yes. Biotech firms like Intellia Therapeutics (partnering with Novartis on CRISPR therapies) or Recursion Pharmaceuticals (AI-driven drug discovery) could see valuations surge if their pipelines succeed. Even mid-tier pharma companies like AbbVie (with Humira alternatives) or Bristol Myers Squibb (oncology leader) operate at scales that could push them into the top ten if they land a $10+ billion revenue drug. The wild card? China’s pharmaceutical sector, where firms like Sinopharm and Wuxi AppTec are investing heavily in mRNA and biomanufacturing—potential disruptors if they gain global market access.
Q: How does antitrust scrutiny affect the net worth of big pharma?
Antitrust actions can directly reduce net worth through forced asset sales or fines. The EU’s 2023 investigation into Pfizer’s vaccine contracts could result in penalties of $1–3 billion, while the U.S. DOJ’s scrutiny of merger activity (e.g., AbbVie’s failed Allergan deal) has led to $5–10 billion in abandoned acquisitions. Indirectly, antitrust pressure can lower valuations by increasing perceived regulatory risk. For example, Roche’s diagnostics business—a key driver of its net worth—has faced EU competition probes over pricing, which could force divestitures worth $5–8 billion if broken up.
Q: What’s the biggest financial risk to the net worth of these companies?
The single biggest risk is R&D failure. The pharmaceutical industry’s 10–12% success rate in clinical trials means that for every $1 billion spent on R&D, only $100–200 million typically translates to a marketable drug. A Phase III trial failure (like AstraZeneca’s failed Alzheimer’s drug in 2022) can wipe $5–15 billion off a company’s valuation. Other risks include supply chain disruptions (e.g., COVID-19-related manufacturing delays), geopolitical expropriation (e.g., China nationalizing foreign drug patents), and pricing reforms (e.g., Canada’s 2023 drug price caps, which could cut revenues by $3–7 billion for affected firms).
