7 Things Worth Knowing About the Net Worth of the Athletic Wear Industry
The athletic wear market’s financial anatomy is complex, but seven core dynamics explain why its total valuation keeps climbing—and why the landscape is more volatile than ever. These aren’t just trends; they’re the structural forces that determine who wins and who loses in this space.1. The $200B+ Valuation Isn’t Just About Clothing Anymore
The net worth of the athletic wear industry has ballooned beyond traditional apparel metrics because the category has expanded into digital experiences, data analytics, and even healthcare. Take Nike, for example: while its footwear and apparel still dominate, Nike Training Club (a free fitness app with 300M+ users) and Nike’s digital sneaker resale platform generate ancillary revenue streams that traditional retail balance sheets don’t capture. Similarly, Lululemon’s community-driven yoga classes and mental wellness partnerships add layers of valuation that extend beyond fabric and stitching. The industry’s total addressable market now includes wearable tech integration, personalized fitness tracking, and even AI-driven sizing recommendations—all of which inflate the sector’s perceived worth. What’s often overlooked is how secondary markets are becoming a financial force. Resale platforms like StockX and GOAT have turned limited-edition sneakers into liquid assets, with some pairs appreciating like collectibles. In 2023, the global resale market for athletic wear was estimated to hit $12 billion, a figure that’s growing faster than primary sales. This parallel economy isn’t just changing consumer behavior; it’s redefining asset valuation within the industry. Brands that once saw resale as a threat now treat it as a growth lever, partnering with platforms to authenticate products and capture a cut of the secondary transaction fees. The result? The net worth of the athletic wear industry is increasingly tied to digital infrastructure as much as physical inventory.2. China’s Factory Floor Still Sets the Price Floor
Despite Western brands’ premium positioning, China remains the undisputed cost arbitrator for athletic wear manufacturing. Over 70% of the world’s athletic shoes are still produced in Chinese factories, where labor costs have stabilized around $0.50–$1.50 per hour—a fraction of what Western workers earn. This isn’t just about cheap labor; it’s about supply chain efficiency. Chinese manufacturers have mastered just-in-time production, allowing brands to pivot designs seasonally without overstocking. When Adidas announced plans to shift 30% of its production to Vietnam and Bangladesh, it wasn’t a cost-saving move—it was a hedge against geopolitical risks after U.S.-China trade tensions escalated. The catch? Quality control and sustainability pressures are forcing brands to rethink this model. Patagonia’s Fair Trade Certified supply chain and Nike’s Move to Zero initiative (aiming for 100% sustainable materials by 2025) signal a shift toward ethically sourced production, which can add 20–40% to unit costs. This trade-off is reshaping the net worth of the athletic wear industry by creating a two-tiered market: one where fast-fashion brands rely on Chinese factories for volume, and another where premium brands pay a premium for ethical compliance. The question isn’t whether China’s dominance will fade—it’s how quickly the industry can absorb the hidden costs of sustainability without eroding margins.3. Direct-to-Consumer Is the New Margin Play
The rise of direct-to-consumer (DTC) brands like Gymshark, Fabletics, and Allbirds has disrupted traditional retail’s profit pools. These companies bypass wholesalers and middlemen, keeping 60–70% of the retail price as gross margin—compared to 30–40% for brands selling through department stores. The strategy works because DTC brands own the customer relationship, using data to personalize marketing and reduce return rates through better sizing algorithms. When Gymshark’s valuation hit $1.3 billion in 2021 (backed by private equity), it wasn’t just about its $500M revenue—it was about its customer lifetime value (CLV), which exceeded $1,000 per user. The downside? Scaling DTC is capital-intensive. Inventory management, last-mile logistics, and customer service require heavy upfront investment. That’s why legacy brands are acquiring DTC startups—not just to access their tech, but to plug into their high-margin distribution channels. When Lululemon acquired Mirror (the smart home gym) for a reported $500M, it wasn’t just about fitness equipment; it was about future-proofing its DTC ecosystem. The net worth of the athletic wear industry is now being measured in tech stack valuations as much as in physical retail square footage.4. Athleisure Isn’t Just a Trend—It’s a Valuation Driver
The athleisure boom—where $100 leggings outsell traditional workout gear—has permanently altered the industry’s revenue mix. Before 2015, athletic wear was a performance-driven category; today, it’s a lifestyle necessity. Lululemon’s Alpine Loop leggings (reportedly selling for $98) became a cultural phenomenon because they blurred the line between gym and streetwear. This shift has inflated the perceived value of casual athletic wear, pushing brands to premiumize even basic items. When Shein launched its athleisure line, it didn’t just copy designs—it redefined price points, proving that $15 leggings could compete with Lululemon’s $100 offerings in certain markets. The financial impact is clear: athleisure now accounts for 40% of Lululemon’s revenue, and Nike’s "Sportwear" segment (which includes hoodies and sneakers) grew 12% YoY in 2023. But the net worth of the athletic wear industry isn’t just about sales—it’s about brand equity. Consumers now treat athletic wear as wardrobe staples, not just functional gear. This has led to higher price elasticity: when Lululemon raised prices by 10–15% in 2022, demand didn’t drop—it stabilized, proving that perceived value now outweighs price sensitivity in this category.5. Sustainability Is a Double-Edged Sword for Valuation
"The future of athletic wear isn’t about cheaper materials—it’s about proving that sustainability can command a premium." — Paul Dillinger, Adidas’ Chief Sustainability OfficerBrands that lead on sustainability are seeing higher multiples in private equity deals, but the path isn’t straightforward. Patagonia’s 1% for the Planet initiative and Worn Wear resale program have made it a cult favorite, with its Worn Wear division generating $100M+ annually. Yet, even Patagonia faces supply chain bottlenecks—its recycled polyester costs 30% more than virgin materials, and organic cotton can add 50% to fabric costs. The challenge? Consumers aren’t always willing to pay the full premium for eco-friendly materials. When H&M’s Conscious Collection underperformed in 2021, it wasn’t because of demand—it was because retailers struggled to communicate the value. The net worth of the athletic wear industry is being recalculated through ESG metrics. Investors now scrutinize carbon footprints, water usage, and labor conditions as closely as revenue growth. Brands that lag on sustainability risk lower valuations in acquisitions. When PVH (parent company of Tommy Hilfiger) acquired Speedo for $440M, one of the key factors was Speedo’s sustainability roadmap—not just its swimwear sales. The message is clear: ESG compliance isn’t a cost—it’s a competitive advantage that directly impacts enterprise valuation.
6. The Resale Market Is a Wildcard for Future Valuations
The secondary market for athletic wear is growing faster than primary sales, and it’s forcing brands to rethink ownership models. Limited-edition sneakers like the Nike Air Max 97 or Adidas Yeezy Boost 350 now appreciate like fine wine. In 2023, a pair of Nike Dunk Low "Panda" resold for $10,000—a 20x markup from retail. This speculative trading is creating a parallel economy where brand equity is tied to scarcity and hype, not just performance. For brands, this is a double-edged sword: while resale drives demand, it also erodes perceived exclusivity if products become too easy to find. The net worth of the athletic wear industry is now being augmented by digital scarcity. Brands like New Balance and Balenciaga have restricted distribution of certain models to drive resale value. Meanwhile, Nike’s SNKRS app (which handles limited drops) has become a profit center in its own right. The resale market isn’t just a side hustle—it’s a financial instrument that brands are learning to monetize directly. When StockX acquired COSSAC (a sneaker authentication firm) for $200M, it signaled that verification infrastructure is now a valued asset in the athletic wear ecosystem.7. Labor Costs Are the Silent Margin Killer
While consumers focus on price tags, the real cost drivers in athletic wear are labor and logistics. In Vietnam, where 60% of Nike’s shoes are made, factory workers earn $180–$250/month—a 30% pay cut from pre-pandemic levels due to inflation. When Adidas factories in Indonesia faced strikes over unpaid wages, production delays cost the company $50M+ in lost sales. These hidden labor costs don’t appear on balance sheets but directly impact margins. Brands that outsource to lower-cost regions (like Ethiopia or Cambodia) often face quality control issues, leading to higher return rates and customer dissatisfaction. The net worth of the athletic wear industry is being tested by labor market dynamics. As Western consumers demand ethical production, brands are caught between rising wages and squeezed margins. When Patagonia increased factory worker pay by 40%, it boosted morale but also reduced unit profitability. The solution? Automation. Companies like Puma are investing in robotics for stitching and assembly, but the upfront costs ($5M–$10M per automated line) are prohibitive for smaller brands. This tech vs. labor tension is reshaping the industry’s financial model, with high-tech brands (like Under Armour’s AI-driven supply chain) gaining a competitive edge over traditional manufacturers.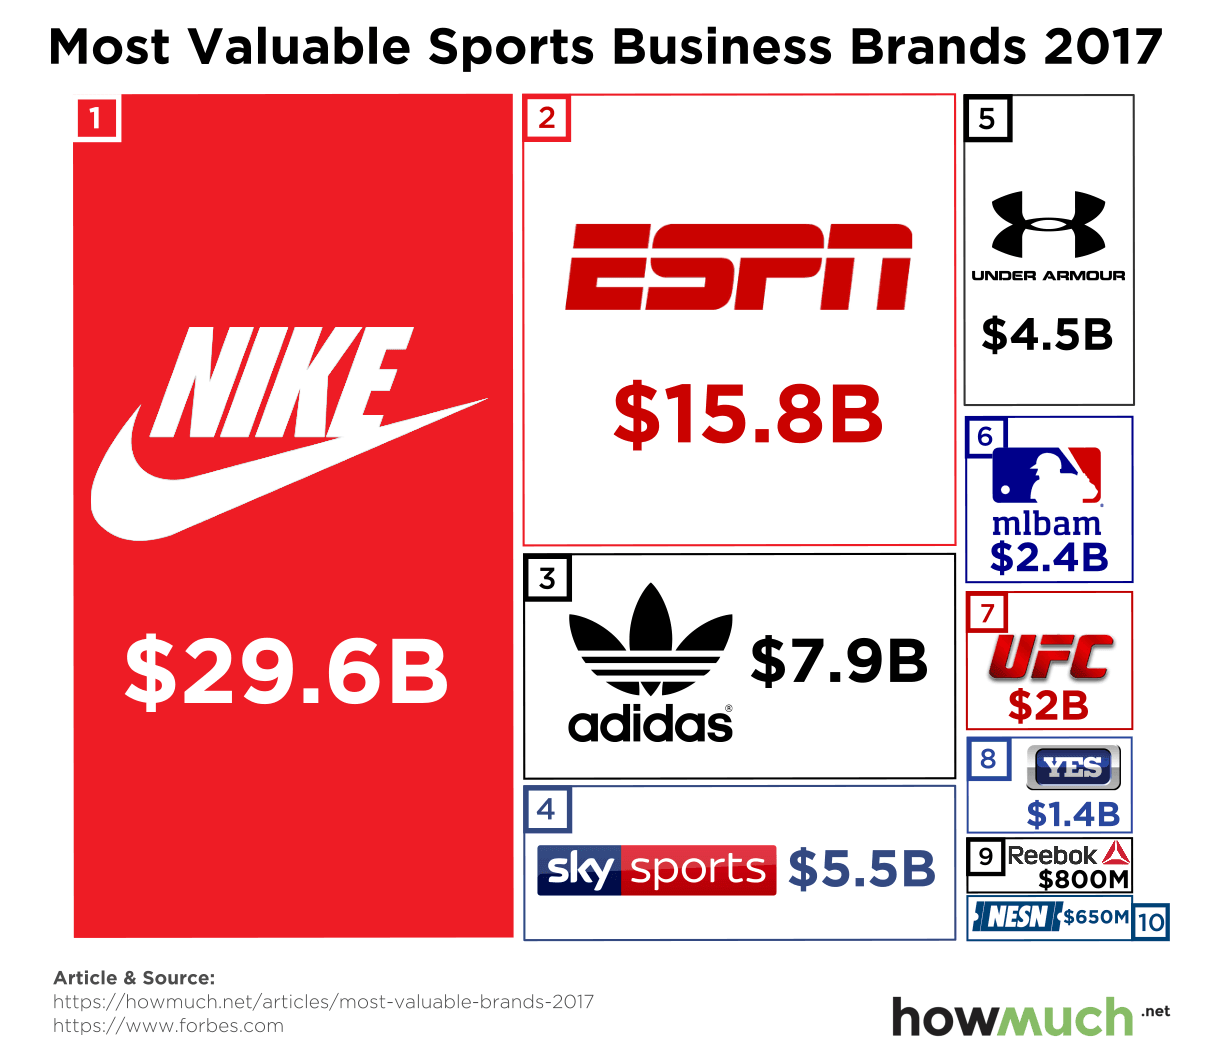
How These Facts Connect
The net worth of the athletic wear industry isn’t just a sum of revenue streams—it’s a network of interdependent forces where technology, labor, and consumer psychology collide. The DTC revolution has compressed margins for traditional retailers but created new valuation benchmarks for digital-native brands. Meanwhile, China’s factory dominance ensures low-cost production, but sustainability demands are forcing a revaluation of supply chains. Athleisure’s lifestyle shift has inflated perceived value, while the resale market has turned limited-edition products into liquid assets. Even labor costs, often overlooked, are silently eroding profitability in ways that balance sheets don’t capture. What emerges is a two-speed industry: one where legacy brands (Nike, Adidas, Lululemon) leverage scale and brand equity, and another where agile startups (Gymshark, Fabletics) disrupt with tech and direct relationships. The net worth of the athletic wear industry is now measured in data points as much as in physical inventory. Brands that master digital infrastructure (AI sizing, resale partnerships, app-driven drops) will outperform those stuck in traditional retail models. The financial future isn’t just about how much the industry is worth—it’s about who controls the levers that determine its value.| Key Dynamic | Financial Impact | Valuation Driver | Risk Factor | Future Outlook |
|---|---|---|---|---|
| DTC Dominance | 60–70% gross margins vs. 30–40% for retail | Customer lifetime value (CLV) | High capital expenditure for scaling | Acquisition targets for legacy brands |
| China’s Factory Control | 70% of global shoe production | Cost efficiency | Geopolitical trade risks | Nearshoring to Vietnam/Bangladesh |
| Athleisure Lifestylization | 40% of Lululemon’s revenue | Premium pricing power | Over-saturation in fast fashion | Hybrid performance-lifestyle designs |
| Sustainability Premiums | 30–50% higher material costs | ESG-driven investor confidence | Consumer price sensitivity | Carbon-neutral supply chains as Moat |
| Resale Market Growth | $12B+ secondary market | Brand equity from scarcity | Authentication fraud risks | Brands monetizing resale platforms |

Conclusion
The net worth of the athletic wear industry isn’t static—it’s a living organism shaped by technology, culture, and geopolitics. The brands that thrive in the next decade won’t just sell clothes; they’ll own the data, control the supply chain, and define the cultural narrative around fitness and style. The DTC wave has only just begun, and the resale revolution is still in its infancy. Meanwhile, sustainability isn’t a checkbox—it’s a competitive weapon that will redefine which brands get acquired at what valuations. The industry’s total addressable market may keep growing, but the distribution of wealth within it is shifting faster than ever. For investors, this means looking beyond P&L statements—they need to assess tech stacks, resale partnerships, and ESG roadmaps. For consumers, it means understanding that athletic wear is no longer just functional gear; it’s a financial asset with appreciating value. And for brands? The message is clear: innovate or be disrupted. The net worth of the athletic wear industry isn’t just about how much it’s worth today—it’s about who will shape its value tomorrow.Comprehensive FAQs
Q: How does the net worth of the athletic wear industry compare to other apparel sectors?
The athletic wear market ($200B+) dwarfs luxury apparel (~$300B total, but with lower volume) and fast fashion (~$150B). Unlike general apparel, athletic wear benefits from higher price points, longer product lifecycles, and stronger brand loyalty, making it a more stable investment despite volatility in trends.
Q: Which brands hold the most value in the athletic wear industry?
Nike ($35B+ market cap), Lululemon ($20B+), and Adidas ($40B+) dominate in brand equity. Private companies like Gymshark (reportedly $1.3B valuation) and Fabletics (acquired by Techstyle for $250M) show how DTC models can create unicorn valuations without traditional retail footprints.
Q: How does sustainability affect the net worth of athletic wear brands?
Brands with strong ESG credentials (Patagonia, Allbirds) command higher acquisition premiums and lower capital costs (e.g., tax incentives for sustainable materials). However, greenwashing risks can depreciate value—investors now scrutinize third-party audits as much as revenue growth.
Q: Is the resale market cannibalizing primary sales in athletic wear?
Not yet. While limited-edition sneakers see resale markups of 10x+, mass-market athletic wear still relies on primary sales. However, brands like Nike are partnering with resale platforms to capture secondary revenue, turning a potential threat into a new profit stream.
Q: What’s the biggest financial risk to the athletic wear industry’s growth?
Labor cost inflation and supply chain fragmentation pose the greatest threats. With Western brands moving production to Vietnam/Bangladesh, wage pressures could erode margins by 10–15% in the next 5 years. Additionally, over-reliance on China leaves brands vulnerable to geopolitical disruptions—a risk that nearshoring can’t fully mitigate.
Q: How are emerging markets changing the net worth of the athletic wear industry?
India and Southeast Asia are becoming growth engines, with middle-class demand for athletic wear rising 15%+ annually. Brands like Decathlon and Nike are localizing supply chains in these regions to reduce costs and latency. Meanwhile, Africa’s fitness boom (driven by mobile apps) could add $5B+ to the market by 2030, but infrastructure gaps remain a hurdle.
Q: Can small brands compete with Nike and Adidas in terms of valuation?
Yes, but through niche specialization. Brands like On Running (acquired by Decathlon for $200M) and Viewpoint (sold to Puma) prove that innovative designs or tech integrations can command premium valuations—even against giants. The key? DTC scalability and patent-protected innovations (e.g., On’s cloud technology).
