The Complete Overview of the Net Worth of Middle Class in the U.S.
The net worth of middle class in the U.S. is a composite of assets—primary residences, retirement accounts, vehicles, and investments—minus liabilities like mortgages, student loans, and credit card debt. For decades, homeownership was the cornerstone of middle-class wealth, but today’s housing market has turned that assumption on its head. The median home price now exceeds $400,000 in many metros, pricing out first-time buyers while older homeowners with paid-off mortgages sit on the bulk of their net worth. Meanwhile, younger middle-class households are more likely to be asset-poor, with liquid savings insufficient to cover three months of expenses—a threshold financial advisors consider the bare minimum for resilience. The data reveals another critical divide: race and ethnicity. White middle-class households hold a median net worth nearly ten times that of Black households and eight times that of Hispanic households, according to the Federal Reserve. This gap persists even after controlling for income, underscoring how wealth is inherited as much as earned. The net worth of middle class in the U.S. is thus not a monolith but a fractured landscape, where geography, education, and family background dictate outcomes far more than sheer effort.Historical Background and Evolution
The post-WWII era through the 1970s saw the net worth of middle class in the U.S. grow steadily as wages kept pace with productivity, unions strengthened, and homeownership became accessible via fixed-rate mortgages. By the 1980s, however, deindustrialization and financial deregulation began reshaping the equation. The Great Recession of 2008 wiped out trillions in household wealth, with middle-class families losing an average of 40% of their net worth. The recovery that followed was uneven: those with existing assets (homeowners, retirees) rebounded quickly, while renters and young adults saw little improvement. More recently, the pandemic-era stimulus checks and remote-work flexibility temporarily inflated the net worth of middle class in the U.S., but those gains evaporated as inflation outpaced wage growth. The S&P 500’s surge benefited those with 401(k)s, while hourly workers saw real earnings stagnate. Historically, the middle class’s wealth was tied to tangible assets; today, it’s increasingly tied to financial markets—a gamble that not all can afford.Core Mechanisms: How It Works
The net worth of middle class in the U.S. is determined by three primary levers: asset accumulation, debt management, and income volatility. Homeownership remains the single largest driver, accounting for roughly 60% of middle-class net worth. Yet with home prices outpacing wage growth in 90% of U.S. markets, younger middle-class families are forced to delay homebuying or accept longer commutes. Retirement accounts—401(k)s and IRAs—are the second-largest asset class, but their value hinges on market performance, which middle-class investors often lack the expertise to navigate. Debt, particularly student loans and medical bills, acts as a drag on net worth. The average middle-class household carries $28,000 in student debt, a figure that can take decades to pay off. Credit card debt, meanwhile, has ballooned to record highs, with middle-class borrowers carrying an average of $6,000 in revolving balances. Income volatility—gig work, layoffs, or underemployment—exacerbates these pressures, making it harder to build savings or pay down debt. The result? A middle class that is wealthier on paper than in decades past, but far more precarious.Key Benefits and Crucial Impact
A robust net worth of middle class in the U.S. isn’t just about financial security; it’s the foundation of social mobility. Families with assets can weather job losses, invest in education, or start businesses—a buffer against systemic shocks. Yet the current state of middle-class wealth tells a different story: stagnant wages, high costs of living, and a housing market that rewards the already wealthy. The impact is visible in declining birth rates, delayed retirements, and a growing reliance on side hustles to make ends meet. The net worth of middle class in the U.S. also shapes political and economic priorities. Policies like student debt relief or expanded child tax credits directly address wealth gaps, but their effectiveness depends on whether they reach the families that need them most. Without intervention, the middle class risks becoming a relic—wealthy in name only, but powerless to change the systems that hold them back."Wealth is not just about money; it’s about options. If you can’t afford to take a sabbatical, send a kid to college, or retire before 70, you’re not truly middle class—you’re just surviving." — Rachel Schneider, economist at the Urban Institute
Major Advantages
- Asset ownership provides a cushion against economic downturns, allowing families to avoid predatory loans or sell assets in emergencies.
- Homeownership builds generational wealth, enabling parents to subsidize their children’s education or first home purchases.
- Retirement accounts offer tax-deferred growth, though middle-class savers often lack access to high-yield investment opportunities.
- Financial stability reduces stress, improving health outcomes and increasing participation in civic life—key markers of a thriving democracy.

Comparative Analysis
| Metric | Middle Class (40th Percentile) | Upper Middle Class (70th Percentile) |
|---|---|---|
| Median Net Worth (2022) | $120,000 | $640,000 |
| Homeownership Rate | 65% | 85% |
| Student Debt Burden | $28,000 per household | $12,000 per household |
| Retirement Savings | $50,000 in 401(k)s/IRAs | $300,000+ in 401(k)s/IRAs |
Future Trends and Innovations
The net worth of middle class in the U.S. will likely face headwinds from automation, climate migration, and policy shifts. Younger generations, saddled with student debt and stagnant wages, may never achieve the wealth levels of their parents. Meanwhile, the gig economy—while offering flexibility—erodes traditional benefits like pensions and healthcare, forcing middle-class workers to rely on side income streams to maintain their net worth. Innovations like automatic retirement savings programs or employer-matched student loan contributions could help, but systemic change requires addressing housing affordability and wage stagnation. Without it, the middle class’s net worth may continue to stagnate, leaving future generations to navigate an economy where wealth is increasingly a birthright rather than an achievement.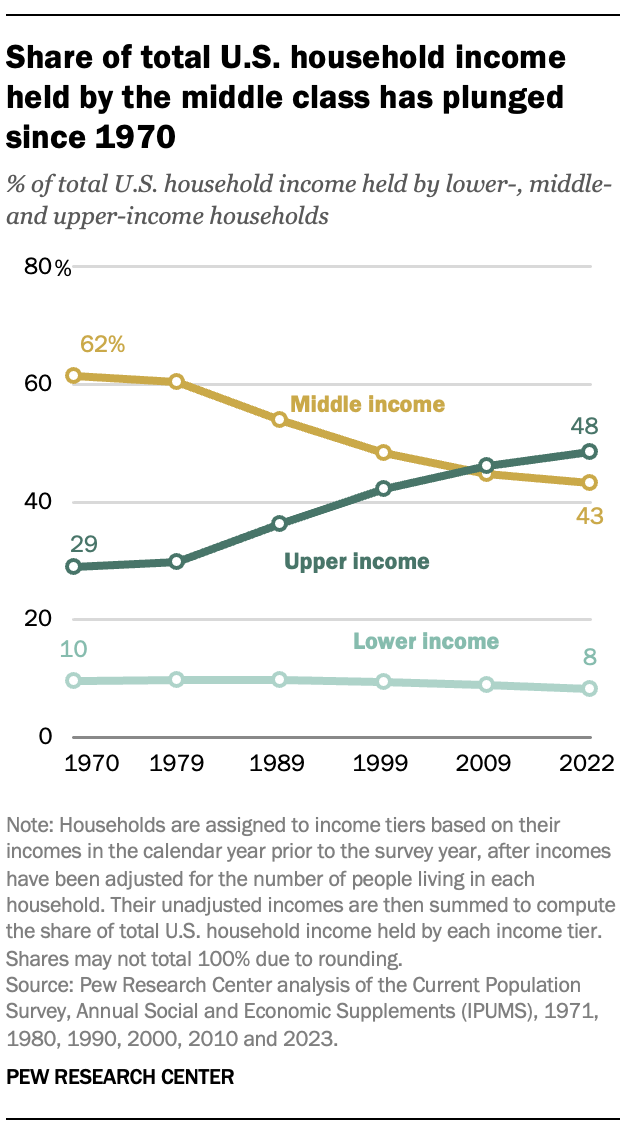
Conclusion
The net worth of middle class in the U.S. is a story of resilience and fragility. On one hand, middle-class families have more assets than ever—thanks to housing markets, retirement accounts, and policy interventions. On the other, those assets are increasingly concentrated among the older, whiter, and more educated segments of the population. The challenge ahead is not just growing wealth, but ensuring it’s distributed in a way that sustains the middle class as the backbone of the American economy. What’s clear is that the net worth of middle class in the U.S. cannot be discussed in isolation. It’s intertwined with healthcare costs, education access, and the shrinking safety net. Without deliberate policy changes, the middle class’s financial foundation will continue to crack—leaving millions one crisis away from falling into poverty.Comprehensive FAQs
Q: How is the net worth of middle class in the U.S. calculated?
The Federal Reserve’s Survey of Consumer Finances defines middle-class households as those in the 40th to 60th income percentiles. Net worth is calculated by subtracting liabilities (debt, mortgages) from assets (home equity, retirement accounts, investments). The median figure for the 40th percentile is currently around $120,000, though this varies by region and demographics.
Q: Why does the net worth of middle class in the U.S. vary so much by race?
Historical factors like redlining, wage gaps, and wealth-building barriers (e.g., inheritance, homeownership access) create persistent disparities. For example, Black middle-class households have a median net worth of $24,100 compared to $188,200 for white households. Policy interventions, such as reparations or targeted savings programs, are often proposed to address this gap.
Q: Can the net worth of middle class in the U.S. recover from inflation?
Recovery depends on wage growth outpacing inflation and asset appreciation. While home prices and stock markets have rebounded post-pandemic, middle-class families with fixed incomes (e.g., retirees) struggle. Younger households may see gains if they enter the housing market during a downturn, but high interest rates currently limit that opportunity.
Q: How does student debt impact the net worth of middle class in the U.S.?
Student debt reduces liquid savings and delays major life milestones like homebuying. The average middle-class household with student loans has a net worth 30% lower than those without. Policies like income-driven repayment or debt forgiveness could alleviate this burden, but political resistance remains a hurdle.
Q: What’s the biggest threat to the net worth of middle class in the U.S. today?
Healthcare costs and housing affordability are the top threats. Middle-class families spend nearly 20% of their income on healthcare, and rising premiums erode savings. Meanwhile, home prices in many cities exceed 10x median incomes, pricing out first-time buyers and forcing older homeowners to tap equity early.
Q: Are there any bright spots in the net worth of middle class in the U.S.?
Yes. Younger middle-class households are leveraging side gigs and remote work to supplement incomes, while employer-sponsored retirement plans (like 401(k) matches) are helping some build wealth faster. Additionally, communities of color are seeing growth in asset-building programs, such as credit unions and cooperative housing models.
