The Complete Overview of the Net Worth of Housing Industry in the US
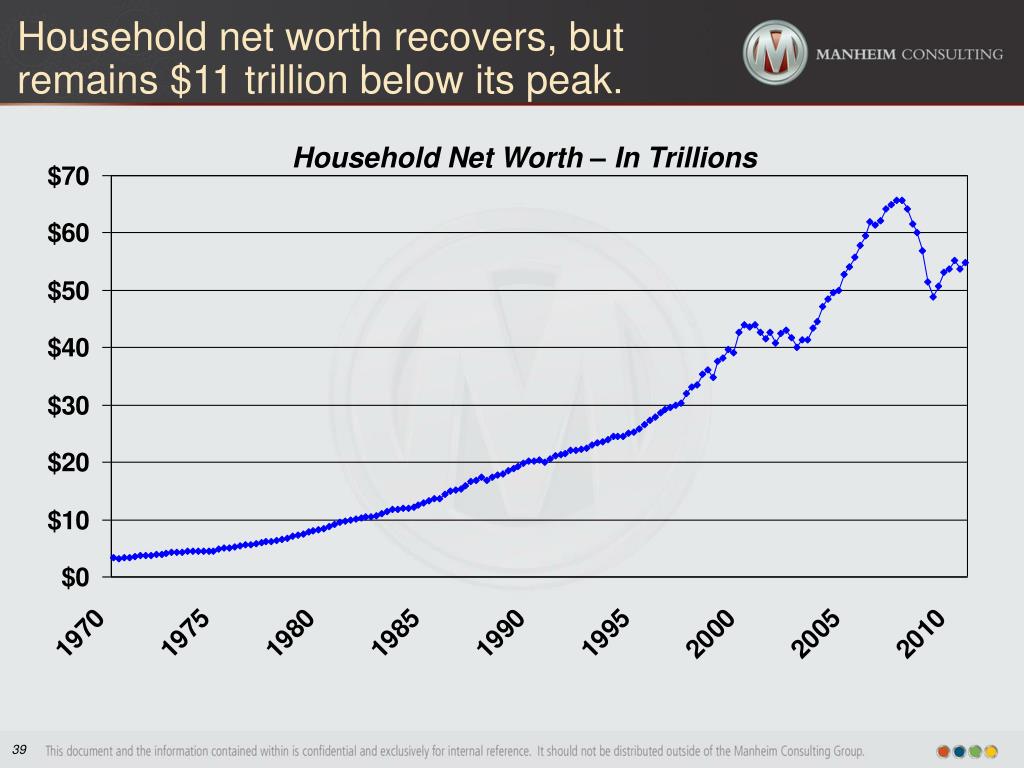
The housing sector’s financial footprint stretches beyond traditional metrics. While Zillow tracks median home values, the broader net worth of housing industry in the US includes commercial real estate, REITs, construction firms, and even the shadowy world of offshore property holdings. The Federal Reserve’s Flow of Funds reports reveal that residential real estate alone accounts for roughly 30% of total household net worth—a figure that surged post-2008 as stock market volatility made homes the safest bet for wealth storage. This dominance isn’t accidental. Decades of tax incentives—like the mortgage interest deduction—have warped behavior, turning homeownership into a forced savings mechanism. Meanwhile, institutional investors now own 1 in 5 single-family homes in some markets, a shift that’s reshaping local economies. The industry’s true value isn’t just in appraisals but in its ripple effects: from school district funding to small business lending tied to property collateral.Historical Background and Evolution
The modern housing industry’s financial might traces back to the New Deal. The 1934 Home Owners' Loan Corporation and 1938 Federal Housing Administration (FHA) didn’t just stabilize markets—they created a system where banks could profit from long-term mortgages. By the 1980s, securitization turned home loans into tradable assets, inflating the net worth of housing industry in the US while obscuring risk. The 2008 crash exposed the fragility of this model, but the recovery saw even deeper integration of housing into global capital flows. Today, the sector operates as a hybrid of local markets and Wall Street strategies. Private equity firms now snap up distressed properties en masse, while tech giants like BlackRock manage billions in real estate investments. The industry’s evolution reflects broader trends: the rise of remote work has hollowed out city centers, while suburban sprawl creates new demand in unexpected places. Understanding its past is key to predicting its next moves.Core Mechanisms: How It Works
At its core, the housing industry’s net worth is a function of three variables: supply constraints, financing innovation, and consumer psychology. Limited land supply in coastal cities keeps prices elevated, while mortgage-backed securities allow banks to lend far beyond local deposits. The Federal Reserve’s interest rate decisions act as a lever—when rates rise, refinancing dries up, and the industry’s valuation contracts. Yet the system isn’t monolithic. Rural markets operate on different rules than Manhattan condos, and investor activity in Florida differs from that in Texas. The net worth of housing industry in the US is also a story of regional disparities: California’s tech-driven boom contrasts with Rust Belt stagnation. Behind every transaction lies a web of appraisers, title companies, and local governments—each extracting value in their own way.Key Benefits and Crucial Impact
Few industries match housing’s ability to concentrate wealth. For middle-class families, a home represents the largest single asset they’ll ever own. When prices rise, equity builds silently—until it doesn’t. The industry’s economic impact is undeniable: construction jobs, property tax revenues, and the collateral that fuels small business loans all trace back to housing’s financial ecosystem. Even during recessions, home values tend to decline slower than stocks, making real estate a hedge against volatility. Critics argue the system is rigged. With 40% of renters spending over 30% of income on housing, affordability crises in cities like San Francisco and New York reveal the dark side of an industry that’s become a speculative asset class. The net worth of housing industry in the US isn’t just about numbers—it’s about who benefits and who gets priced out."Housing isn’t just shelter—it’s the most important financial product most Americans will ever interact with." — Robert Shiller, Nobel laureate and Yale economist
Major Advantages
- Wealth accumulation engine: Homeownership remains the primary way Americans build generational wealth, with equity gains outpacing inflation over decades.
- Economic multiplier effect: Every dollar spent on housing generates $2–$3 in related economic activity through construction, services, and local taxes.
- Stable collateral base: Mortgages and property values underpin trillions in consumer and business lending, from car loans to corporate bonds.
- Policy leverage: Housing-related tax breaks and subsidies (like the mortgage interest deduction) influence federal budgets and electoral priorities.
- Global investor magnet: The US market’s liquidity and scale attract international capital, from sovereign wealth funds to Chinese developers.

Comparative Analysis
| Metric | Housing Industry |
|---|---|
| Total market value (2023 estimates) | $40+ trillion (residential + commercial) |
| Share of household net worth | ~30% (vs. 20% for stocks) |
| Annual transaction volume | $1.5 trillion (residential sales) |
| Employment impact | 12 million jobs (direct + indirect) |
| Policy sensitivity | High (Fed rates, zoning laws, tax codes) |
Future Trends and Innovations
The next decade will test whether the housing industry can adapt. Climate risks—from wildfires in California to hurricane damage in Florida—are already forcing insurers to rethink underwriting. Meanwhile, proptech (property technology) is automating everything from mortgage approvals to virtual tours, but this efficiency comes at a cost: smaller players get squeezed out. The net worth of housing industry in the US may also face pressure from demographic shifts, as millennials delay homebuying and Gen Z embraces co-living models. Regulation could be the wild card. Proposals to tax vacant homes or limit corporate landlords gain traction as inequality widens. If implemented, these changes could reshape the industry’s financial architecture—potentially reducing its net worth while increasing affordability. The biggest question remains: Can the system evolve without collapsing under its own weight?
Conclusion
The housing industry’s financial dominance isn’t going anywhere. Its net worth of housing industry in the US reflects deeper truths about American capitalism: how wealth is created, who controls it, and what happens when the system tilts. The challenges ahead—affordability, climate adaptation, and technological disruption—won’t break the industry, but they will force it to reinvent itself. The question isn’t whether housing remains central to the economy, but whether its benefits will be shared more equitably in the years to come. For now, the numbers tell one clear story: housing isn’t just a market. It’s the foundation of modern American life.Comprehensive FAQs
Q: How does the net worth of housing industry in the US compare to other global markets?
The US housing market dwarfs others in absolute terms—its $40+ trillion valuation exceeds China’s (~$30 trillion) and Europe’s combined. However, as a share of GDP, countries like Canada (120%) and Australia (150%) have higher exposure, reflecting their reliance on real estate-fueled growth.
Q: What role do commercial real estate and REITs play in the industry’s total net worth?
Commercial properties (offices, retail, industrial) add ~$10 trillion to the total, while REITs (real estate investment trusts) hold ~$4 trillion in assets. Together, they account for nearly 40% of the industry’s valuation, though their performance lags residential markets post-pandemic.
Q: How has mortgage debt affected the net worth of housing industry in the US?
Outstanding mortgage debt (~$12 trillion) acts as a double-edged sword: it inflates home values by increasing demand but also leaves owners vulnerable to rate hikes. During downturns, delinquencies can trigger cascading losses across banks and insurers, as seen in 2008.
Q: Are there regional disparities in housing net worth?
Yes. Coastal states (California, New York) see higher valuations due to land scarcity, while Sun Belt states (Texas, Florida) offer more affordable entry points. Rural areas often lag, with home values tied to local economies rather than national trends.
Q: How do housing bubbles form and burst?
Bubbles emerge when speculation outpaces fundamentals—often fueled by easy credit and investor frenzy. The 2008 crash followed subprime lending; today, risks include corporate landlord overleveraging and overbuilding in secondary markets like Phoenix and Las Vegas.
Q: What’s the impact of remote work on housing industry net worth?
Remote work has accelerated suburbanization, boosting demand in lower-cost areas while depressuring urban cores. Cities like Denver and Nashville saw home values surge 20%+ post-pandemic, while NYC and SF experienced slower growth as residents relocated.
Q: Can the government reduce housing costs without crashing the industry’s net worth?
Potential tools include zoning reforms (allowing denser development), tax incentives for first-time buyers, and targeted subsidies for affordable housing. However, aggressive interventions risk destabilizing investor confidence, which could trigger a correction in the industry’s valuation.
