
The Short Answers
- The median net worth of the bottom 50% of Americans is negative or near zero, with many holding more debt than assets.
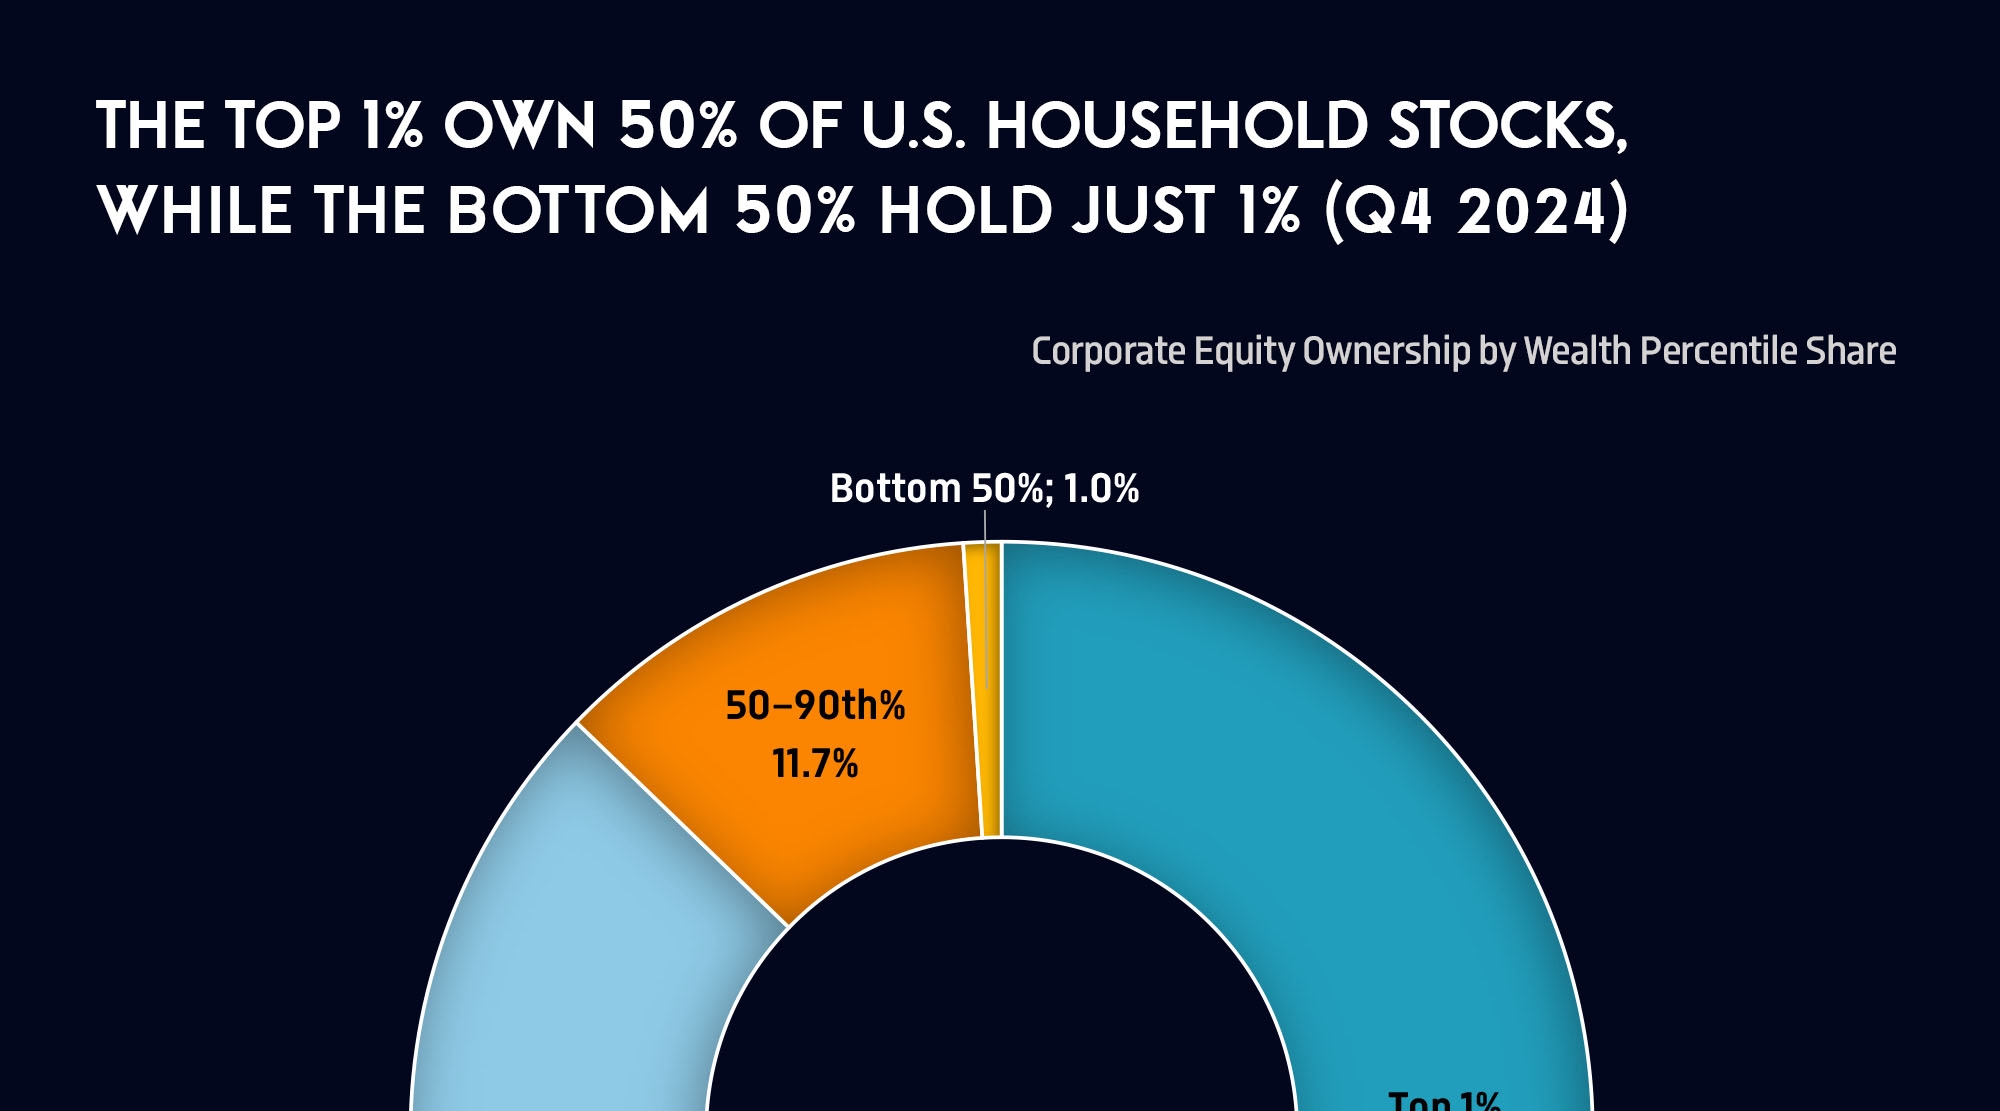
- This group owns less than 1% of total U.S. household wealth, while the top 10% controls nearly 70%.
- Racial disparities are extreme: the median white household in this bracket has 10 times the wealth of the median Black household.
- Student loan debt and medical expenses are the two biggest wealth drains for this demographic.
- Policy changes—like expanding the Child Tax Credit or canceling student debt—could shift these numbers, but political resistance remains strong.
Deep Dive: The Full Picture
The net worth of the bottom 50 percent of Americans is a measure of exclusion as much as it is of economics. When a family’s assets—home equity, savings, investments—are outweighed by liabilities, they are not just poor; they are financially vulnerable in ways that define their life choices. The Federal Reserve’s data shows that 40% of households in this bracket have zero or negative net worth, meaning their debts exceed their assets. For renters, this is often the case by default, as homeownership—a traditional wealth-builder—remains out of reach for most. Even when they do own homes, the equity is often tied up in mortgages or predatory loans, leaving little liquidity for emergencies or investments. The racial divide within this group is one of the most glaring inequalities in the data. A Black family in the bottom 50% is far more likely to be asset-poor, with little to no cushion against economic downturns. The reasons are historical: decades of discriminatory housing policies, wage gaps, and the disproportionate burden of student loans (Black borrowers default at three times the rate of white borrowers). For Hispanic families, the story is similar—though compounded by language barriers and lower access to financial literacy resources. The net worth of these households isn’t just lower; it’s structurally different, with fewer pathways to accumulation.The Context You Need
To understand the net worth of the bottom 50 percent, you must first grasp what wealth means in America. It’s not just about income—it’s about assets that can be leveraged across generations. A home with equity, a retirement account, or even a modest investment portfolio can be passed down or used to weather crises. For the bottom half, these tools are often absent. The median income for this group has stagnated for decades, while essential costs—healthcare, childcare, education—have risen sharply. The result? A wealth gap that has tripled since the 1980s, according to the Economic Policy Institute. The pandemic laid this bare. Stimulus checks provided temporary relief, but the net worth of the bottom 50% still fell by 24% between 2019 and 2020, while the top 10% saw their wealth grow. The reason? Asset price inflation—stocks, real estate—benefits those who already own them, not those who rent or scrape by on gig work. The bottom half’s recovery has been sluggish, with many still paying off pandemic-era debts while facing rising interest rates.The Mechanics
The mechanics of this disparity are well-documented but often overlooked in policy debates. Student loan debt is the single largest liability for young adults in the bottom 50%, with balances averaging $25,000 per borrower—a figure that can take decades to repay. Medical debt follows closely, with 40% of households in this bracket reporting they’ve taken on medical bills they can’t afford. These debts don’t just reduce net worth; they destroy credit scores, limiting access to future loans for homes or small businesses. Then there’s the housing crisis. The bottom 50% is increasingly rent-burdened, with half spending over 30% of their income on rent—the threshold for affordability. Homeownership rates for this group have fallen to 45%, down from 62% in the 1990s. When they do buy homes, it’s often in high-cost areas with little appreciation, or through subprime mortgages that strip equity over time. The net worth of these households is, in many cases, a function of exclusion—from markets, from credit, from the wealth-building tools that benefit higher-income families.Details That Change the Picture
The net worth of the bottom 50 percent isn’t static; it shifts with policy, technology, and cultural attitudes. For example, the expansion of the Child Tax Credit in 2021 temporarily lifted 40% of children out of poverty, but its reversal in 2022 erased those gains. Similarly, the gig economy—while offering flexible work—has reduced net worth for many, as unpredictable incomes make saving impossible. Even public assistance programs, like SNAP or housing vouchers, often fail to bridge the gap between survival and asset accumulation. What’s less discussed is how local economies exacerbate these trends. In high-cost cities like San Francisco or New York, the bottom 50% may earn decent wages by local standards but still struggle to build wealth due to housing costs. In rural areas, stagnant wages and limited job opportunities mean even less opportunity to accumulate assets. The net worth of this group varies dramatically by geography, with Southern states showing the lowest median wealth due to historical underinvestment."Wealth inequality isn’t just about money—it’s about who gets to play by the rules of the game. For the bottom 50%, the rules are stacked against them from birth." — Darrick Hamilton, economist and professor at Ohio State University
| Metric | Bottom 50% vs. Top 10% |
|---|---|
| Median net worth (2022) | $6,700 vs. $1.2 million |
| Homeownership rate | 45% vs. 90% |
| Student loan debt burden | 40% of households vs. 10% |
| Wealth held in stocks/retirement | 1% vs. 50% |
| Likelihood of zero/negative net worth | 40% vs. <1% |

Conclusion
The net worth of the bottom 50 percent of Americans is more than a statistic—it’s a measure of systemic failure. When half the population has little to no wealth, the economy is not just unequal; it’s unstable. Crises hit harder, opportunities are fewer, and the ability to pass down security to the next generation is nearly nonexistent. The data doesn’t lie: this is not an accident of market forces but the result of policy choices, from tax breaks for the wealthy to the erosion of labor protections. Changing these numbers won’t happen overnight, but the tools exist: expanded public housing, student debt relief, stronger unions, and progressive taxation. The question isn’t whether it’s possible to shift the net worth of the bottom 50% upward—it’s whether there’s the political will to try. The alternative is a country where prosperity remains the exclusive domain of the few, while the rest are left scrambling just to stay afloat.Comprehensive FAQs
Q: Why does the bottom 50% have negative or near-zero net worth?
The combination of high debt (student loans, medical bills), low asset accumulation (no homeownership, minimal savings), and stagnant wages pushes many into negative net worth. Even those with jobs often lack the financial cushion to build wealth, especially in high-cost areas.
Q: How does race factor into the net worth of this group?
Racial disparities are deeply embedded. The median white household in the bottom 50% has 10 times the wealth of the median Black household, largely due to historical policies like redlining, wage gaps, and the wealth-stripping effects of student loans. Hispanic households face similar barriers, though the gap varies by generation.
Q: Can the bottom 50% ever accumulate wealth?
Yes, but the barriers are significant. Homeownership is the biggest lever, yet rising costs and credit restrictions make it difficult. Policy changes—like down payment assistance programs or student debt cancellation—could help, but structural issues (low wages, healthcare costs) remain major obstacles.
Q: How does the net worth of this group compare to other developed nations?
The U.S. has far greater wealth inequality than peers like Germany or Canada, where social safety nets and stronger labor protections help the bottom half accumulate assets. In Sweden, for example, the bottom 50% holds 3% of total wealth—still low, but far better than America’s <1%.
Q: What policies could improve the net worth of the bottom 50%?
Key proposals include:
- Expanding the Child Tax Credit (which cut child poverty by 40% when fully funded).
- Canceling student debt (which would boost Black and Hispanic wealth disproportionately).
- Strengthening unions to raise wages for low-income workers.
- Public housing investment to increase homeownership rates.
- Wealth taxes on the top 1% to fund these programs.
Q: How does the gig economy affect the net worth of this group?
Gig work—while offering flexibility—reduces wealth accumulation due to unpredictable incomes, lack of benefits, and no retirement savings. Many gig workers in the bottom 50% can’t afford to save, let alone invest, making long-term wealth-building nearly impossible without policy intervention.
Q: What’s the biggest myth about the net worth of the bottom 50%?
The myth that "hard work alone will fix it." While effort matters, systemic barriers—like predatory lending, wage suppression, and lack of asset-building tools—mean that even those who work full-time often can’t escape negative or near-zero net worth. The data shows this isn’t a personal failure but a structural one.
