
7 Things Worth Knowing About the Net Worth of 44 lbs of Gold
The net worth of 44 lbs of gold isn’t a fixed number. It’s a dynamic equation where the variables include purity, form, market conditions, and even your location. Below are the seven factors that determine whether that weight is a lifeline or a liability.1. The Spot Price Multiplier: Why 44 lbs Isn’t Just 44 Times the Price
At first glance, calculating the net worth of 44 lbs of gold seems straightforward: multiply the current spot price by 44. But gold isn’t traded like wheat. The London Bullion Market Association (LBMA) sets the benchmark for 400-ounce bars, while smaller sizes—like the 1-ounce coins favored by retail investors—carry premiums or discounts that can swing value by 5% or more. For example, if gold trades at $2,400 per ounce, a pure 44-lb bar (which weighs ~691.2 troy ounces) would theoretically be worth $1,658,880. However, buying that same weight in 1-ounce American Eagles could cost $1,700,000+ due to minting, distribution, and dealer markups. The net worth of 44 lbs of gold thus hinges on whether you’re dealing in bulk industrial bars, investment-grade coins, or collectibles—each with its own liquidity premium. The discrepancy widens when you factor in bid-ask spreads. Dealers profit from the difference between buying and selling prices, and spreads are wider for smaller transactions. A high-net-worth buyer purchasing a single 44-lb bar might secure a tighter spread than a retail investor buying 44 individual 1-ounce coins. This isn’t just semantics; it’s the difference between a $100,000 loss and a $150,000 gain on the same physical weight.2. Purity Matters: 24-Karat vs. 18-Karat vs. "Pure" Bullion
Not all gold is created equal. The net worth of 44 lbs of gold plummets if the metal isn’t 24-karat (99.9% pure). Bullion bars and most investment coins meet this standard, but jewelry—even high-end pieces—often contains alloys like copper or zinc to improve durability. An 18-karat gold bracelet (75% pure) would require ~59 lbs of raw 24-karat gold to produce the same net worth as 44 lbs of pure bullion. This explains why gold jewelry resale values lag behind bullion: buyers pay for craftsmanship, not just the metal content. Even within "pure" gold, certifications matter. LBMA-approved bars from refiners like Heraeus or Metalor command higher trust—and thus tighter spreads—than uncertified cast bars. A 44-lb bar from a lesser-known foundry might sell for 5-10% less due to counterparty risk. The net worth of 44 lbs of gold isn’t just about the metal; it’s about the chain of custody that proves its legitimacy.3. Storage Costs: The Silent Eater of Returns
Physical gold doesn’t earn interest. In fact, storage costs can erode its net worth faster than you’d expect. A home safe might suffice for small holdings, but 44 lbs is a $1.7M+ asset—enough to attract thieves or require commercial-grade vaulting. Bank safety deposit boxes typically charge $100–$300/month for high-value items, while private vaults (like those offered by Brink’s or Loomis) can run $1,000–$5,000/year for climate-controlled, 24/7 secured storage. Insurance adds another layer: policies for $1M+ in gold often exceed $5,000 annually, especially if the insurer considers the asset "high-risk" due to its portability. The math is brutal. If you store 44 lbs of gold at a $2,400/oz spot price in a $3,000/year vault, you’re losing ~0.5% annually—before even accounting for price fluctuations. For a retiree relying on gold as a inflation hedge, those costs could turn a $1.7M asset into a $1.6M liability over a decade. The net worth of 44 lbs of gold isn’t just about the metal; it’s about the hidden expenses that turn it into a cost center rather than a store of value.4. Liquidity: Can You Sell 44 lbs Without Tanking the Price?
Gold is liquid—but not infinitely so. Selling 44 lbs in a single transaction requires either a specialist dealer or a private buyer willing to accept the full weight. Most bullion dealers have minimum order sizes (often 1 kg or 32 troy ounces), meaning you’d need to break up your holding into 22 separate sales—each incurring additional fees. The bid-ask spread widens further for large quantities, as dealers hedge their risk by offering lower buy-back prices. In extreme cases, selling 44 lbs could trigger market impact, causing the spot price to dip temporarily as arbitrageurs adjust. For collectors, the problem is worse. Rare gold coins (like 1933 Saint-Gaudens) may have illiquid secondary markets, while custom jewelry could require appraisals, certifications, and auctions—adding 10–20% in transaction costs. The net worth of 44 lbs of gold on paper doesn’t guarantee the same value in hand. If you need cash quickly, you might accept $1.5M instead of $1.7M, depending on how you structure the sale.5. Geopolitical and Macroeconomic Levers
The net worth of 44 lbs of gold isn’t just about supply and demand—it’s about who’s holding the keys. Central banks are the largest gold buyers today, and their actions move markets. When the People’s Bank of China or European Central Bank announce purchases, spot prices rise not because of new mining output, but because of perceived demand shifts. A single $10B gold purchase by a sovereign entity can push prices up 1–2% overnight, directly inflating the value of your 44 lbs. Then there’s the U.S. dollar. Gold and the dollar have an inverse relationship: when the Fed cuts rates or signals inflation concerns, gold rallies. In 2022, a single 25-basis-point rate hike could erase $50,000 from the net worth of 44 lbs of gold if markets priced in tighter monetary policy. Conversely, during crises (like the 2020 COVID selloff), gold surged 20% in months, turning a $1.6M holding into $1.9M. The metal’s value isn’t static; it’s a real-time barometer of global risk sentiment.6. The Tax and Regulatory Minefield
Owning 44 lbs of gold doesn’t just mean managing its value—it means navigating capital gains taxes, VAT, and reporting requirements. In the U.S., selling gold held for over a year triggers long-term capital gains tax (20%), while shorter holdings face ordinary income rates (up to 37%). Some countries (like Germany or Switzerland) impose VAT on gold purchases, adding 7–25% to the cost of acquiring 44 lbs. Then there’s KYC/AML compliance: banks and dealers now scrutinize large gold transactions to prevent money laundering, meaning you may need to justify the source of funds when buying or selling. For high-net-worth individuals, inheritance taxes can be the biggest surprise. In Europe, gold inherited over a certain threshold may face estate taxes of 20–40%, slashing the net worth of 44 lbs by hundreds of thousands. Even storage in foreign vaults can trigger cross-border tax obligations, depending on your residency status. The metal itself is neutral—but the legal framework around it is anything but.7. The Opportunity Cost: What You’re Not Earning Elsewhere
Here’s the brutal truth: gold doesn’t generate income. While stocks yield dividends and bonds pay interest, a 44-lb gold bar sits idle—unless you’re a jeweler or industrial manufacturer. For most investors, holding gold means forgoing the returns of other assets. If the S&P 500 averages 7% annually and gold appreciates 3%, you’re leaving $100,000+ on the table over a decade by not diversifying. The opportunity cost becomes clearer when you compare gold’s performance to inflation. Over the past 50 years, gold has outpaced inflation by ~2% annually, but it’s also underperformed stocks by ~5%. For a retiree with a $1.7M gold position, that’s the difference between $1.9M in a decade (gold) vs. $3M (stocks). The net worth of 44 lbs of gold isn’t just about its current value—it’s about what you sacrifice by not allocating capital elsewhere.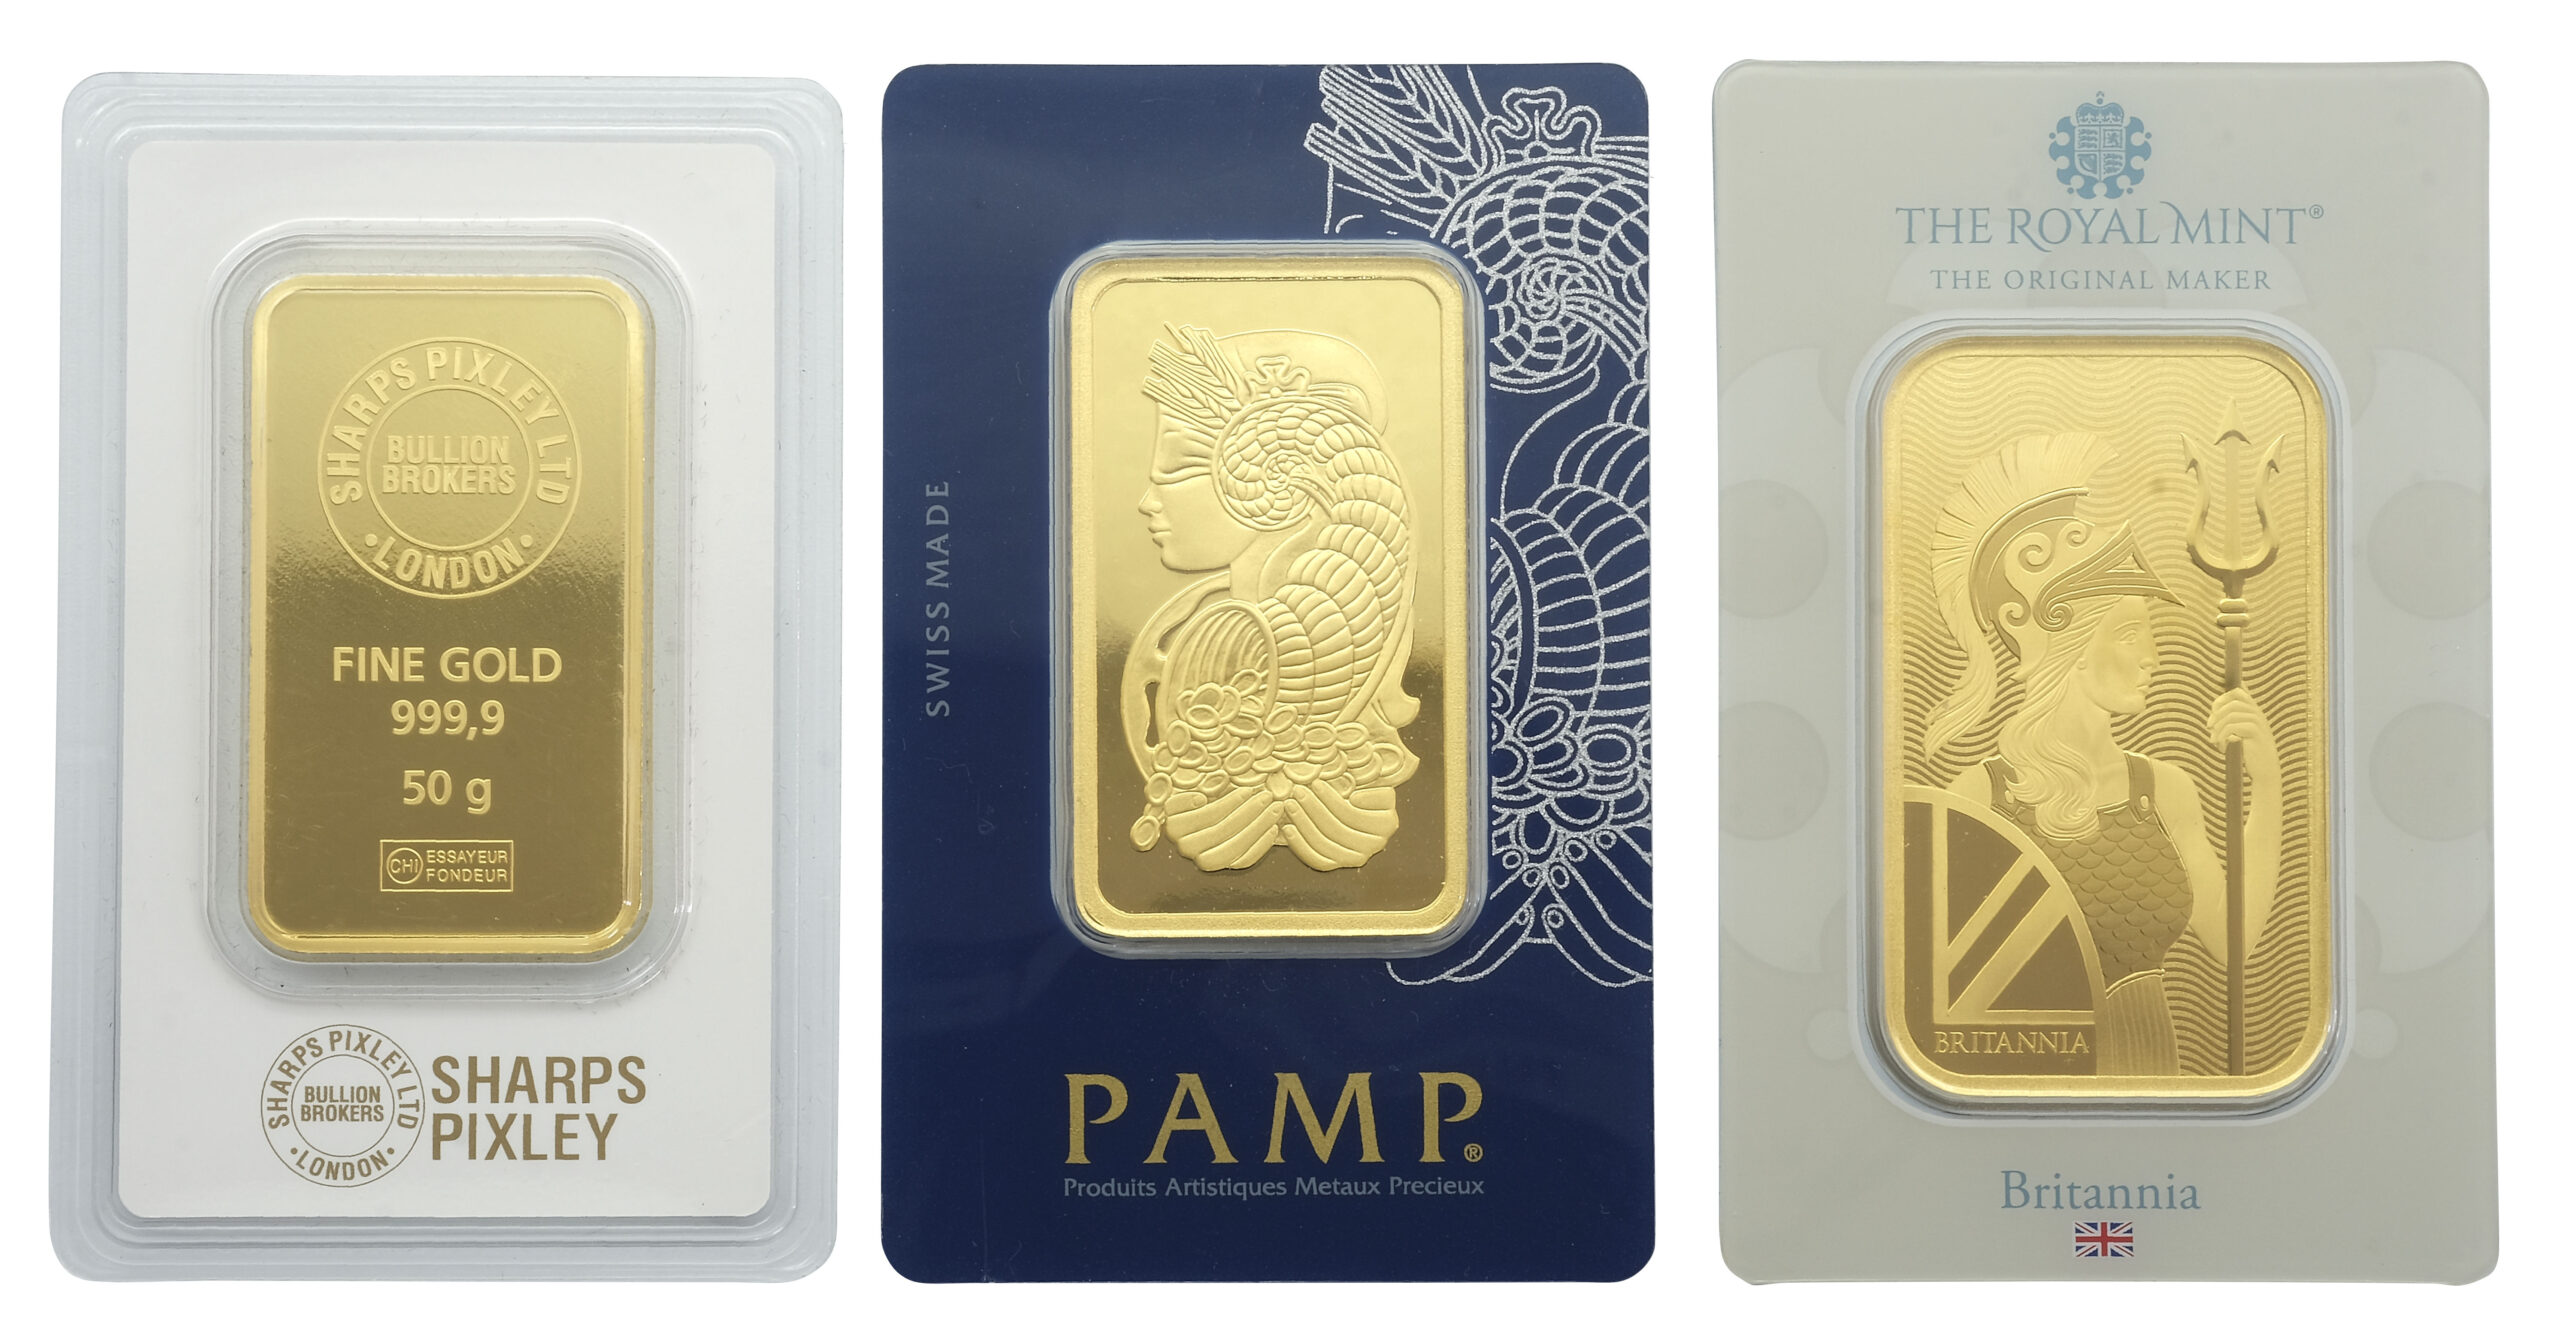
How These Facts Connect
The net worth of 44 lbs of gold isn’t a single number—it’s a constellation of variables that interact in unpredictable ways. Storage costs and liquidity risks don’t exist in isolation; they’re amplified by geopolitical shifts and tax laws. A central bank buying spree might increase your gold’s value by $100,000 overnight, but if you’re forced to sell quickly due to a liquidity crunch, you could lose $50,000 to spreads. Meanwhile, holding gold as a inflation hedge assumes prices will rise—but if inflation cools and the Fed tightens, your $1.7M asset could drop to $1.5M while your bonds or stocks keep climbing. The biggest misconception is treating gold as a passive asset. It’s not. It’s a high-maintenance liability unless you’re actively managing its form, storage, and tax implications. The opportunity cost of holding 44 lbs isn’t just about missing stock market gains—it’s about the time and expertise required to optimize its value. A hedge fund might treat gold as a tactical allocation, but a retiree storing it in a shoebox is playing a different game entirely.| Factor | Impact on Net Worth | Example Scenario |
|---|---|---|
| Form (Bullion vs. Coins vs. Jewelry) | ±5–20% due to premiums/discounts | 44 lbs of 1-oz Eagles: $1.7M+ 44 lbs of 24-karat bars: $1.65M 44 lbs of 18-karat jewelry: $1.2M–$1.4M |
| Storage Costs | 0.3–1% annual erosion | Home safe: $500/year Private vault: $3,000/year (Cumulative loss over 10 years: $30K–$300K) |
| Liquidity Constraints | 5–15% haircut on forced sales | Selling 44 lbs in bulk: $1.5M–$1.6M Selling in small lots: $1.4M–$1.5M |

Conclusion
The net worth of 44 lbs of gold is less about the metal itself and more about how you interact with it. A miner sees it as raw material; a central banker sees it as a reserve asset; a retiree sees it as a nest egg. The same weight can be a fortune, a speculative play, or a money pit, depending on your strategy. The key variables—purity, storage, liquidity, taxes, and macro trends—don’t operate in a vacuum. They’re interconnected, and ignoring any one of them can turn a $1.7M asset into a $1.2M headache. For serious investors, the takeaway is clear: gold is not a set-and-forget asset. It demands active management, from choosing the right form (bullion over jewelry) to structuring storage (vaults over safes) and understanding tax implications. The net worth of 44 lbs of gold isn’t just a number—it’s a living equation, and the variables are always in motion.Comprehensive FAQs
Q: How often does the net worth of 44 lbs of gold change?
The spot price of gold updates continuously, but significant moves (1%+ swings) typically occur daily to weekly due to central bank actions, Fed policy, or geopolitical events. For example, during the 2022 Ukraine war, gold prices jumped $100/oz in a single day, adding ~$70,000 to the net worth of 44 lbs. Intra-day volatility is less pronounced unless trading volumes spike (e.g., during London Fix sessions).
Q: Can I accurately track the net worth of 44 lbs of gold in real time?
Yes, but with caveats. LBMA Gold Price and Kitco provide live spot rates, but your actual net worth depends on:
- The premium/discount for your specific form (e.g., 1-oz coins vs. bars).
- Your bid-ask spread (which varies by dealer).
- Any pending sales or purchases that haven’t settled.
Q: Is 44 lbs of gold enough to qualify as a "significant" holding for tax purposes?
It depends on your jurisdiction. In the U.S., the IRS considers gold over $1,000 in value as a reportable asset, but 44 lbs (~$1.7M) would trigger:
- Form 8300 if purchased with cash over $10,000.
- FBAR reporting if held in foreign accounts.
- Capital gains reporting upon sale.
Q: What’s the most tax-efficient way to hold 44 lbs of gold?
Tax efficiency varies by country, but common strategies include:
- Long-term holding (1+ years) to qualify for lower capital gains rates (e.g., 20% in the U.S. vs. ordinary income rates).
- Self-directed IRAs (in the U.S.), which defer taxes until withdrawal.
- Offshore storage in jurisdictions with no VAT on gold (e.g., Singapore, Dubai), though this introduces reporting complexities.
- Avoiding frequent trading, as short-term gains are taxed at higher rates.
Q: How does insurance affect the net worth of 44 lbs of gold?
Insurance isn’t just an expense—it’s a liquidity and risk factor. For 44 lbs of gold:
- Homeowner’s insurance typically covers $1,000–$5,000 in jewelry/gold; anything above requires a scheduled personal articles floater, costing $500–$2,000/year.
- Commercial vault insurance (e.g., Brink’s, Loomis) runs $1,000–$5,000/year but covers theft, fire, and natural disasters.
- All-risk policies (for collectors) may exclude war or political risk, adding 20–30% to premiums in high-risk regions.
Q: What’s the biggest mistake people make with 44 lbs of gold?
Assuming it’s liquid, low-maintenance, and immune to market risks. The top three mistakes are:
- Storing it at home without proper security, leading to theft or loss (insurance claims for stolen gold spike during holidays).
- Ignoring storage costs, which can erode 0.5–1% annually—silently turning a hedge into a drain.
- Buying at retail premiums without comparing bid-ask spreads across dealers, costing $50K–$100K+ on a $1.7M purchase.
Q: Can 44 lbs of gold be used as collateral for a loan?
Yes, but the terms are harsh. Gold-backed loans typically offer 50–70% LTV (loan-to-value), meaning you’d secure $850K–$1.2M against your $1.7M holding. Key considerations:
- Interest rates are often 5–10%+, higher than traditional mortgages.
- Origination fees can be 1–3% of the loan amount.
- Storage is your responsibility—defaulting means losing both the gold and the loan proceeds.
- Repayment triggers may require selling gold at distressed prices if markets dip.
