
Breaking Down the Numbers
The net worth of 12 million is often misunderstood as a static benchmark, but its real value fluctuates with geography, market conditions, and personal circumstances. In London, where property prices and living costs inflate the cost of maintaining such wealth, 12 million might feel like a mid-tier fortune. In Singapore or Dubai, it could afford a lifestyle most Westerners would envy. The key variable isn’t the number itself but the ratio of assets to liabilities—how much of that 12 million is tied up in illiquid real estate, how much is accessible cash, and how much is exposed to market volatility. Wealth at this level also introduces a psychological shift. Below 1 million, financial stress dominates decisions; above 10 million, the stress often shifts to preservation and legacy planning. The 12 million bracket is where individuals must balance generosity with self-preservation, where philanthropy becomes a tax strategy, and where the temptation to "live the life" can erode capital faster than expected. The margin for error narrows as the stakes rise.The Verified Baseline
Publicly verifiable data on the net worth of 12 million is rare, as high-net-worth individuals rarely disclose precise figures. However, tax filings, property records, and business disclosures occasionally provide snapshots. For example, a mid-career tech executive in Silicon Valley might see their net worth hit this mark after a successful exit, while a European heir might inherit it as part of a trust. In both cases, the verified baseline includes: - Primary residence: Often the largest single asset, valued between £3 million and £6 million in prime markets. - Investments: A diversified portfolio of equities, private equity, or venture stakes, with liquidity varying by holding type. - Business interests: For entrepreneurs, this could mean a minority stake in a scaling company or a fully owned SME generating passive income. What’s rarely public? The offshore accounts, the family trusts, and the unlisted assets that often constitute 30–40% of the total. These are the blind spots where wealth can vanish—or grow—independently of market trends.What the Estimates Suggest
Industry estimates suggest that a net worth of 12 million requires active management to sustain its growth. Passive index investing might yield 5–7% annually, but tax drag, inflation, and lifestyle expenses can erode returns if not planned for. Financial advisors often categorize this bracket as "accumulation phase"—where the focus shifts from aggressive growth to capital preservation and tax optimization. The estimates also highlight a critical divide: - Pre-tax vs. post-tax: After capital gains, inheritance taxes, and living expenses, the effective spending power may be closer to £800,000–£1 million annually in high-tax jurisdictions. - Geographic arbitrage: Relocating to a lower-tax country (e.g., Portugal, Switzerland, or the UAE) can stretch the net worth of 12 million further, but exit taxes and residency rules add complexity.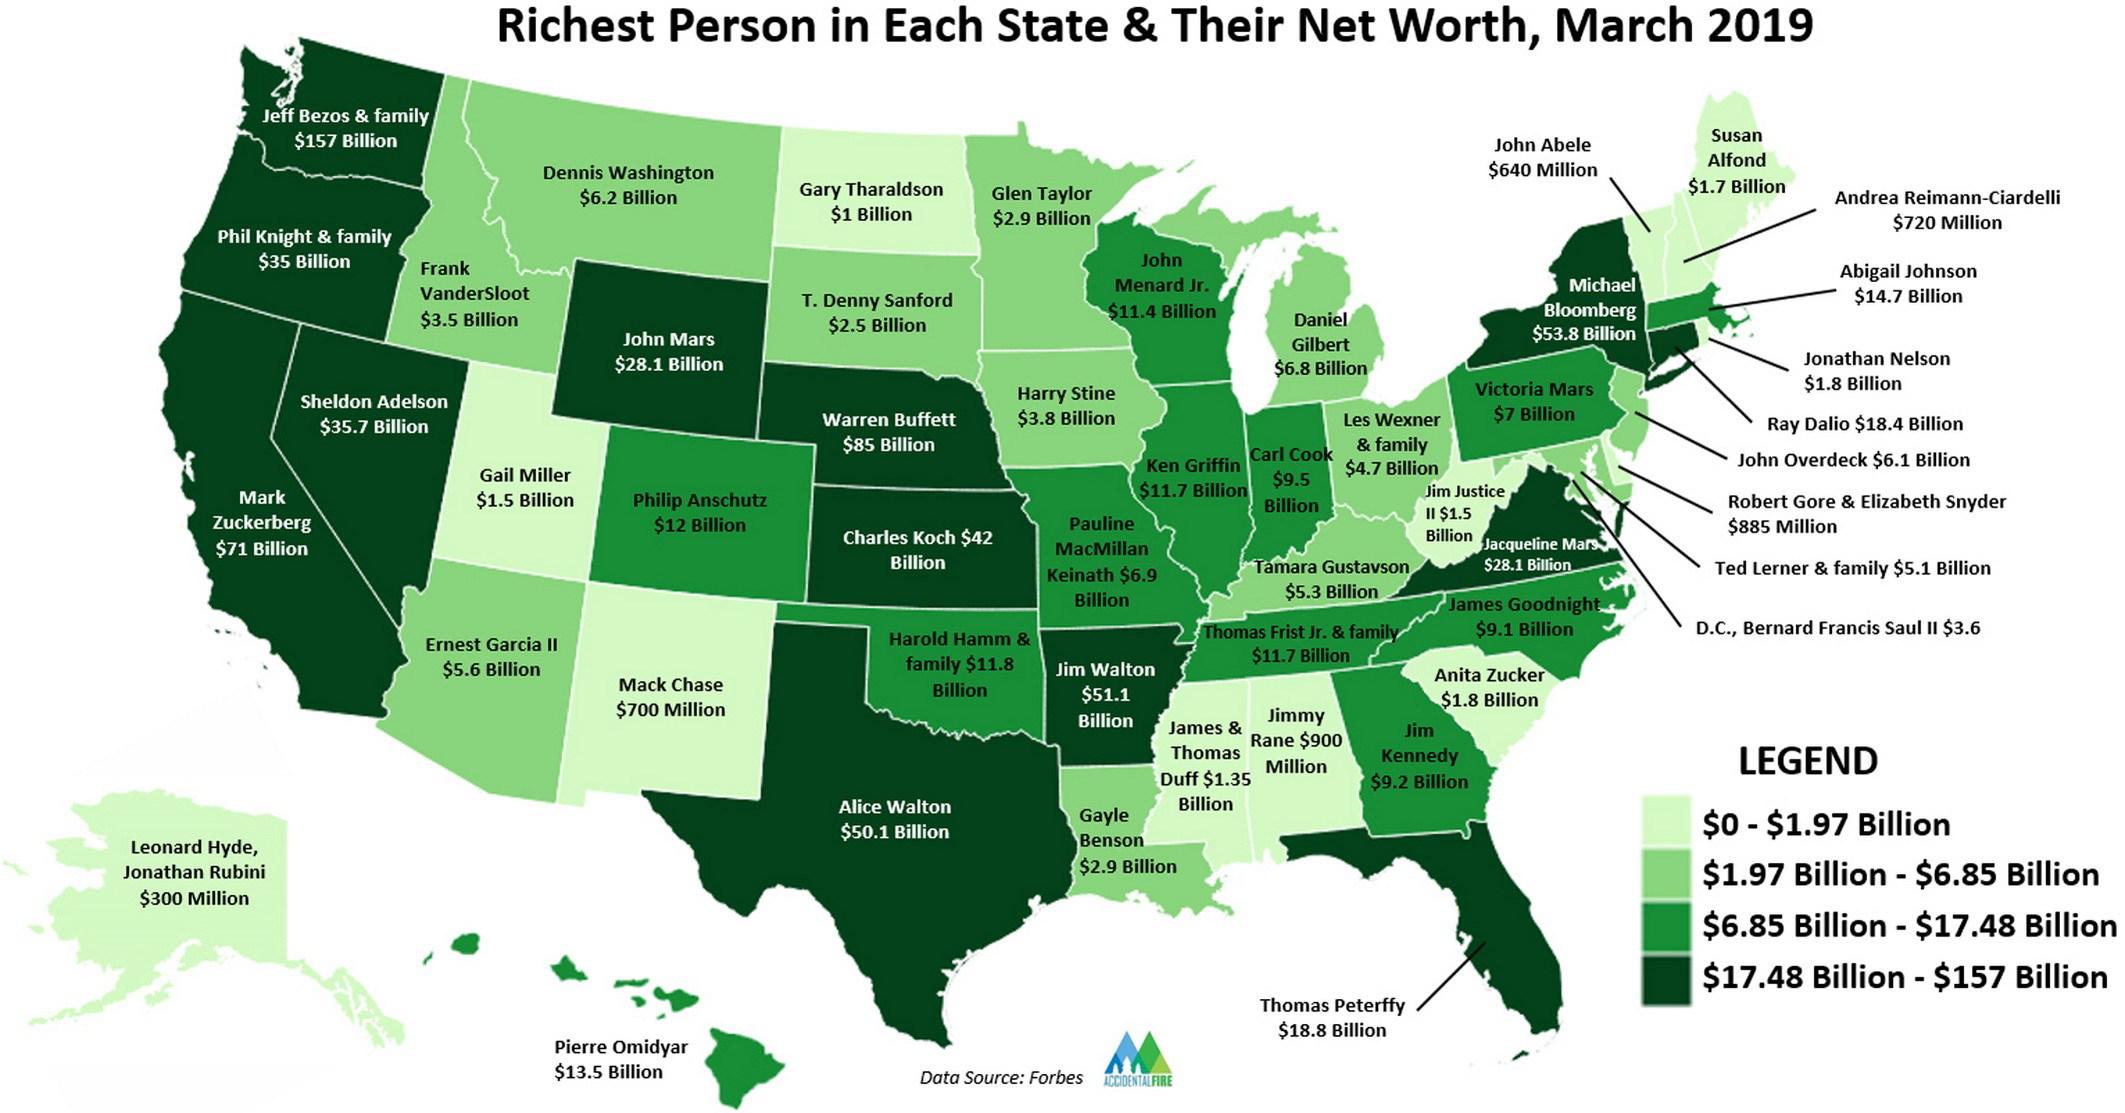
Case Study: A Closer Look
Consider the case of a former fintech founder who sold their company for £15 million at age 42. After fees, taxes, and reinvesting £3 million into a new venture, their net worth settled at £12 million. Their challenge wasn’t earning more—it was deciding what to keep, what to spend, and what to give away. The founder’s first mistake was underestimating lifestyle inflation. A £5 million penthouse in Mayfair, a fleet of luxury cars, and a private jet burned through £2 million in three years—without generating additional income. Their second misstep was failing to diversify beyond cash and blue-chip stocks. When a market correction hit, their portfolio dropped to £10.5 million, forcing them to liquidate assets at a loss to cover living expenses."You think you’re rich until you try to spend like it. The first year was euphoria; the second was panic when the numbers didn’t add up." — Anonymous fintech founder, quoted in a 2022 Financial Times profile
| Factor | Estimated Impact |
|---|---|
| Annual living expenses (UK) | £600,000–£900,000 (varies by lifestyle) |
| Taxes (capital gains + income) | £200,000–£400,000 annually, depending on structure |
| Market volatility (5-year average) | ±£1.5 million (portfolio swings) |
| Philanthropy/legacy planning | £500,000–£1 million (if structured as trusts or donations) |
What This Means Going Forward
For those approaching this threshold, the next decade will be defined by three irreversible choices: 1. Where to live: Tax residency becomes a primary concern. Countries like Monaco or Andorra offer favorable terms but require proof of "economic substance." 2. How to pass it on: Family trusts, dynasty trusts, or outright gifts—each has legal and emotional consequences. 3. What to do with the rest: The "enough" point is subjective. Some retire early; others reinvest aggressively. The biggest risk isn’t losing money—it’s losing control. A single lawsuit, a bad business partner, or an unplanned divorce can dismantle years of accumulation. The net worth of 12 million is a fortress, but fortresses have weak points.
Conclusion
A net worth of 12 million is a milestone, not a finish line. It’s the point where financial freedom becomes a reality, but the work of maintaining it has only just begun. The difference between those who preserve it and those who squander it often comes down to discipline in spending, foresight in tax planning, and humility in recognizing that money alone doesn’t solve problems—it just changes which problems you have. For the rest of us, it’s a useful benchmark. It’s the number that separates the "comfortable" from the "truly independent," the "investors" from the "heirs." And in an era where wealth inequality is a political battleground, understanding what 12 million really buys—and what it really costs—is more relevant than ever.Comprehensive FAQs
Q: Can you live off £12 million comfortably?
A: Yes, but it depends on geography and lifestyle. The 4% rule (spending 4% annually) would yield £480,000/year, but in London or New York, this covers only a moderate lifestyle. In lower-cost regions (e.g., Spain, Malaysia), it stretches further. The catch? Inflation, taxes, and unexpected expenses can derail even this rule.
Q: How do taxes affect a net worth of 12 million?
A: Taxes vary wildly. In the UK, capital gains tax (20–28%) and inheritance tax (40% above £325,000) can eat into growth. In the UAE or Singapore, rates are lower, but residency rules apply. Offshore trusts can defer taxes but add legal complexity. Always consult a cross-border advisor.
Q: Is 12 million enough to retire early?
A: Possibly, but it’s tight. The "FIRE" movement (Financial Independence, Retire Early) often cites £1 million as the target for £40,000/year spending. At 12 million, you could aim for £480,000/year—but healthcare, long-term care, and market downturns are wildcards. Many adjust expectations to "semi-retirement" instead.
Q: What’s the biggest mistake people make with this level of wealth?
A: Overestimating liquidity. Many assume their home or business is "cash," but selling illiquid assets in a downturn can trigger capital gains or lose value. Others fall for lifestyle creep—buying assets (yachts, art) that don’t appreciate and drain cash flow.
Q: Can you lose a net worth of 12 million quickly?
A: Yes. A 20% market crash on a £10 million investment portfolio wipes out £2 million. A divorce settlement, lawsuit, or bad real estate bet can do the same. The key is diversification beyond stocks—cash reserves, tangible assets, and tax-efficient structures act as buffers.
Q: How do you protect a net worth of 12 million from lawsuits or creditors?
A: Asset protection is critical. Strategies include: - Holding assets in trusts (domestic or offshore). - Using limited liability companies (LLCs) for business assets. - Keeping liquid reserves in low-risk, hard-to-seize accounts (e.g., annuities, precious metals). - Avoiding co-signing loans or personal guarantees. Consult a specialist—this isn’t DIY territory.
Q: What’s the psychological impact of hitting this net worth?
A: Freedom and paranoia. Many report relief from financial stress, but others develop fear of loss—obsessing over market moves or hoarding cash. Some struggle with purpose; money no longer solves problems, so identity shifts. Therapy or mentorship can help navigate the transition from "earner" to "preserver."
