
Where It All Began
The origins of the net worth Excel sheet can be traced back to the 1980s, when personal computers began making their way into middle-class households. Before then, tracking wealth was a manual process—ledgers, check registers, and perhaps a yearly review with an accountant. The first financial software, like Quicken (launched in 1983), automated transaction logging but didn’t emphasize net worth as a primary metric. It was the spreadsheet revolution that changed everything. Microsoft Excel, released in 1985, offered a blank canvas for those who wanted more control. Early adopters—often engineers, accountants, and self-taught investors—built their own custom net worth trackers, tailoring them to specific needs like real estate portfolios or complex tax strategies. The early net worth templates were crude by today’s standards. They lacked conditional formatting, data validation, and the sleek dashboards now available in tools like Google Sheets or Notion. But they served a critical function: they made the invisible visible. For the first time, individuals could see their financial lives in real time. The shift from reactive to proactive finance was underway. What began as a niche practice among finance enthusiasts soon spread through word of mouth, particularly in communities where financial transparency was valued—think early internet forums like Reddit’s r/personalfinance or the nascent FIRE (Financial Independence, Retire Early) movement.The Early Signs
By the late 1990s, the net worth Excel sheet had evolved into a cultural artifact. Financial gurus like David Bach and Suze Orman began advocating for regular wealth tracking in their books, though they didn’t always prescribe spreadsheets as the tool. It was the tech-savvy crowd that pushed the envelope. In 2000, a user named "Mr. Money Mustache" (then anonymous) posted a net worth tracking template on a now-defunct forum, detailing how he’d achieved financial independence by age 30. His spreadsheet wasn’t groundbreaking—just meticulous—but it demonstrated how a simple tool could enforce discipline. Around the same time, early bloggers like Ramit Sethi and J.D. Roth were experimenting with personal finance spreadsheets, often sharing them with readers as a way to demystify wealth-building. The dot-com crash of 2000-2001 acted as a stress test for the movement. Those who’d been tracking their net worth fared better, not because the spreadsheets prevented losses, but because they forced a reckoning with reality. The crash exposed a flaw in the early net worth tracking systems: most were static, offering only a snapshot in time. The next generation of trackers would need to adapt to volatility—adding columns for market fluctuations, unemployment buffers, and emergency funds. This was the moment when the net worth Excel sheet stopped being a luxury and became a necessity.The Turning Point
The turning point came in 2008, not with the financial crisis itself, but with the aftermath. As unemployment rates soared and 401(k) balances plummeted, people realized that passive investing wasn’t enough. They needed a way to see their finances in real time, to adjust course before disaster struck. The net worth tracker became a tool for resilience. Financial bloggers who’d been sharing their custom net worth templates suddenly found an audience. Sites like The Simple Dollar and Get Rich Slowly saw traffic spikes as readers scrambled to understand their true financial positions. The crisis also accelerated the shift from Excel to cloud-based tools. Google Sheets, introduced in 2006, gained traction as users sought collaborative solutions—spouses tracking joint finances, parents teaching teens about money. What changed wasn’t just the tool, but the mindset. The net worth Excel sheet was no longer just a ledger; it was a stress test. It revealed how exposed people were to single points of failure—a job loss, a medical emergency, a market downturn. The best trackers began incorporating "what-if" scenarios, allowing users to simulate the impact of layoffs, divorce, or early retirement. This was the birth of the dynamic net worth tracker, one that didn’t just reflect the past but predicted the future. The turning point wasn’t technological; it was psychological. People stopped asking, "How much am I worth?" and started asking, "What could happen to that number tomorrow?""A net worth tracker isn’t about vanity. It’s about vulnerability. The moment you put your numbers on paper, you realize how little control you actually have—and how much you do." — Ramit Sethi, author of I Will Teach You to Be Rich
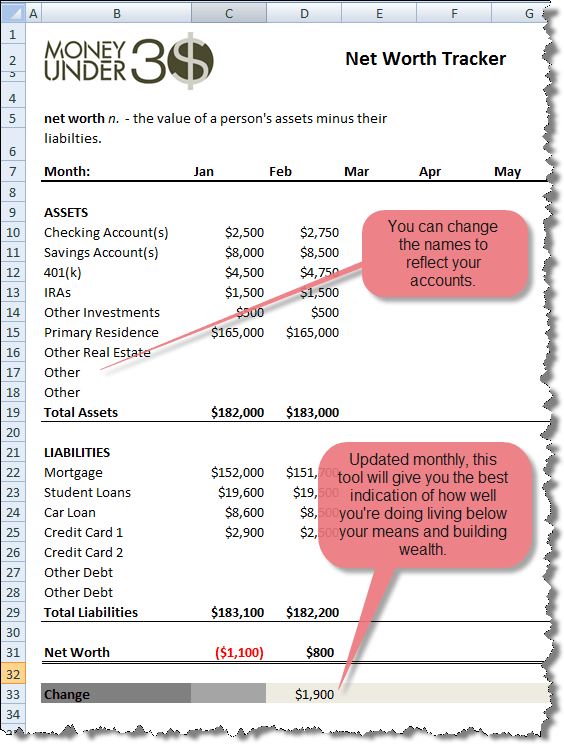
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1985–1995 | Excel becomes the default tool for DIY finance. Early net worth templates emerge, often hand-built by accountants or engineers. Focus is on static snapshots—assets vs. liabilities. |
| 1996–2005 | Internet forums popularize sharing custom net worth trackers. The first "financial independence" communities form, with members tweaking spreadsheets to model early retirement scenarios. |
| 2006–2010 | Google Sheets enters the scene, enabling real-time collaboration. Net worth tracking becomes social—couples and families share spreadsheets to align financial goals. The first automated import tools (e.g., bank feeds) appear. |
| 2011–2015 | Mobile apps (Mint, YNAB) gain popularity, but purists argue that personalized net worth trackers offer more control. The FIRE movement explodes, with bloggers like Mr. Money Mustache refining net worth calculator spreadsheets for aggressive savings strategies. |
| 2016–Present | AI and automation integrate into financial overview spreadsheets, with tools like Tiller Money or Personal Capital offering dynamic updates. The focus shifts to behavioral finance—how tracking net worth changes spending habits and risk tolerance. |
Lessons From the Journey
- Simplicity beats sophistication. The most effective net worth Excel sheets start with two columns: assets and liabilities. Fancy formulas or dashboards come later.
- Consistency is the real currency. Updating a personal wealth tracker monthly—even if just to add a zero—creates discipline faster than any investment strategy.
- Net worth isn’t just a number; it’s a story. The best trackers include notes on major life events (divorce, inheritance, career changes) to contextualize fluctuations.
- Automation is a double-edged sword. While tools like bank feeds save time, they can also create a false sense of security. Manual review of categories (e.g., "cash equivalents") is still critical.
- The spreadsheet is only as good as its user. A custom net worth template won’t prevent bad decisions—it will only expose them faster.
- Privacy matters. Even in the age of shared finances, some people treat their net worth tracker like a diary. Encryption and local files (not cloud-only) may be preferable for sensitive data.
Where Things Stand Today
Today, the net worth Excel sheet exists in a fragmented ecosystem. For the tech-savvy, tools like Notion or Airtable have replaced static spreadsheets, offering databases with tags, filters, and integrations. Apps like Personal Capital or YNAB provide automated tracking, though many users still prefer the control of a DIY net worth tracker. The rise of crypto and alternative assets has also forced adaptations—new columns for Bitcoin, NFTs, or private equity stakes. Meanwhile, the FIRE movement has institutionalized the practice, with communities like r/financialindependence sharing net worth tracking templates as a rite of passage. What hasn’t changed is the core principle: measurement creates accountability. Whether it’s a $500,000 portfolio or a $5,000 emergency fund, the act of tracking net worth forces clarity. The tool itself—whether a Google Sheets net worth tracker or a handwritten ledger—is secondary. The real transformation happens in the mind of the user, who moves from "I hope I’m doing okay" to "Here’s exactly where I stand, and here’s how I’ll adjust."
Conclusion
The net worth Excel sheet is more than a financial tool; it’s a mirror. It reflects not just your balance sheet but your relationship with money—your fears, your ambitions, and your willingness to confront hard truths. The best trackers don’t just add up numbers; they tell a narrative. They show the dip after a layoff, the spike from a bonus, the slow climb of a side hustle. And in an era where financial advice is often one-size-fits-all, the personalized net worth tracker remains one of the most democratic tools in personal finance. It doesn’t require a six-figure income, a trust fund, or even a college degree. All it requires is the discipline to update it—and the courage to look at the result. The next evolution may lie in AI, with tools that predict spending patterns or suggest tax optimizations in real time. But the essence will remain the same: a net worth tracker is only as powerful as the person using it. The spreadsheet won’t make you rich, but it will tell you whether you’re on track—or if it’s time to change course.Comprehensive FAQs
Q: Do I need an advanced net worth Excel sheet, or will a basic template work?
A: A basic template—even one with just two columns—will work for most people. Advanced features like Monte Carlo simulations or automated bank feeds are helpful but not essential. Start simple, then layer in complexity as your needs grow.
Q: How often should I update my personal wealth tracker?
A: Monthly is ideal, but consistency matters more than frequency. If you can’t update monthly, do it quarterly and note why (e.g., "Skipped due to tax season"). The key is to avoid long gaps where the tracker becomes outdated.
Q: Can I use a net worth calculator spreadsheet for joint finances with a partner?
A: Yes, but it requires clear communication. Use a shared tool (like Google Sheets) and decide upfront whether to track assets/liabilities separately or jointly. Some couples prefer two separate trackers that feed into a combined view.
Q: What’s the best way to handle volatile assets (e.g., crypto, stocks) in a financial overview spreadsheet?
A: List volatile assets at their current market value, but include a note (e.g., "BTC: Valued at $X, but subject to 20%+ daily swings"). For long-term tracking, consider averaging costs (e.g., "Cost basis: $Y") rather than relying solely on spot prices.
Q: Are there free net worth tracking templates I can use?
A: Yes. Sites like Vertex42, Microsoft’s Office templates, and personal finance blogs (e.g., The Balance) offer free downloadable net worth Excel sheets. For Google Sheets, search for "net worth tracker template" in the template gallery or adapt a basic budget sheet.
Q: How do I protect sensitive data in my custom net worth tracker?
A: Avoid storing the file in cloud services tied to your email (e.g., iCloud). Use local encryption (e.g., BitLocker for Windows) or password-protected ZIP files. For digital files, consider a secondary email or a tool like Cryptomator for extra security.
Q: Can a net worth tracker help me retire early?
A: Indirectly. It won’t guarantee early retirement, but it will show you whether you’re on track to meet your FIRE number (25x annual expenses). The tracker reveals leaks (e.g., lifestyle inflation) and opportunities (e.g., untapped side income) that accelerate progress.
