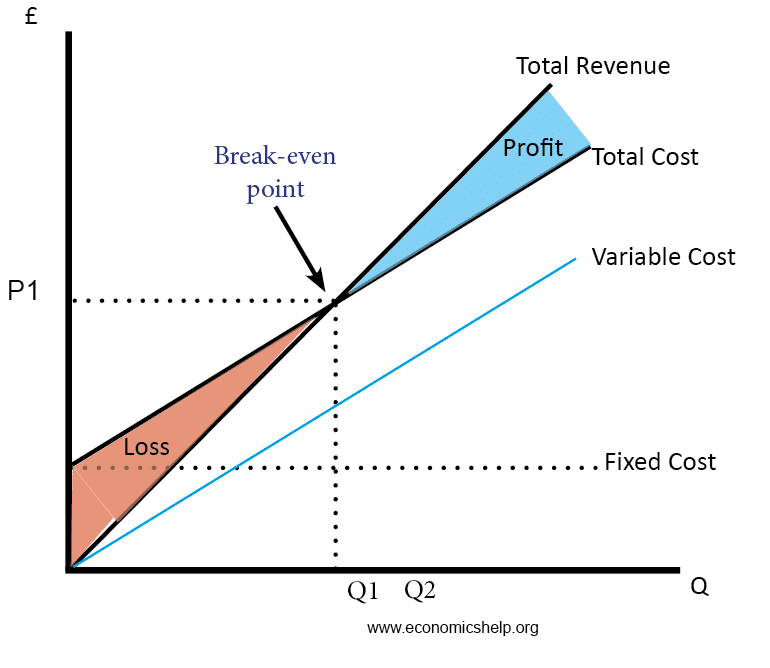
Common Myths About Net Worth Break-Even Refinance Calculators
The assumption that refinancing is always beneficial if rates drop ignores the broader financial ecosystem. Many homeowners believe that if their mortgage rate is higher than current market rates, refinancing is a no-brainer—without considering how it affects their overall net worth trajectory. This oversimplification leads to decisions that may save on interest but erode long-term equity. Another persistent myth is that the break-even point is purely a function of time. Some calculators reduce refinancing to a "payback period" metric, treating it as a race to recoup closing costs. In reality, the net worth break-even refinance mortgage calculator must account for tax implications, changes in home value, and how the refinance alters your debt-to-equity ratio. Ignoring these variables can turn a seemingly smart move into a wealth-draining one. #### Myth 1: Refinancing is always worth it if you save on monthly payments The logic here is straightforward: lower payments mean more disposable income, which should theoretically improve net worth. However, this ignores the opportunity cost of tying up capital in a longer loan term. A net worth break-even refinance mortgage calculator reveals that extending a mortgage—even at a lower rate—can delay wealth-building by locking in debt for years longer than originally planned. For example, a homeowner who refinances from a 15-year to a 30-year term may save on monthly costs but could end up paying thousands more in interest over time, offsetting any short-term gains. The calculator also exposes the hidden trade-off: the savings from lower payments might not fully offset the reduced equity growth if the home appreciates slowly. In high-cost markets where home values stagnate, the net worth impact of refinancing could be neutral or even negative. The key insight is that refinancing isn’t just about cash flow—it’s about how that cash flow interacts with your broader asset portfolio. #### Myth 2: The break-even point is the same for everyone Calculators that use a one-size-fits-all approach to break-even analysis fail to account for individual financial profiles. A young professional with high liquidity needs may prioritize cash flow over long-term equity, while a retiree might care more about minimizing debt. The net worth break-even refinance mortgage calculator must factor in variables like tax brackets, investment returns, and retirement timelines. For instance, a homeowner in a high tax bracket might benefit more from deducting mortgage interest, while one in a low bracket could see minimal tax advantages. The break-even point also shifts based on home equity. A homeowner with 80% equity might refinance to access cash, but the calculator must weigh whether that cash is used for wealth-generating investments (e.g., stocks, business ventures) or lifestyle expenses (e.g., vacations, non-essential purchases). The latter could erode net worth faster than the refinancing saves. #### Myth 3: You should refinance as soon as rates drop below your current rate This reactive approach ignores the transaction costs and long-term implications. A net worth break-even refinance mortgage calculator reveals that refinancing too frequently can be costly—each time you refinance, you reset the clock on closing costs, which can add up. For example, refinancing every two years to chase lower rates might save on interest in the short term but could cost thousands in fees over a decade. The calculator forces a more disciplined approach: it asks whether the rate drop is significant enough to justify the break-even period and the long-term net worth impact. Additionally, market conditions matter. In a rising-rate environment, refinancing might lock in a rate that becomes unfavorable if rates later drop further. The calculator must model scenarios where future rate movements could make the refinance decision obsolete—or profitable—before the break-even point is reached.What Holds Up to Scrutiny
At its core, the net worth break-even refinance mortgage calculator operates on two verifiable principles: 1. Time-value of money: The calculator discounts future savings and costs to their present value, accounting for inflation and investment returns. 2. Equity dynamics: It models how refinancing affects home equity growth, whether through reduced principal payments or cash-out options. These principles are backed by empirical data. Studies on mortgage refinancing behavior show that homeowners who refinance based solely on rate drops often underperform those who consider net worth implications. A 2022 Federal Reserve report found that refinancers who extended loan terms saw median net worth growth lag behind non-refinancers over a five-year period—unless they used the proceeds for high-yield investments. The calculator’s strength lies in its ability to simulate different scenarios. For instance, it can compare: - A rate-and-term refinance (lowering payments without cashing out equity). - A cash-out refinance (using equity for investments or debt consolidation). - The impact of refinancing on retirement planning or emergency funds."Refinancing isn’t about the loan—it’s about the leverage it provides or restricts. The best calculators don’t just crunch numbers; they tell you whether the move aligns with your wealth-building strategy." — David Bach, Financial Author and Wealth Strategist
| Common Belief | What the Evidence Says |
|---|---|
| Refinancing saves money if the rate drops by 1% or more. | The break-even point depends on closing costs, loan term, and how the savings are reinvested. A 1% drop might not justify refinancing if fees eat into the savings for years. |
| Cash-out refinancing is always risky. | Risk depends on how the cash is used. If deployed into assets with higher returns than the mortgage rate, it can boost net worth. If used for non-essential expenses, it may not. |
| The break-even point is the same as the payback period. | The break-even point considers net worth growth, not just cost recovery. A shorter payback period doesn’t guarantee a positive net worth impact. |

Why the Confusion Persists
The primary reason for misconceptions is the lack of standardized tools. Many online calculators focus on payback periods or monthly savings without integrating net worth projections. Lenders and real estate agents often push refinancing based on rate differentials, not holistic financial planning. This creates a disconnect between what’s marketed as "saving money" and what actually improves long-term wealth. Another factor is behavioral economics. Homeowners tend to anchor their decisions on recent rate movements or emotional triggers (e.g., fear of missing out on lower rates). The net worth break-even refinance mortgage calculator forces a more analytical approach, which requires time and financial literacy—two resources not everyone has. Without clear guidance, homeowners default to simplistic rules of thumb, leading to suboptimal outcomes.Conclusion
The net worth break-even refinance mortgage calculator isn’t just a financial tool—it’s a framework for aligning mortgage decisions with wealth-building goals. Its power lies in shifting the focus from short-term savings to long-term equity. Yet its potential is often undermined by oversimplified advice or calculators that ignore critical variables like tax impact, investment returns, and home value trends. For homeowners, the takeaway is clear: refinancing should be a calculated move, not a reactive one. The calculator doesn’t eliminate risk—it reframes it. By integrating net worth projections, it helps distinguish between refinancing that accelerates wealth and refinancing that merely postpones it.Comprehensive FAQs
Q: How does the net worth break-even refinance mortgage calculator differ from a standard refinance calculator?
A standard refinance calculator typically focuses on monthly savings and payback periods, ignoring how the decision affects your overall net worth. A net worth break-even refinance mortgage calculator incorporates factors like home equity growth, tax implications, investment returns, and changes in your debt-to-equity ratio. It asks not just "Will I save money?" but "Will this move improve my long-term financial position?"
Q: Can I use this calculator if I have other debts, like credit cards or student loans?
Yes, but the calculator must account for how refinancing interacts with your broader debt strategy. For example, if you use a cash-out refinance to pay off high-interest credit cards, the calculator should model whether the new mortgage rate is lower than the credit card APR—and whether the savings outweigh the cost of extending your mortgage term.
Q: Does refinancing always reduce my monthly payment?
Not necessarily. While refinancing often lowers payments by extending the loan term or securing a better rate, some refinances—especially cash-out options—can increase monthly obligations. A net worth break-even refinance mortgage calculator will factor in whether the trade-off (e.g., higher payment for access to cash) aligns with your financial goals.
Q: How do tax implications factor into the break-even analysis?
Taxes play a critical role. For instance, mortgage interest deductions may reduce taxable income, but refinancing could eliminate this benefit if you switch to a non-deductible loan. The calculator should compare your marginal tax rate against the interest savings to determine the true net benefit. In high-tax states, the deduction can significantly alter the break-even point.
Q: What if my home’s value has dropped since I bought it? Does that affect the calculation?
Absolutely. If your home is underwater or has limited equity, refinancing options may be restricted, and cash-out refinances could be off the table. The calculator must adjust for reduced equity, as it limits your ability to access capital or secure favorable terms. In such cases, a rate-and-term refinance might be the only viable option.
Q: Should I refinance if I plan to sell the home in the next few years?
Probably not. The break-even period for refinancing is often longer than the time you’ll own the home. A net worth break-even refinance mortgage calculator will show that the costs of refinancing (closing fees, reset clock on loan term) may not be recouped before you sell. In this scenario, the calculator’s output would likely advise against refinancing unless the rate savings are extraordinary.
Q: How often should I run this calculation to stay on track?
At least annually, or whenever major life or financial changes occur—such as a job change, inheritance, or shift in investment strategy. Market conditions (e.g., rising rates, home value fluctuations) also warrant recalculating. The goal is to ensure your refinancing decision remains aligned with your evolving net worth objectives.
Q: Are there scenarios where refinancing hurts net worth even if it lowers my payment?
Yes. For example, extending a loan term to lower payments reduces the principal paid over time, which can slow equity growth. If home values stagnate, the reduced principal payments may not be offset by appreciation. Additionally, if you use refinancing proceeds for non-wealth-generating expenses (e.g., luxury purchases), the net worth impact could be negative despite lower monthly costs.