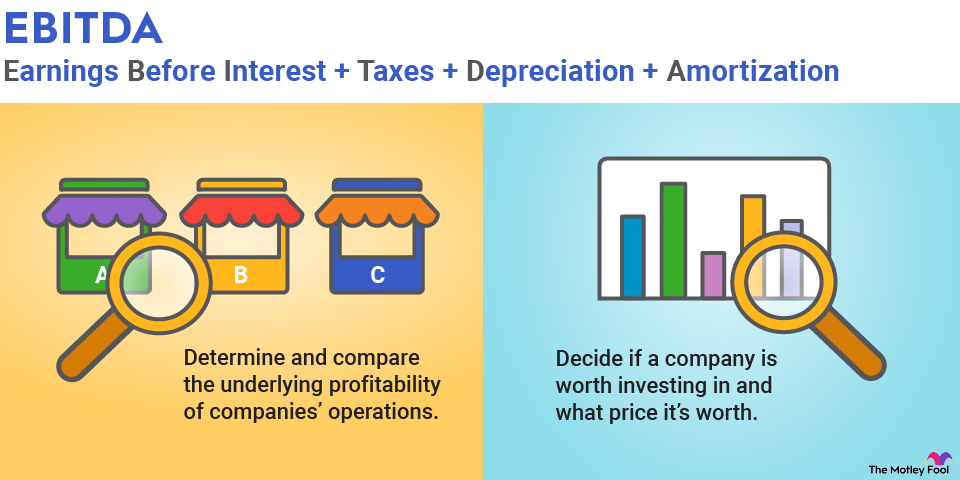
7 Things Worth Knowing About EBITDA = Net Worth
The EBITDA = net worth assumption is a shortcut that obscures more than it reveals. It’s useful in certain contexts—like comparing similar businesses in stable industries—but it’s a trap in others. Below are seven critical realities about this equation, its limitations, and why it fails so often.1. EBITDA Ignores Capital Structure
EBITDA is a pre-debt metric, which means it doesn’t account for how a company finances its operations. A highly leveraged business with massive interest payments may have the same EBITDA as a conservatively financed peer, but the latter’s net worth will almost certainly be higher. Interest expense, after all, directly impacts cash flow and equity value. The EBITDA = net worth myth assumes that debt doesn’t matter—or that all companies have identical capital structures—which is rarely the case. In reality, debt levels can distort EBITDA’s relationship to net worth by hundreds of millions, especially in cyclical industries where leverage fluctuates. Consider two companies in the same sector, both generating $50 million in EBITDA. Company A has $20 million in debt with a 5% interest rate, while Company B is debt-free. Company A’s net income after interest is $40 million, but its net worth is eroded by debt service and potential refinancing risks. Company B’s net worth, meanwhile, reflects its full cash flow potential. The EBITDA figures are identical, but their net worths diverge sharply.2. It Overlooks Working Capital Requirements
EBITDA doesn’t account for the cash tied up in inventory, receivables, or payables—critical components of working capital. A business with high EBITDA but poor working capital management may be sitting on a mountain of unsold inventory or struggling to collect payments, both of which drag on net worth. Conversely, a company with lower EBITDA but efficient working capital could generate more free cash flow, translating to higher equity value. The EBITDA = net worth equation assumes that all EBITDA is immediately convertible into cash, which ignores the reality of operational cash flow cycles. For example, a retail chain with strong EBITDA might be hemorrhaging cash due to slow-moving inventory or generous customer credit terms. Its net worth could be far below its EBITDA multiple suggests. Meanwhile, a subscription-based SaaS company with lower EBITDA but predictable, recurring revenue may have a net worth that exceeds its EBITDA by a wide margin.3. Depreciation and Amortization Aren’t Cash Outflows
EBITDA adds back depreciation and amortization (D&A) to earnings, treating them as non-cash expenses. While this is technically correct—D&A doesn’t involve actual cash payments—it obscures the fact that these expenses represent the wear and tear on physical and intangible assets. A company with high D&A may need to reinvest heavily to maintain its EBITDA, which isn’t reflected in net worth. The EBITDA = net worth assumption treats D&A as free money, but in reality, it signals future capital expenditure needs that could drain equity value. Take a manufacturing plant with high D&A due to aging equipment. Its EBITDA might look robust, but the need to replace machinery could require significant capital infusions, reducing net worth. Meanwhile, a software firm with minimal D&A might have higher net worth because its intangible assets (like IP) don’t require the same level of reinvestment.4. It Fails for Asset-Heavy Businesses
In industries where fixed assets dominate—such as utilities, shipping, or industrial manufacturing—EBITDA can bear little relation to net worth. These businesses require substantial upfront capital to acquire or maintain assets, which aren’t reflected in EBITDA. A shipping company with high EBITDA but a fleet of aging vessels may have net worth dragged down by depreciation and maintenance costs. The EBITDA = net worth equation breaks down entirely when asset turnover and capital intensity are high. Even in tech, where intangible assets often outweigh physical ones, the rule doesn’t hold. A biotech firm with high EBITDA from drug sales may have net worth eroded by R&D costs or failed clinical trials. The equation assumes that all EBITDA contributes equally to net worth, but in reality, some industries require constant reinvestment to sustain earnings.5. Private Equity’s Love Affair with EBITDA Multiples
Private equity firms have popularized the use of EBITDA multiples as a valuation tool, often implying that EBITDA approximates net worth when structuring deals. This leads to acquisitions where buyers pay a premium based on EBITDA alone, without scrutinizing underlying assets or liabilities. The result? Overpaying for businesses where net worth is far lower than EBITDA suggests. The 2008 financial crisis exposed this flaw when many leveraged buyouts collapsed under the weight of debt, revealing that EBITDA alone couldn’t sustain net worth in a downturn."EBITDA is useful, but it’s a means to an end, not an end in itself. If you’re valuing a company based solely on EBITDA, you’re essentially betting that the future will look exactly like the past—and that’s a risky assumption." — Henry Kravis, Co-Founder of Kohlberg Kravis Roberts (KKR)The myth persists because EBITDA multiples are easy to compare across deals. But as the dot-com bubble and the 2008 crash proved, ignoring net worth in favor of EBITDA can lead to catastrophic misallocations of capital.
6. It Misleads in High-Growth Companies
Startups and high-growth firms often operate at a loss for years, reinvesting EBITDA into expansion. In these cases, EBITDA = net worth is laughably inaccurate. A company with negative EBITDA but a scalable business model (like many tech firms in their early stages) may have a net worth that skyrockets once it achieves profitability. Conversely, a mature business with stable EBITDA but no growth potential may see its net worth stagnate or decline. The equation assumes that all EBITDA contributes to equity value immediately, which ignores the time value of money and reinvestment needs. Consider a pre-profit SaaS company burning cash to acquire users. Its EBITDA might be negative, but its net worth could be rising if its customer base and revenue projections justify a high valuation. The EBITDA = net worth rule would dismiss such a company as worthless, when in reality, its future EBITDA potential is what drives its net worth today.7. Regulators and Accountants Reject the Equation
Financial regulators, including the SEC in the U.S. and the Financial Reporting Council (FRC) in the UK, have explicitly warned against using EBITDA as a proxy for net worth or profitability. The SEC’s guidance on non-GAAP measures states that EBITDA should not be presented as a substitute for net income or cash flow from operations. Similarly, the FRC has cautioned that EBITDA can be misleading if not properly contextualized. The EBITDA = net worth assumption violates these principles by implying that a single metric can replace a full financial analysis. Accounting standards bodies, such as the International Financial Reporting Standards (IFRS) and Generally Accepted Accounting Principles (GAAP), treat EBITDA as a non-standard metric precisely because it omits critical financial details. Yet, in practice, many investors and executives still treat it as a shorthand for worth—despite the risks.
How These Facts Connect
The EBITDA = net worth myth thrives because it simplifies a complex reality. EBITDA is a useful tool for comparing operational efficiency or forecasting cash flow, but it’s a poor substitute for net worth because it ignores capital structure, working capital, reinvestment needs, and industry-specific dynamics. The seven points above reveal that the equation holds only in narrow circumstances—typically for mature, asset-light businesses with stable cash flows and minimal debt. Even then, it’s an oversimplification. The real danger is that the myth encourages shortcuts in valuation. Investors who rely on EBITDA multiples without digging deeper risk paying inflated prices for businesses where net worth is far lower. Founders may undervalue their own companies or overestimate their financial health. Creditors might extend loans based on EBITDA projections that don’t account for hidden liabilities. The table below contrasts the key differences between EBITDA and net worth, highlighting why the two are rarely interchangeable.| Factor | EBITDA | Net Worth |
|---|---|---|
| Capital Structure | Ignores debt | Reflects debt impact on equity |
| Working Capital | Excludes inventory, receivables, payables | Includes liquidity and operational cash needs |
| Reinvestment Needs | Adds back D&A (non-cash) | Accounts for future capital expenditures |
| Industry Dynamics | Assumes uniform profitability drivers | Varies by asset intensity and growth stage |
Conclusion
The persistence of the EBITDA = net worth idea is a testament to the allure of simplicity in finance. Yet, as this breakdown shows, the equation is a dangerous oversimplification that can lead to poor decisions—whether in acquisitions, investments, or corporate strategy. EBITDA is a valuable metric, but it must be used in context, alongside net worth, cash flow, and industry-specific factors. Ignoring these nuances can result in overvalued deals, misallocated capital, and financial distress. For investors, the lesson is clear: EBITDA is not net worth, and treating it as such can obscure the true financial health of a business. For founders, it’s a reminder that earnings alone don’t define worth—capital structure, reinvestment needs, and working capital do. And for regulators, it underscores the need for continued scrutiny of non-GAAP measures. The myth of EBITDA = net worth may be convenient, but in finance, convenience is often the enemy of accuracy.Comprehensive FAQs
Q: Why do private equity firms still use EBITDA multiples if they’re misleading?
Private equity relies on EBITDA multiples because they provide a quick, comparable metric for deals. The industry’s focus on leverage and cash flow makes EBITDA a useful shorthand, even though it’s not a perfect measure of net worth. Many firms adjust for these limitations by incorporating debt coverage ratios or other metrics, but the allure of simplicity keeps EBITDA central to valuation. The risk, however, is that overreliance on EBITDA can lead to overleveraged acquisitions—especially in downturns.
Q: Can EBITDA ever approximate net worth?
In very specific cases—such as mature, asset-light businesses with stable cash flows and minimal debt—EBITDA might loosely correlate with net worth. For example, a well-established SaaS company with recurring revenue, low capital expenditures, and conservative debt levels could see its EBITDA and net worth move in similar directions. However, even in these cases, the relationship isn’t exact. The equation holds far less true for capital-intensive industries, high-growth startups, or businesses with significant working capital needs.
Q: How should EBITDA be used in valuation?
EBITDA should be one of many inputs in valuation, not a standalone measure. It’s most useful for comparing operational efficiency across similar businesses or forecasting cash flow. To derive net worth, it must be adjusted for debt, working capital, capital expenditures, and industry-specific factors. Analysts often use EBITDA as a starting point but then apply industry-specific multiples or discount cash flow models to arrive at a more accurate valuation.
Q: What’s a better metric than EBITDA for assessing net worth?
Free cash flow (FCF) is often a better indicator of net worth because it accounts for capital expenditures and working capital changes. FCF = EBITDA – capital expenditures – changes in working capital. Unlike EBITDA, FCF reflects the actual cash available to shareholders or for reinvestment, making it a more reliable proxy for net worth in many cases. Other metrics, such as return on invested capital (ROIC) or economic value added (EVA), also provide deeper insights into a company’s financial health.
Q: How does the EBITDA = net worth myth affect small businesses?
Small businesses often fall prey to this myth when seeking financing or selling their companies. Banks or buyers may overvalue a business based on EBITDA alone, ignoring the founder’s personal guarantees, undervalued assets, or industry-specific risks. For example, a family-owned restaurant with high EBITDA but high food costs and tenant lease obligations may have net worth far below its EBITDA suggests. This can lead to overleveraging or undervalued exits, leaving owners with less equity than they expected.
Q: Are there industries where EBITDA is a decent proxy for net worth?
In industries with low capital intensity, predictable cash flows, and minimal working capital needs—such as some service-based businesses or subscription models—EBITDA can be a rough proxy for net worth. For instance, a professional services firm with high margins and few fixed assets might see its EBITDA and net worth move in tandem. However, even in these cases, debt levels and reinvestment needs can create discrepancies. The relationship is never precise, and other metrics should always be considered.
Q: How can a founder avoid overvaluing their business based on EBITDA?
Founders should seek independent valuation reports that incorporate EBITDA alongside other financial metrics. Engaging a financial advisor or using discounted cash flow (DCF) analysis can provide a more accurate picture of net worth. It’s also crucial to disclose all liabilities—including off-balance-sheet obligations—and to adjust EBITDA for industry-specific factors, such as R&D costs in tech or maintenance costs in manufacturing. Transparency with buyers or lenders about these adjustments can prevent overvaluation.
