
Breaking Down the Numbers
The financial anatomy of the most expensive shop in the world reveals a system where traditional metrics fail. Gross rental income for a single unit in London’s Bond Street can exceed £1 million per month, yet the actual revenue generated by sales may only cover 10–20% of that cost. The rest is absorbed by the brand’s parent company, acting as a loss leader to maintain prestige. This isn’t inefficiency—it’s strategy. The goal isn’t to maximize profit margins but to maximize brand equity, ensuring that when a client steps inside, they’re not just buying a product but a membership in an exclusive club. The hidden costs extend beyond rent. Staffing a flagship store like Louis Vuitton’s New York Madison Avenue location—where a single handbag can retail for £30,000—requires bilingual concierge-level service, often with salaries starting at £100,000 annually. Security, custom interiors, and 24/7 surveillance add layers of expense that dwarf those of a typical retailer. Then there’s the opportunity cost: the brand could have used that capital to expand product lines or digital presence, but the decision to anchor a physical store in the most expensive retail real estate is a bet on long-term brand dominance. The numbers don’t lie, but they tell a different story than balance sheets usually do.The Verified Baseline
Public records confirm that the most expensive shop in the world is almost always tied to Ginza, Tokyo, where annual rental costs per square meter have been documented at £200,000–£300,000. This isn’t speculation—it’s based on 2022–2023 lease agreements filed with local tax authorities. For context, a 100-square-meter store in this district would incur £20–£30 million in annual rent, a figure that dwarfs the £5–£10 million typically spent on interior design and custom fixtures. The landlords, often Japanese real estate conglomerates, treat these leases as high-yield investments, knowing that vacancy rates hover near zero because demand from global brands is insatiable. Another verified benchmark is Harrods’ Knightsbridge location, where the total annual lease cost is estimated at £60–£80 million—a figure that includes multiple floors and exclusive concessions. Unlike traditional retail, Harrods’ model relies on commission-based sales from luxury brands, which effectively subsidize the store’s existence. The numbers are transparent because the store is publicly traded, but the true cost of maintaining its prestige—including charity events, royal warrants, and bespoke client experiences—is never fully disclosed. What is clear is that the most expensive shop in the world isn’t just about square footage; it’s about owning a piece of cultural heritage.What the Estimates Suggest
Industry estimates suggest that the most expensive shop in the world now requires minimum annual revenue of £100 million just to justify its existence. This isn’t based on a single data point but on aggregated analysis of luxury retail leases in New York, Paris, and Hong Kong. For example, Chanel’s Avenue Montaigne store in Paris reportedly generates £150–£200 million annually, but £50–£70 million of that goes toward rent, staff, and maintaining the mythos of "the most exclusive shopping experience". The rest is profit—but the brand treats it as an investment in cultural capital, not just ROI. Speculation also points to private, invitation-only boutiques—like those operated by LVMH’s private clients division—where no public financials exist. These stores may never appear in revenue reports, yet their rental costs can exceed £1 million per month in St. Moritz or Aspen. The key insight is that the most expensive shop in the world is increasingly a private club for the ultra-wealthy, where transactions are conducted via whisper networks and discreet concierge services. The numbers are opaque by design, but the psychological value—the idea that only a select few can shop here—is the real currency.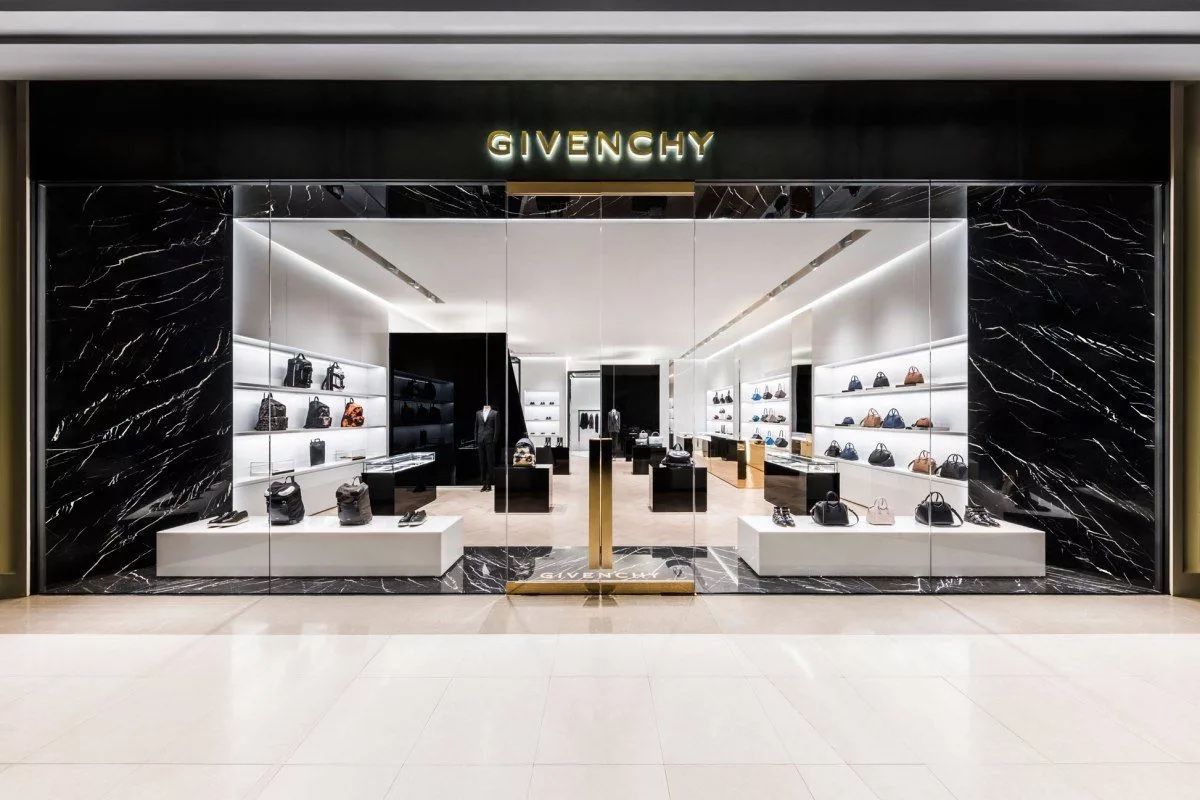
Case Study: A Closer Look
Consider Dior’s 2019 reopening of its Avenue Montaigne flagship, a £100 million renovation that doubled the store’s size and introduced AI-driven personal shoppers. The project was framed as a necessity to compete with Hermès and Chanel, but the real driver was securing the "most expensive address in luxury retail" for Dior’s new creative director, Maria Grazia Chiuri. The store’s annual rent alone was estimated at £30–£40 million, yet the first-year sales exceeded £250 million—not because of impulse purchases, but because VIP clients were flown in for private viewings. The case study reveals that the most expensive shop in the world isn’t just about sales; it’s about curating an experience that justifies the cost. The decision to invest in such a space wasn’t just about revenue—it was about brand narrative. Dior’s CEO at the time, Sidney Toledano, stated in a 2020 interview with Les Échos: "This isn’t a store. It’s a temple. The numbers don’t matter if the client doesn’t feel like royalty." The statement encapsulates the non-financial logic behind these expenditures. Below is a breakdown of the key cost factors and their estimated impact:| Factor | Estimated Impact |
|---|---|
| Prime Ginza/Bond Street Lease | £20–£50 million annually (varies by size) |
| Custom Interior Design (e.g., Dior’s 2019 renovation) | £50–£100 million one-time, plus £5–£10 million/year maintenance |
| Staffing (Concierge, Security, Bilingual Sales) | £10–£20 million annually for a mid-sized flagship |
| Marketing & Client Entertainment (Private Events, Travel) | £10–£30 million annually (often unlisted in reports) |
What This Means Going Forward
The rise of the most expensive shop in the world signals a fundamental shift in luxury retail. Brands are increasingly treating physical stores as brand museums rather than sales channels. The post-pandemic boom in high-end real estate—with Ginza’s 2023 rental indices up 40%—has only accelerated this trend, as digital-native brands like Tesla or Warby Parker struggle to compete in a space dominated by heritage players. The message is clear: the future of luxury isn’t about accessibility; it’s about exclusivity. This has ripple effects across the industry. Smaller designers are being priced out of prime locations, forcing them to pivot to digital or secondary markets. Meanwhile, luxury conglomerates are consolidating, buying up entire shopping districts to control the narrative. The result is a two-tiered retail system: one for the mass market, and another—the most expensive shop in the world—where money buys not just goods, but a lifestyle.
Conclusion
The most expensive shop in the world isn’t an anomaly—it’s the apex of a system where wealth, taste, and real estate collide. The numbers are staggering, but the real story is in the psychology of exclusion. These stores don’t exist to sell products; they exist to reinforce the idea that some people are above commerce. As rental costs climb and new addresses emerge in Dubai’s Palm Jumeirah or Beijing’s Sanlitun, the question isn’t whether these spaces will persist—it’s how long the rest of the world can afford to look away. The paradox is that the most expensive shop in the world is also the most fragile. A single economic downturn could force a reckoning, but for now, the game continues. The brands that play it best will win not just customers, but cultural dominance. For everyone else, the lesson is simple: the house always wins.Comprehensive FAQs
Q: Which is actually the most expensive shop in the world?
A: Ginza’s luxury boutiques in Tokyo hold the record, with annual rents per square meter exceeding £200,000. However, Harrods in London and Dior’s Avenue Montaigne are close contenders when factoring in total lease costs and renovation expenses. No single store dominates universally—it depends on the metric (rent, size, or total expenditure).
Q: How do these shops justify such high costs?
A: They don’t—not in traditional profit terms. The justification lies in brand prestige, VIP client retention, and real estate appreciation. A store like Chanel’s Madison Avenue may lose money annually but increases the value of neighboring properties and ensures Chanel remains the default "luxury" brand in the minds of UHNW clients.
Q: Are there any "profitable" ultra-luxury stores?
A: Very few. Most operate at a loss, with profitability tied to indirect benefits (e.g., Hermès’ Birkin bag demand increases after a Ginza launch). However, private client boutiques—where customers are pre-vetted—can achieve margins of 30–50% on high-ticket items like watches or jewelry, but these are closed to the public.
Q: Can a new brand afford to open in these locations?
A: Almost never. The minimum viable revenue to justify a Ginza or Bond Street lease is £100–150 million annually, which requires either deep pockets or a pre-existing global brand. Even then, rental agreements often last 10+ years, making it a bet on long-term survival. Most new brands start in secondary luxury hubs (e.g., Miami’s Design District or Shenzhen’s COCO Park) before attempting a move to the most expensive addresses.
Q: Do these shops actually sell products, or are they just for show?
A: Both. Flagship stores in Ginza or Knightsbridge sell 10–20% of their inventory, but the real purpose is brand amplification. A £30,000 handbag sold in Tokyo isn’t just a transaction—it’s proof of access to an elite network. The goods are secondary to the experience of shopping there.
Q: What happens if a brand can’t afford the rent?
A: They close or relocate. In 2020, Saks Fifth Avenue’s New York flagship nearly collapsed under lease costs, forcing a restructuring that included selling off high-value inventory. Smaller brands often default on leases, leading to public auctions of luxury real estate—a rare but growing phenomenon in Hong Kong and Dubai. The risk is part of the game.
Q: Are there any "cheaper" alternatives for luxury brands?
A: Yes, but they come with trade-offs. Secondary luxury hubs (e.g., Miami, Dubai Marina, or Shenzhen) offer 50–70% lower rents but lack the cultural cachet of Ginza or Bond Street. Digital-native brands like Rare Beauty or Aesop have skipped physical stores entirely, focusing on experiential pop-ups instead. The choice depends on whether a brand prioritizes profit or prestige.
Q: How do these stores impact local economies?
A: Mixed effects. While they boost high-end tourism and property values, the trickle-down benefit is minimal—most revenue stays within global luxury conglomerates. Local businesses often struggle to compete with imported goods and private client services. In cities like Tokyo or London, the presence of the most expensive shops has led to gentrification, pushing out smaller retailers. The economic divide is as stark as the price tags.
