The Complete Overview of the Median Net Worth of a 50-Year-Old
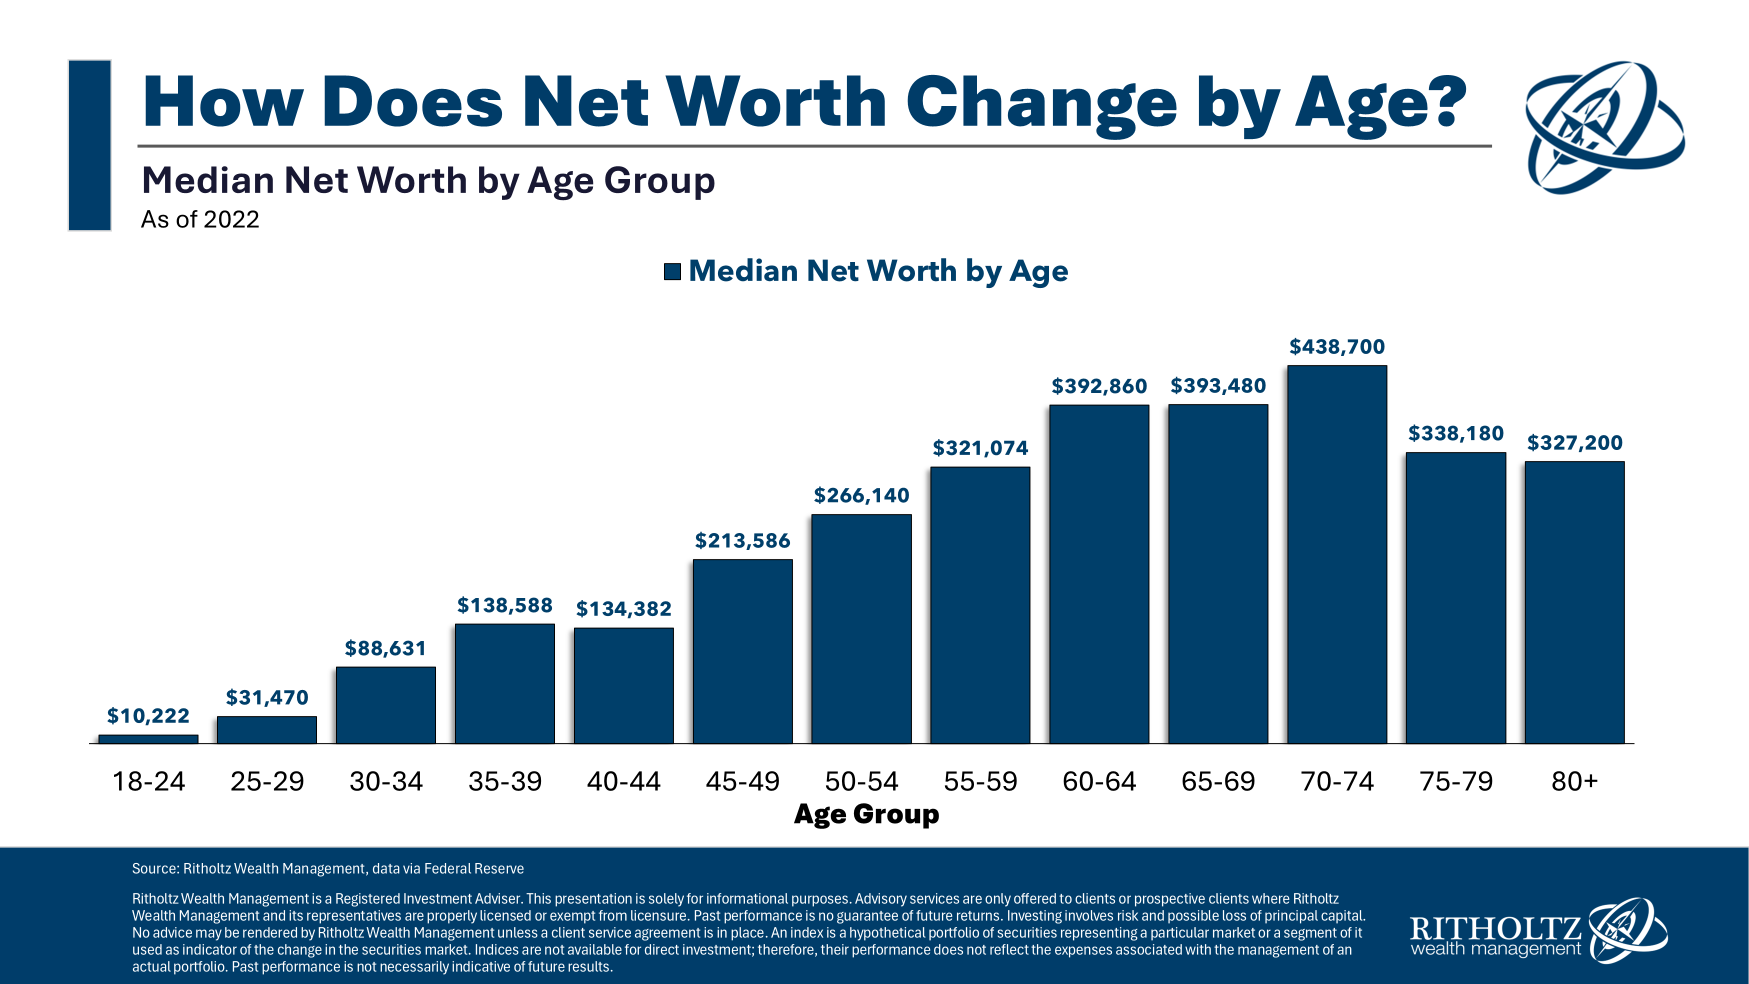
The median net worth of a 50-year-old in the U.S. has long served as a benchmark for economic health, but its meaning has evolved alongside shifting labor markets and housing trends. Federal Reserve data from 2022 placed the figure at roughly $319,000 for households headed by someone aged 50–59—a number that obscures vast regional and racial divides. In San Francisco, where home prices have outpaced wages, the median net worth of a 50-year-old skews toward $1.5 million or more, while in rural Mississippi, it may not exceed $80,000. These disparities aren’t just about income; they reflect the cumulative impact of policy decisions, from mortgage interest deductions to the erosion of defined-benefit pensions. The figure also tells a story about timing. Those who entered the workforce in the late 1990s benefited from a bull market and the dot-com boom, while later generations faced the 2008 crash and stagnant wage growth. A 50-year-old today may have seen their median net worth of a 50-year-old depressed by student loans, delayed retirement savings, or the cost of raising children in an era of rising childcare expenses. The number isn’t static—it’s a moving target influenced by inflation, healthcare costs, and the unpredictable nature of asset appreciation.Historical Background and Evolution
The concept of tracking the median net worth of a 50-year-old emerged alongside broader economic studies in the 1980s, as policymakers sought to measure intergenerational wealth transfer. Before then, discussions centered on median income, which failed to capture the role of home equity, stock portfolios, or inherited wealth. The shift toward net worth metrics revealed a critical insight: for many Americans, homeownership was the primary driver of wealth accumulation. By the 1990s, as real estate boomed, the median net worth of a 50-year-old began to rise sharply, particularly for white households, while Black and Hispanic families lagged due to systemic barriers like redlining and predatory lending. The 2008 financial crisis exposed the fragility of this model. Home values plummeted, and retirement accounts took hits, sending the median net worth of a 50-year-old into a tailspin. Recovery was uneven: by 2016, the figure had rebounded for upper-income earners, but those in the bottom 40% of wealth distribution remained mired in stagnation. Post-pandemic, the picture grew more complex. Remote work expanded opportunities for some to buy homes in lower-cost areas, while others faced job instability or the burden of supporting adult children. The median net worth of a 50-year-old today is less a reflection of personal discipline and more a product of the economic environment they’ve navigated.Core Mechanisms: How It Works
The median net worth of a 50-year-old isn’t determined by a single factor but by the interplay of three key mechanisms: asset accumulation, liability management, and market exposure. Primary assets—homes, retirement accounts, and investments—typically peak in midlife, as mortgages are paid down and salaries reach their zenith. A 50-year-old with a mortgage-free home and a diversified 401(k) will see a higher median net worth than one still carrying debt or reliant on a single asset class. Liabilities, particularly student loans or medical debt, can drag the figure downward, even for high earners. Market exposure plays a secondary but critical role. Those who benefited from the 2010s stock market rally saw their median net worth of a 50-year-old swell, while others missed out due to poor timing or risk aversion. The role of inheritance is often overlooked: studies suggest that 36% of middle-class wealth comes from intergenerational transfers, meaning many 50-year-olds are standing on the financial achievements of their parents. Without this boost, the median net worth of a 50-year-old in similar income brackets can differ by $200,000 or more.Key Benefits and Crucial Impact
Understanding the median net worth of a 50-year-old isn’t just academic—it’s a tool for financial planning. For those nearing retirement, the figure serves as a stress test: can they sustain their lifestyle without depleting savings? For younger workers, it highlights the urgency of addressing gaps—whether through aggressive saving, side income, or debt reduction. The data also forces a reckoning with inequality. When the median net worth of a 50-year-old white household exceeds that of a Black household by $200,000, the conversation shifts from personal failure to systemic design. The impact extends beyond individuals. Cities with high median net worth among 50-year-olds tend to have stronger local economies, as retirees reinvest in communities or support aging services. Conversely, regions where the median net worth of a 50-year-old is depressed often struggle with outmigration and declining tax bases. Policymakers use these figures to justify everything from pension reforms to housing assistance programs, making the statistic a battleground in economic debates."Net worth at 50 isn’t just about money—it’s about agency. If you’ve built a cushion, you control your next chapter. If you haven’t, the system has already decided your options." — Darrick Hamilton, economist and professor at The New School
Major Advantages
- Financial flexibility: A robust median net worth of a 50-year-old allows for career pivots, early retirement, or investments in education for children or grandchildren.
- Debt freedom: Homeownership and cleared mortgages reduce monthly obligations, freeing cash flow for discretionary spending or emergencies.
- Market resilience: Diversified assets (stocks, bonds, real estate) provide buffers against inflation or job loss, a critical advantage in an uncertain economy.
- Legacy planning: Higher net worth enables estate planning, charitable giving, or passing wealth to heirs without liquidity crises.
- Healthcare security: Savings can offset rising medical costs, a growing concern for those in their 50s facing chronic conditions or long-term care needs.

Comparative Analysis
| Demographic | Median Net Worth (Estimated Range) |
|---|---|
| White households (50–59) | $350,000–$400,000 |
| Black households (50–59) | $150,000–$200,000 |
| Households with advanced degrees | $500,000–$750,000 |
Future Trends and Innovations
The median net worth of a 50-year-old is poised for disruption. Rising home prices in urban centers may push more professionals toward suburban or exurban purchases, altering traditional wealth-building paths. Meanwhile, the gig economy’s growth could reduce traditional retirement savings for some, while others leverage side income to boost their median net worth of a 50-year-old. Automation and AI may also reshape career trajectories, with midlife workers needing to upskill to remain competitive—a challenge for those without financial cushions. Demographic shifts will further complicate the picture. As the population ages, the median net worth of a 50-year-old may rise simply because there are fewer younger workers dragging down averages. However, if wage stagnation persists or healthcare costs spiral, the figure could stagnate or decline for lower-income groups. Innovations like automated wealth management tools or community land trusts may offer new pathways to accumulation, but their adoption will depend on accessibility and trust.
Conclusion
The median net worth of a 50-year-old is more than a number—it’s a reflection of economic opportunity, policy choices, and personal resilience. For some, it’s a milestone earned through discipline and luck; for others, it’s a reminder of barriers that persist despite decades of effort. The data underscores why conversations about wealth must move beyond individual behavior to address structural inequities. Without intervention, the gaps will widen, leaving future generations to grapple with the same disparities. Yet the figure also offers hope. Those who’ve navigated market crashes, career shifts, and family obligations to build meaningful wealth prove that midlife can be a time of financial empowerment. The key lies in adaptability: recognizing that the median net worth of a 50-year-old isn’t a destination but a starting point for the next chapter—whether that’s retirement, entrepreneurship, or simply the freedom to live on one’s own terms.Comprehensive FAQs
Q: Why does the median net worth of a 50-year-old vary so much by race?
The gap stems from historical inequities like redlining, wealth stripping through predatory lending, and lower homeownership rates among Black and Hispanic families. Even when controlling for income, white households benefit from inherited wealth and generational asset accumulation.
Q: Can I increase my median net worth of a 50-year-old if I’m behind?
Yes, but it requires aggressive strategies: paying down high-interest debt, maximizing retirement contributions, and exploring side income. For some, downsizing a home or relocating to a lower-cost area can free up capital. However, the later you start, the harder it is to close the gap.
Q: Does the median net worth of a 50-year-old include business assets?
It depends on the survey. Federal Reserve data typically excludes business equity for nonfarm sole proprietorships, but other studies (like the Survey of Consumer Finances) may include it. This omission can understate wealth for self-employed individuals.
Q: How does divorce affect the median net worth of a 50-year-old?
Divorce can halve net worth for many, especially if assets are split unevenly or retirement accounts are drained for legal fees. Women, in particular, often face long-term financial setbacks due to lower post-divorce incomes and caregiving responsibilities.
Q: Is the median net worth of a 50-year-old a good predictor of retirement readiness?
Partially. While it provides a baseline, retirement readiness also depends on debt levels, healthcare costs, and lifestyle expectations. Someone with a high median net worth but high expenses may still face challenges, while another with modest savings but low costs could retire comfortably.
