Common Myths About the Median Net Worth Age
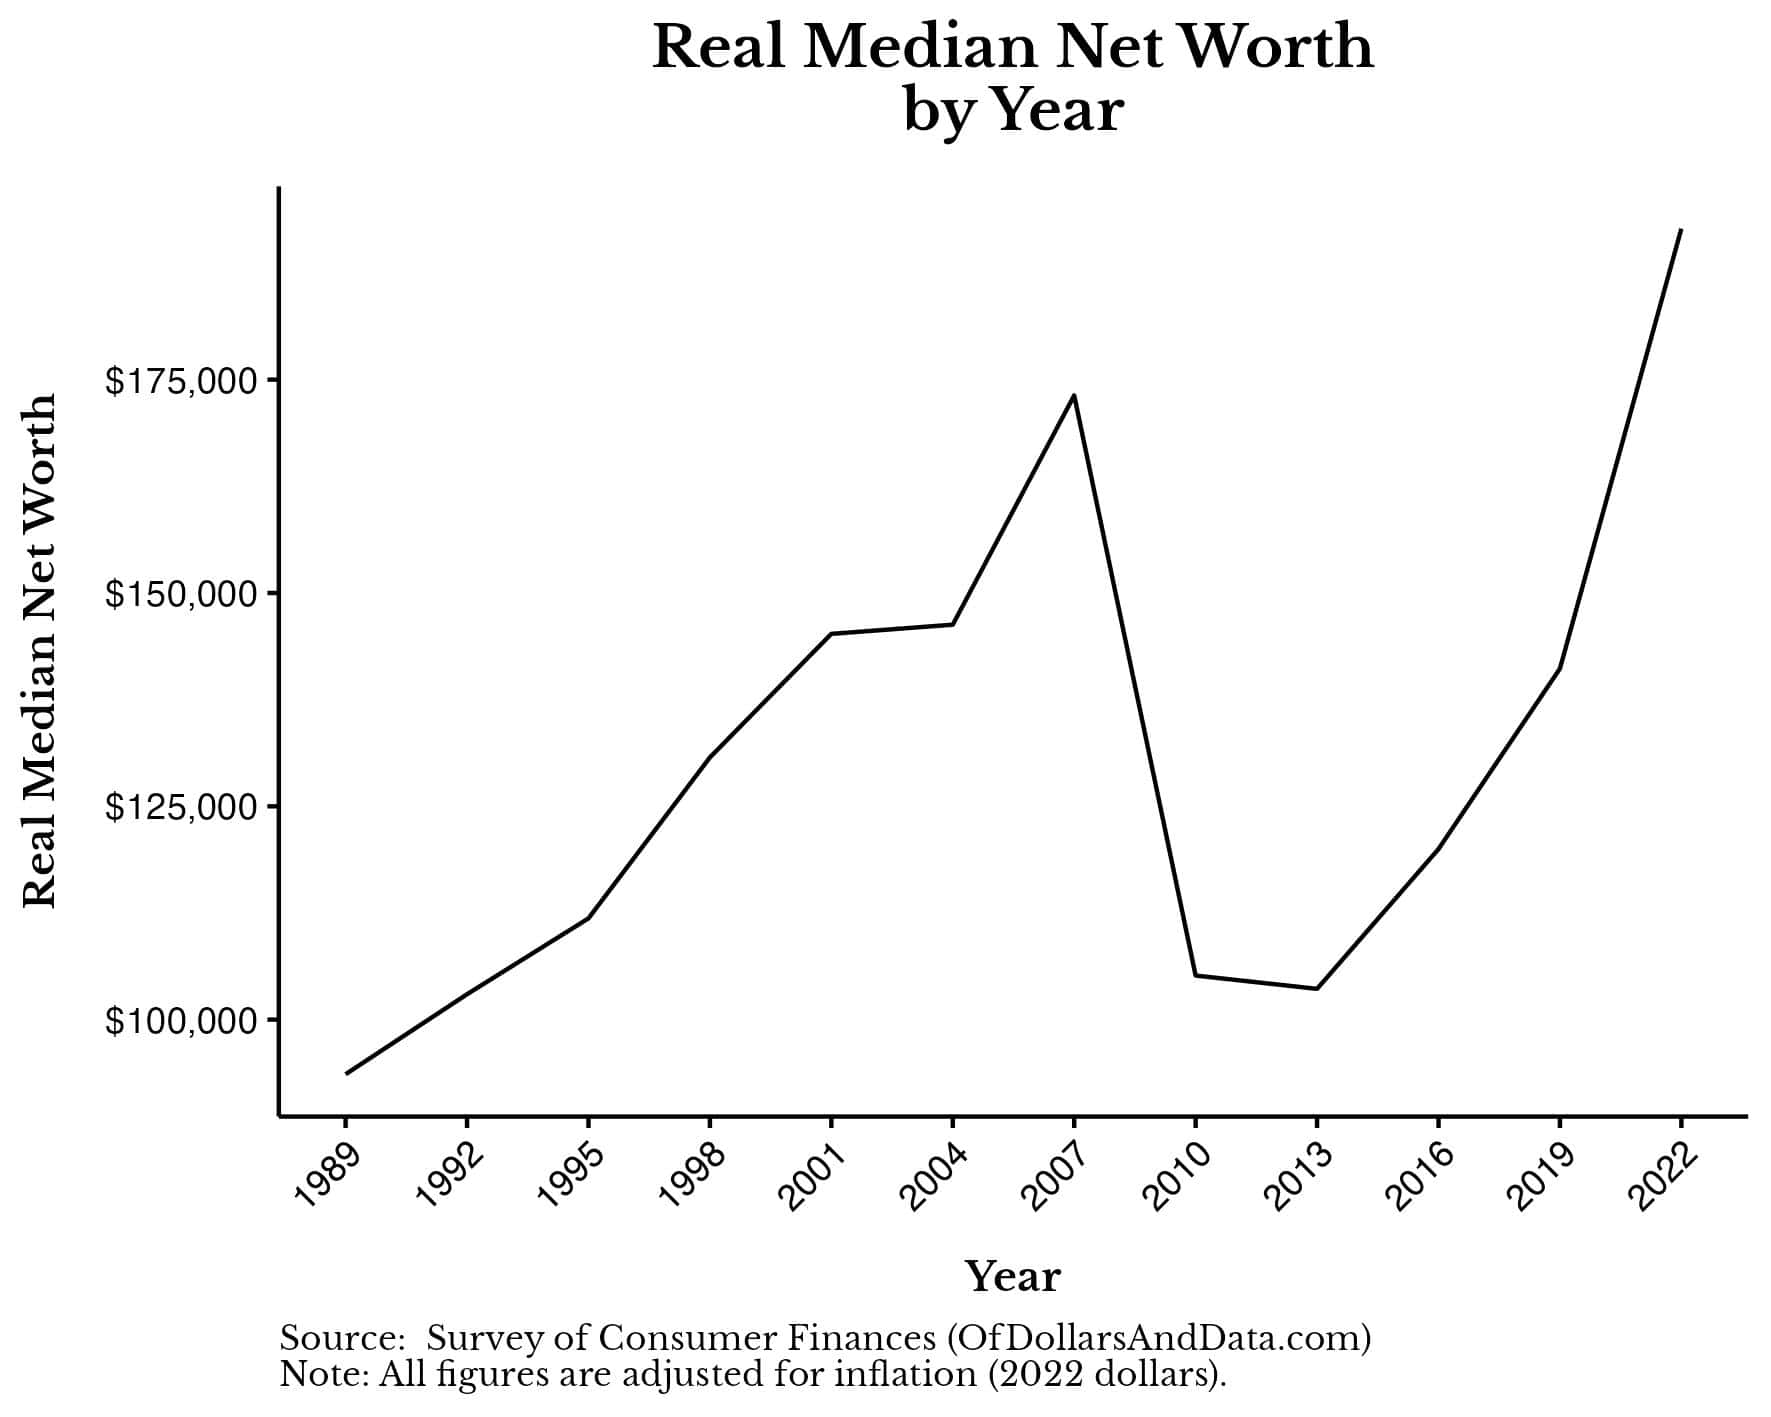
The median net worth age is often misunderstood as a personal failure indicator. Many assume that if they haven’t hit a certain wealth threshold by a specific age, they’re doomed to financial struggle. This myth ignores the fact that wealth accumulation is influenced by systemic factors—like access to capital, education quality, or geographic opportunity—not just individual effort. For example, someone in a high-cost city may appear "behind" simply because housing prices have outpaced salaries, while someone in a lower-cost area might seem ahead despite similar income levels. The median net worth age doesn’t account for these disparities, yet it’s frequently used to shame or motivate people as if it were a personal KPI. Another persistent myth is that the median net worth age is a static number. In reality, it shifts with economic conditions. During periods of inflation or market volatility, the age at which half the population reaches a certain net worth can jump by several years. The Federal Reserve’s periodic surveys show that the median net worth age isn’t just a reflection of personal discipline but also of broader economic trends. Someone who retired in 2007 with a six-figure net worth might have seen that figure halved by 2010 due to the financial crisis—yet their "median net worth age" would still be cited as if it were a fixed milestone.Myth 1: The median net worth age is the same for everyone
The assumption that the median net worth age applies uniformly across demographics is one of the most dangerous oversimplifications. Data from the Federal Reserve’s Survey of Consumer Finances reveals stark differences by race, education level, and marital status. For instance, white households typically reach median net worth levels decades earlier than Black or Hispanic households due to historical wealth gaps, discriminatory lending practices, and differences in homeownership rates. Even within the same racial group, education plays a critical role: someone with a graduate degree will likely hit median net worth benchmarks years before a peer with only a high school diploma, regardless of starting income. The median net worth age also varies by geography. In San Francisco or New York, the age at which half the population reaches a certain wealth threshold is often pushed back by skyrocketing housing costs, while in smaller cities or rural areas, the same milestone might be achieved years earlier. This isn’t just about salary—it’s about the cost of living. Someone earning $100,000 in Austin might accumulate wealth faster than someone earning the same in Boston because their dollar stretches further. Yet most discussions about the median net worth age treat it as a one-size-fits-all metric, erasing these critical differences.Myth 2: Hitting the median net worth age means you’re financially secure
There’s a dangerous conflation between median net worth and financial security. The median net worth age tells you nothing about liquidity, debt levels, or emergency savings. Someone might hit a median net worth benchmark at 40 but still be drowning in student loans or credit card debt, leaving them vulnerable to a single financial shock. Conversely, someone below the median could have a diversified portfolio, no high-interest debt, and a solid emergency fund—putting them in a far stronger position than a peer who’s technically "ahead" on paper. The median net worth age also ignores the role of windfalls and inheritance. A sudden bonus, a trust fund, or an unexpected inheritance can catapult someone above the median overnight, while others may struggle for decades without such breaks. Financial security isn’t just about crossing an arbitrary net worth threshold; it’s about stability, flexibility, and resilience. Yet the median net worth age is often framed as a binary achievement, when in reality, it’s a snapshot that tells you very little about someone’s true financial health.Myth 3: The median net worth age is proof of a "lazy generation"
Generational comparisons are a favorite pastime of financial pundits, but they rarely hold up under scrutiny. Younger generations are often accused of failing to meet median net worth benchmarks because they’re "too lazy" or "not saving enough." Yet this ignores the fact that student debt, stagnant wages, and housing unaffordability have made wealth accumulation far harder for Millennials and Gen Z than for previous generations. The median net worth age for Baby Boomers was lower not because they were more disciplined, but because they benefited from lower education costs, cheaper housing, and stronger labor market protections. Even within generations, experiences vary wildly. Someone who entered the workforce in 2000 saw their 401(k) values plummet during the dot-com crash and the Great Recession, while someone who started in 2010 missed those downturns entirely. The median net worth age isn’t a moral judgment—it’s a product of economic conditions. Blaming individuals for systemic failures is not only unfair but also distracts from the policies that could actually improve financial outcomes for future generations.
What Holds Up to Scrutiny
At its core, the median net worth age is a useful—but limited—tool for understanding wealth distribution. It provides a rough sense of where the average person stands financially at different life stages, but its value diminishes when treated as a universal standard. The most reliable data comes from longitudinal studies, such as those conducted by the Federal Reserve or the Pew Research Center, which track net worth trends over decades. These studies confirm that wealth accumulation is nonlinear, with sharp increases during homeownership and mid-career salary peaks, followed by plateaus or declines in retirement due to healthcare costs and reduced income. What the evidence consistently shows is that the median net worth age is heavily influenced by two factors: asset ownership and debt burden. Homeownership remains the single largest driver of net worth in the U.S., accounting for roughly 35% of the typical household’s wealth. Those who own homes early tend to hit median net worth benchmarks faster, while renters often lag—even if they save aggressively. Similarly, high levels of student debt or medical debt can delay wealth accumulation for years, pushing the median net worth age higher for affected groups."Wealth is not just about income—it’s about access. The median net worth age isn’t a measure of personal failure; it’s a reflection of who had the opportunity to build wealth in the first place." — Darrick Hamilton, economist and professor at The New School
| Common Belief | What the Evidence Says |
|---|---|
| You should hit the median net worth age by 40 or you’re behind. | For most Americans, the median net worth age is closer to 50–55, with significant variation by race, geography, and education. |
| Wealth accumulation is steady and predictable. | Net worth growth is erratic, with sharp spikes during home purchases and dips during economic downturns or unexpected expenses. |
| If you’re above the median, you’re financially secure. | Median net worth doesn’t account for debt levels, liquidity, or exposure to market risk—someone above the median could still be one emergency away from financial ruin. |
Why the Confusion Persists
The median net worth age remains a polarizing metric because it serves two conflicting purposes: it’s both a simplification and a distraction. On one hand, it offers a shorthand for discussing wealth inequality, making complex economic data digestible for a broad audience. On the other, it’s often weaponized—by financial advisors pushing certain products, by politicians blaming individuals for systemic issues, or by media outlets sensationalizing generational decline. The result is a metric that’s easy to cite but nearly impossible to interpret correctly without context. Part of the problem lies in how net worth itself is measured. Unlike income, which is a flow of money, net worth is a snapshot of assets minus liabilities at a single point in time. This makes it highly sensitive to market fluctuations, life events, and reporting biases. For example, someone who refinanced their mortgage might see their net worth drop temporarily, even if their financial situation improved. Yet because the median net worth age is often discussed in broad strokes, these nuances are lost in translation.
Conclusion
The median net worth age is neither a failure metric nor a guarantee of success—it’s a statistical artifact with real-world implications. Its value lies not in its precision but in what it reveals about broader economic trends: the racial wealth gap, the cost of education, the housing crisis, and the fragility of retirement savings. For individuals, the takeaway isn’t whether they’ve hit an arbitrary benchmark but whether their financial strategy aligns with their goals, risk tolerance, and life stage. What’s clear is that wealth accumulation is not a solo endeavor. It’s shaped by policy, luck, and the communities we’re born into. The median net worth age doesn’t tell us who’s doing it right—it tells us who’s had the right opportunities. The real work isn’t chasing a number but advocating for systems that give everyone a fair shot at building wealth.Comprehensive FAQs
Q: What is the median net worth age in the U.S.?
A: According to Federal Reserve data, the median net worth age for U.S. households is estimated to be around 50–55, with significant variation by demographic. For example, white households typically reach median net worth levels by their late 40s, while Black and Hispanic households may not hit the same benchmark until their late 50s or early 60s due to historical wealth disparities.
Q: Does the median net worth age differ by state?
A: Yes. States with high housing costs—like California, New York, and Massachusetts—often see the median net worth age pushed back by 5–10 years compared to lower-cost states like Iowa or Mississippi. For instance, someone in San Francisco may not reach the national median net worth until their late 50s, while someone in Des Moines might hit it in their early 40s.
Q: Can the median net worth age be misleading for young professionals?
A: Absolutely. Young professionals in high-debt fields (like medicine or law) may appear "behind" because their student loans drag down their net worth, even if their income and savings rates are strong. Conversely, someone who inherited property or started a business early might seem ahead despite irregular cash flow. The median net worth age doesn’t distinguish between these scenarios.
Q: How does divorce or separation affect the median net worth age?
A: Divorce can reset the median net worth age for individuals, especially if assets are split unevenly or alimony payments create new financial burdens. Studies show that women, in particular, often see their net worth drop by 30–50% post-divorce, pushing them further from median benchmarks. This effect is rarely reflected in aggregate data, which treats households as static units.
Q: Is the median net worth age rising or falling?
A: It depends on the economic cycle. During periods of inflation or market downturns (like 2008 or 2020), the median net worth age tends to rise as asset values decline. However, post-pandemic data suggests a slight compression—younger generations are accumulating wealth faster due to remote work savings and stock market gains, though this masks underlying inequality. Long-term trends show the median net worth age has been creeping upward for decades.
