The Short Answers
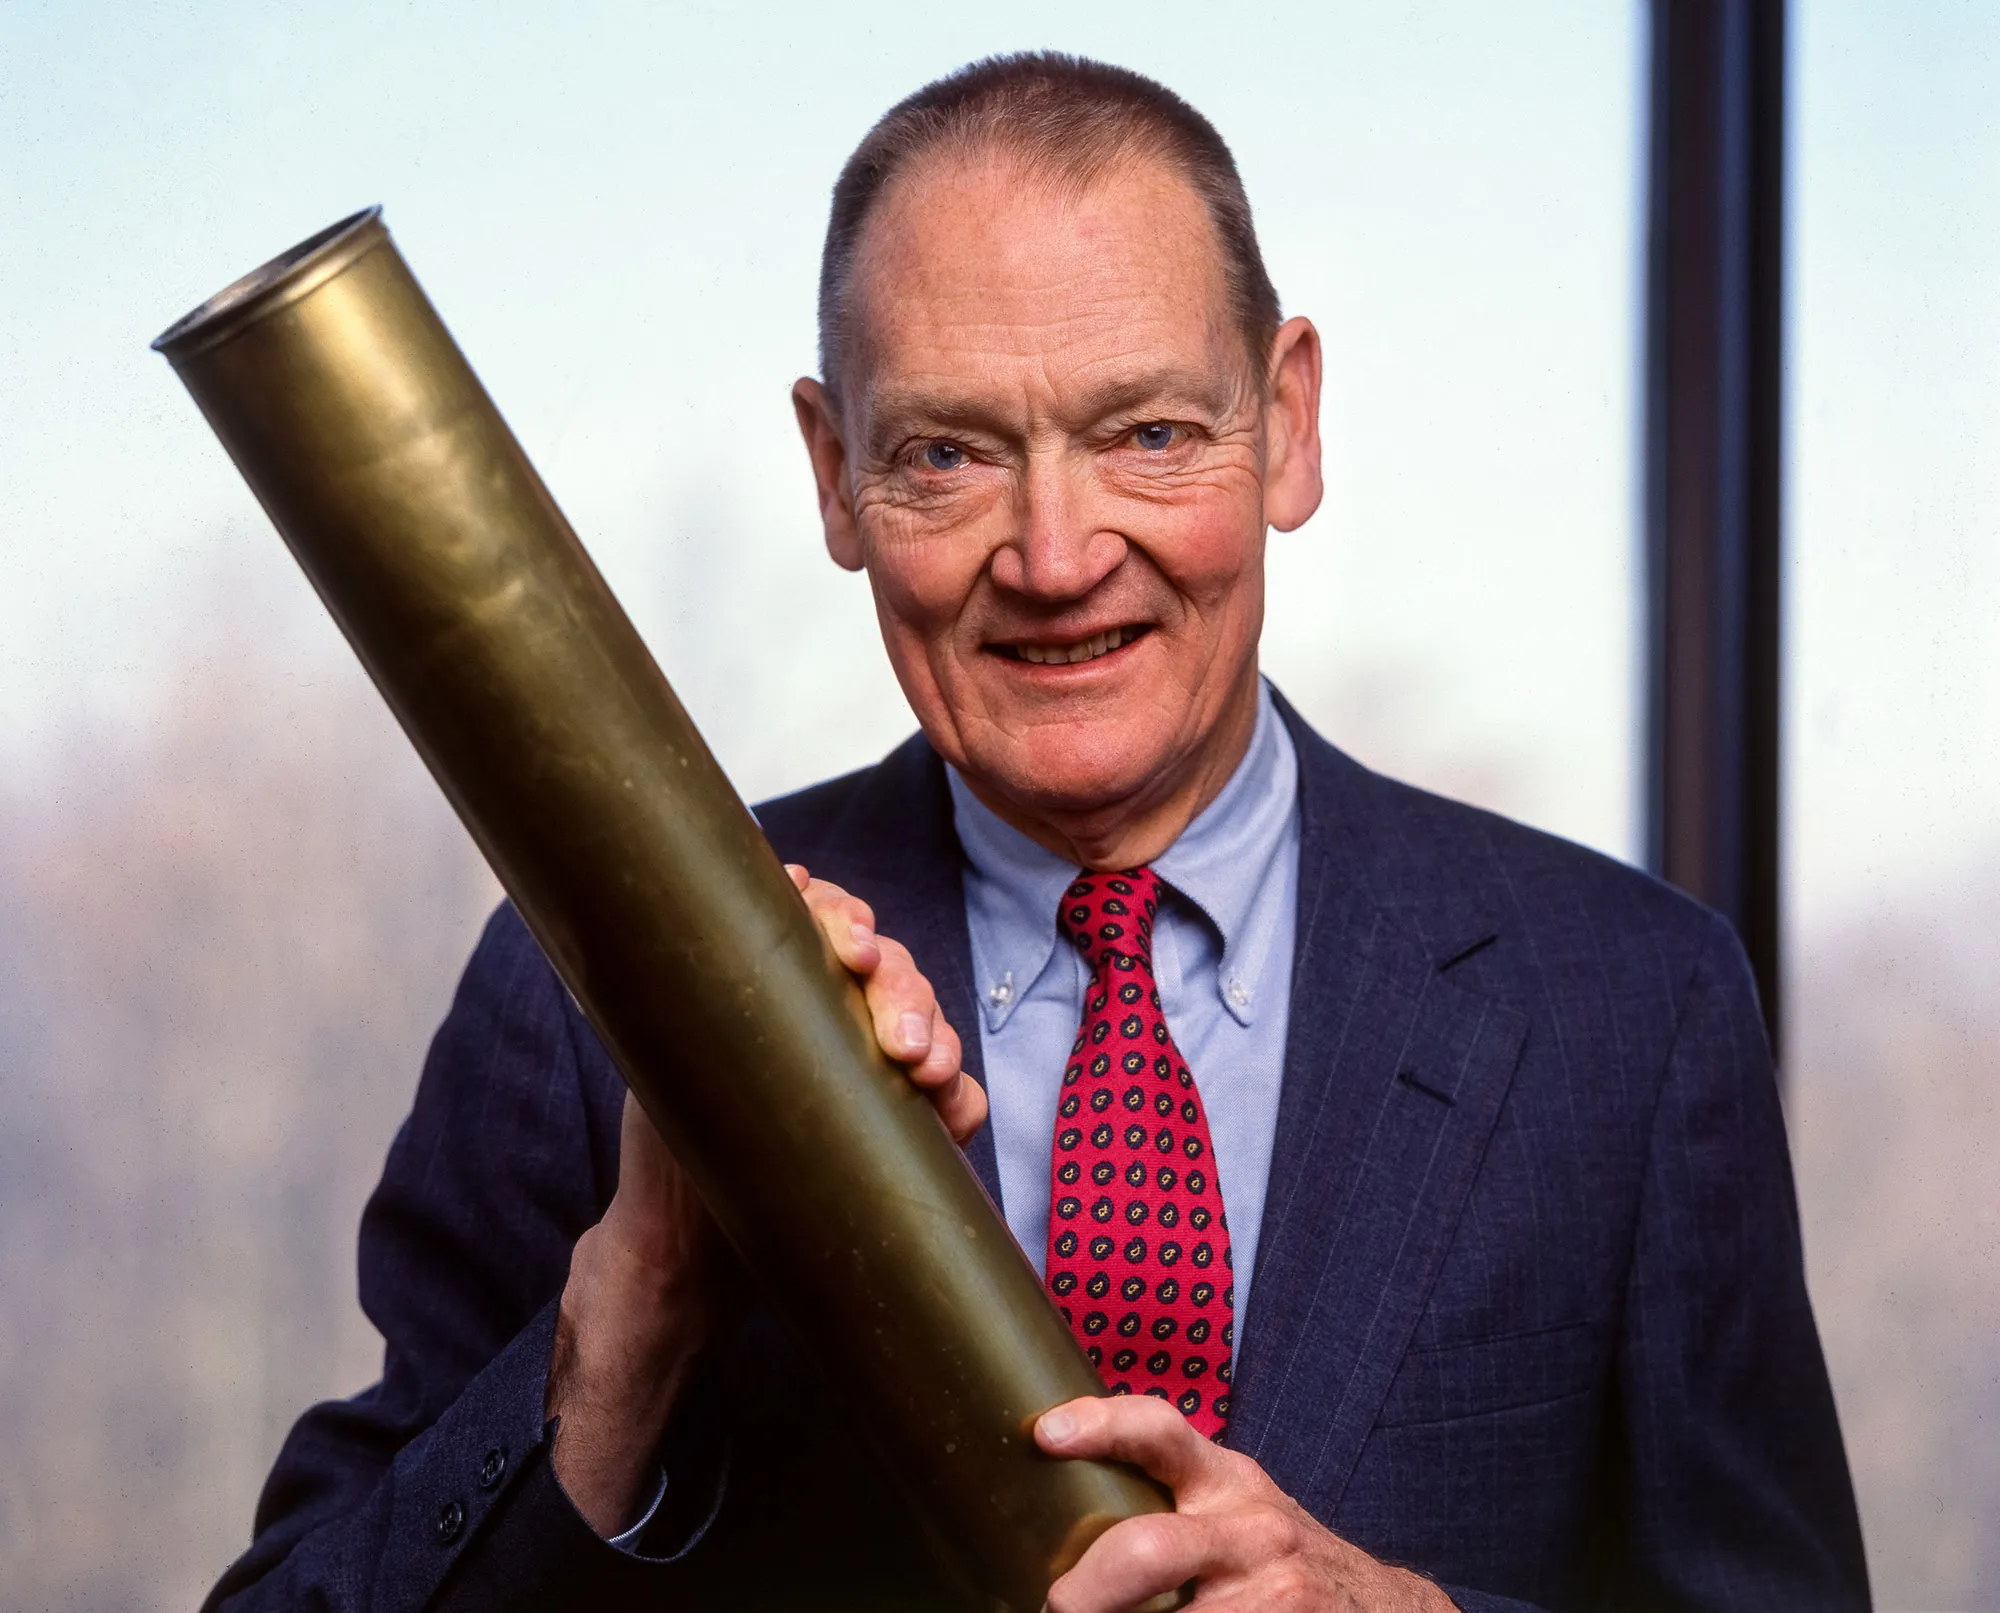
- John Bogle founded Vanguard in 1975 and pioneered the first index mutual fund in 1976, revolutionizing retail investing.
- His philosophy centered on low-cost, passive investing, arguing that most actively managed funds underperformed after fees.
- Bogle’s customer-owned structure at Vanguard—where funds are owned by investors, not shareholders—remains a model for ethical finance.
- He served as Vanguard’s CEO for 30 years, stepping down in 1996 but remaining a vocal advocate for long-term investing.
- His books, including The Little Book of Common Sense Investing, remain bestsellers, distilling his principles for everyday investors.
- Bogle passed away in January 2019 at age 89, leaving behind a legacy that reshaped global markets.
Deep Dive: The Full Picture
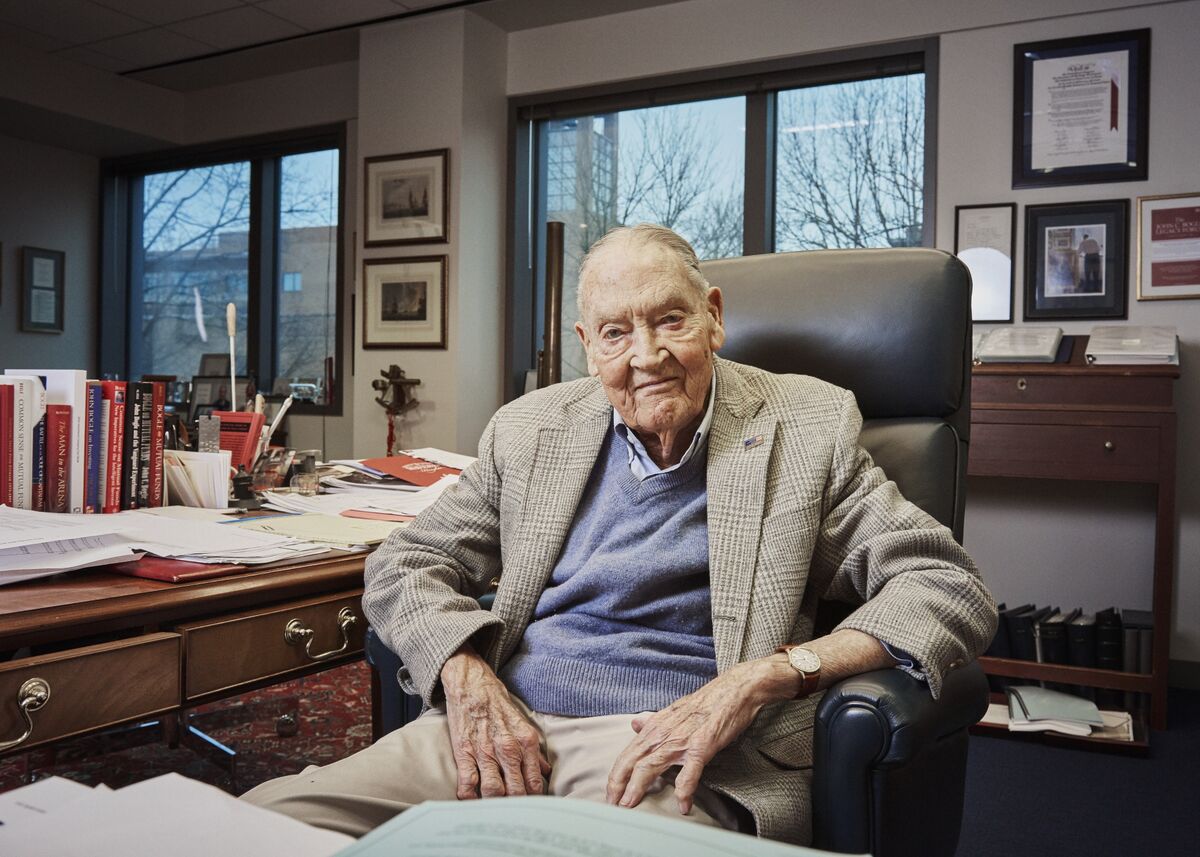
John Bogle’s story begins in a world where investing was a game for the wealthy. Born in 1929 to a working-class family in Montclair, New Jersey, he was the son of a stockbroker who lost everything in the 1929 crash—a lesson that would define his career. After earning a finance degree from Princeton and an MBA from Harvard, he joined Wellington Management in 1951, where he spent two decades climbing the ranks. But by the 1970s, his frustration with the industry’s fee structures and underperformance led him to a radical idea: why not let the market index itself? His 1976 launch of the First Index Investment Trust (later the Vanguard 500 Index Fund) was met with skepticism. Critics called it a gimmick. History proved them wrong. The mechanics of Bogle’s innovation were deceptively simple. Instead of trying to beat the market through stock-picking or market timing—both of which required high fees—his funds tracked the S&P 500. Over time, this approach delivered consistent returns with minimal cost. By 1996, when he stepped down as Vanguard’s CEO, the company managed $100 billion in assets. Today, that figure exceeds $8 trillion. His insistence on who is John Bogle being the champion of the little guy wasn’t just marketing; it was the core of his business model. Vanguard’s structure—where funds are owned by their investors, not external shareholders—eliminated the conflict of interest that plagued traditional asset managers.The Context You Need
To grasp Bogle’s impact, you must understand the financial landscape he inherited. The 1970s were a turning point: the fixed-commission system of the 1930s-60s was collapsing under pressure from regulators and investors. Bogle saw an opportunity. But his real breakthrough wasn’t just the index fund—it was the realization that who is John Bogle could also redefine corporate governance. Traditional mutual funds were owned by their sponsors (like banks or brokerages), which meant profits flowed upward, not to investors. Bogle flipped the script: Vanguard’s funds would be owned by the investors themselves, with no external shareholders to siphon off profits. This "customer-owner" model wasn’t just innovative; it was revolutionary. The timing was critical. The 1980s and 90s saw the rise of the 401(k) and individual retirement accounts, creating a new class of retail investors. Bogle’s low-cost funds were perfectly positioned to serve them. While Wall Street pushed complex, high-fee products, Vanguard offered transparency and simplicity. His 1999 book, Common Sense on Mutual Funds, became a manifesto for investors tired of being fleeced. Even as the dot-com bubble burst and the 2008 financial crisis tested his theories, Bogle’s message remained unchanged: stay the course, keep costs low, and ignore the noise.The Mechanics
Bogle’s genius lay in his ability to distill complex financial concepts into actionable principles. His "Four Pillars of Investing" framework—time, a policy, a plan, and patience—became the bedrock of his philosophy. Time, he argued, was the most powerful variable: compounding rewards long-term holders. A policy meant sticking to a diversified portfolio, while a plan involved setting clear goals. Patience, above all, was the antidote to emotional decision-making. These weren’t just abstract ideas; they were battle-tested strategies that Vanguard’s funds embodied. The numbers tell the story. The Vanguard 500 Index Fund, launched in 1976 with $11 million in assets, grew to manage over $1 trillion by 2023. Its average annual return, net of fees, has been around 10%—outperforming roughly 80% of actively managed funds over the same period. Bogle’s insistence on who is John Bogle being the voice of reason in an industry obsessed with short-term gains was vindicated by data. Yet his skepticism of Wall Street’s excesses never wavered. In his final years, he warned of the dangers of financialization, rising inequality, and the erosion of fiduciary duty—a critique that resonated long after his death.Details That Change the Picture
Bogle’s legacy isn’t just about the funds he created; it’s about the cultural shift he catalyzed. Before him, investing was seen as a high-stakes game requiring expertise. After him, it became accessible to anyone with a paycheck. His advocacy for index funds wasn’t just economic—it was political. By lowering barriers to entry, he helped shift wealth from institutions to individuals, altering the balance of power in markets. This democratization had ripple effects: higher retirement savings rates, reduced reliance on Wall Street intermediaries, and a broader understanding of financial literacy. Yet Bogle’s influence extended beyond the numbers. His personal life reflected his principles. Despite Vanguard’s success, he lived modestly, donating his CEO salary to charity and refusing perks. His 2018 memoir, Enough: True Measures of Money, Business, and Life, was as much a manifesto on ethical living as it was a business memoir. He argued that true wealth wasn’t measured in portfolios but in the lives we build. This duality—being both a financial innovator and a moral compass—made him a rare figure in an industry often criticized for its amoral pursuit of profit."The stock market is a device for transferring money from the impatient to the patient." —John Bogle, 2007The table below highlights key milestones in Bogle’s life and their lasting impact:
| Year | Event |
|---|---|
| 1974 | Launches the first index mutual fund at Wellington Management. |
| 1975 | Founds Vanguard Group, introducing the customer-owner model. |
| 1976 | Vanguard 500 Index Fund debuts with $11 million in assets. |
| 1999 | Publishes Common Sense on Mutual Funds, a bestseller that popularizes passive investing. |
Conclusion
John Bogle’s story is one of defiance in the face of convention. Who is John Bogle, at its core, is the question of how one man’s stubborn belief in simplicity could upend an entire industry. His life’s work wasn’t just about building a company; it was about proving that finance could serve people, not just profits. In an era of algorithmic trading, high-frequency speculation, and skyrocketing inequality, his principles feel more relevant than ever. The rise of robo-advisors, ETFs, and passive investing strategies are all descendants of his ideas. Yet Bogle’s greatest contribution may be intangible: he made investing feel less like gambling and more like a disciplined, long-term endeavor. For millions, his name is synonymous with trust—a rare commodity in finance. As markets evolve, his lessons remain timeless. The question of who is John Bogle isn’t just historical; it’s a mirror held up to the industry today. Are we building a system that empowers investors, or one that exploits them? His answer was clear: the former is possible, and it starts with a single, radical idea.Comprehensive FAQs
Q: How did John Bogle’s index fund work?
Bogle’s index funds replicated the performance of a market index (like the S&P 500) by holding all its constituent stocks in proportion. Unlike actively managed funds, which relied on stock-pickers charging high fees, his approach minimized costs and delivered consistent returns over time. The key was diversification and low expenses, not market-beating predictions.
Q: Why was Vanguard’s customer-owner model revolutionary?
Traditional mutual funds were owned by their sponsors (e.g., banks or brokerages), creating a conflict of interest: profits often flowed to the fund’s owners, not investors. Bogle’s model flipped this by making investors the owners of the funds. This eliminated the incentive to overcharge and ensured that any profits from fund operations were returned to investors in the form of lower fees.
Q: Did John Bogle ever regret his approach to investing?
Bogle remained steadfast in his beliefs, but he did acknowledge that his early warnings about financial industry excesses—such as the rise of high-frequency trading and complex financial products—went largely unheeded. In his later years, he expressed frustration with the growth of "financialization," where markets became detached from the real economy, but he never wavered from his core philosophy of low-cost, long-term investing.
Q: How did Bogle’s ideas influence modern investing?
His impact is everywhere: the explosion of ETFs, the popularity of passive investment strategies, and the shift toward fee transparency are all direct descendants of his work. Even fintech disruptors like robo-advisors and micro-investing apps owe a debt to his emphasis on accessibility and simplicity. His books remain required reading for financial advisors, and his principles are now taught in business schools worldwide.
Q: Was John Bogle a billionaire?
While Bogle’s net worth was substantial—estimated in the hundreds of millions—he never sought personal wealth. He donated his CEO salary to charity, lived modestly, and ensured that Vanguard’s profits benefited investors, not executives. His fortune was tied to the company’s success, but his personal lifestyle reflected his belief that money should serve a purpose beyond accumulation.
Q: What is Bogle’s most famous quote?
One of his most enduring lines is: "Don’t look for the needle in the haystack. Just buy the haystack!" This encapsulates his argument that most investors are better off owning the entire market (the haystack) rather than trying to find the few stocks (the needle) that will outperform. It’s a metaphor for the power of diversification and the futility of stock-picking.
