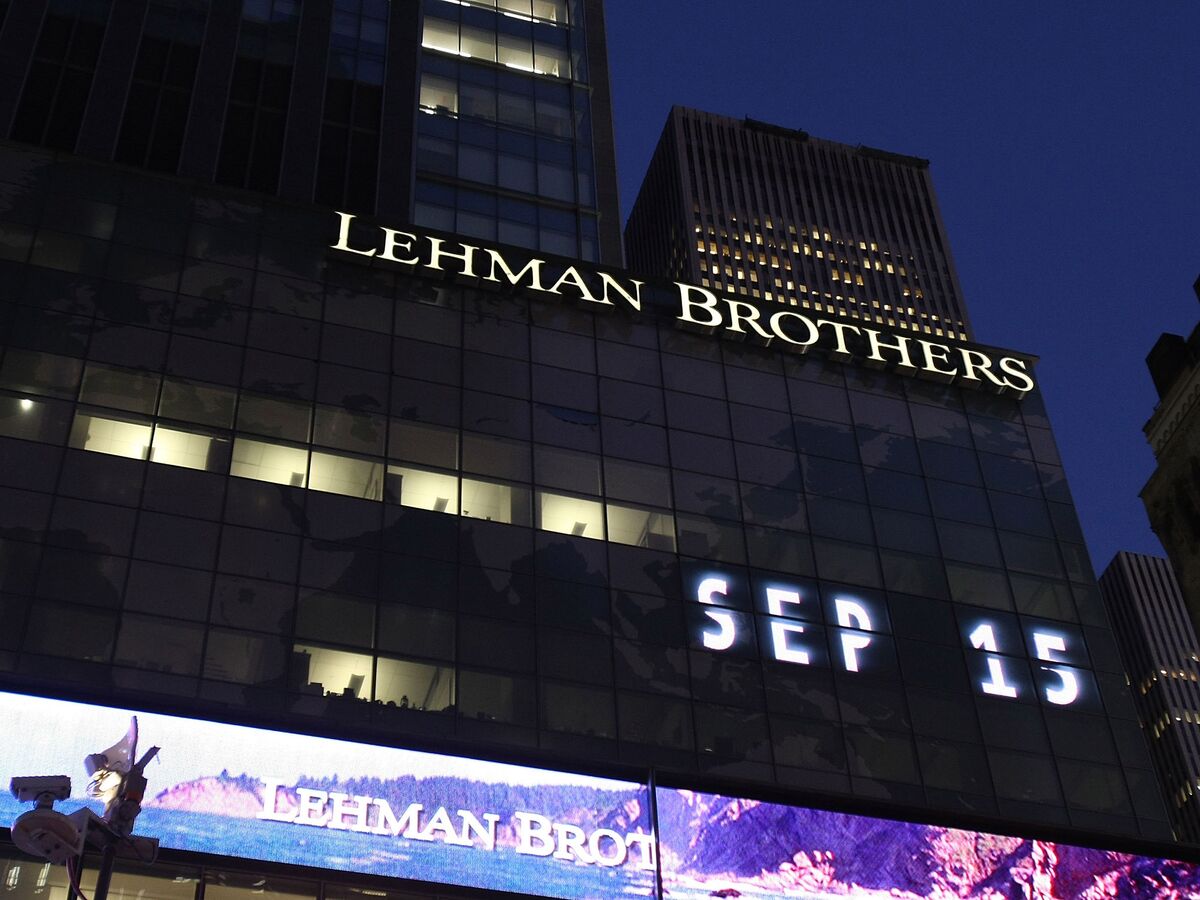
Lehman Brothers wasn’t just another bank when it filed for bankruptcy on September 15, 2008. It was the fourth-largest investment bank in the U.S., a 158-year-old institution that had weathered wars, recessions, and regulatory shifts—until the subprime mortgage crisis exposed its overleveraged balance sheet. The
lehman brothers bank net worth at its peak was a subject of intense scrutiny, not just for its size but for how its collapse triggered a global financial panic. What followed wasn’t just the loss of a company; it was the unraveling of a model that had long been considered untouchable.
The bank’s downfall wasn’t inevitable, but it was the result of a perfect storm: aggressive risk-taking in mortgage-backed securities, a reliance on short-term funding, and a regulatory environment that allowed investment banks to operate with minimal capital buffers. When the housing bubble burst, Lehman’s
lehman brothers bank net worth—once estimated at over $600 billion in assets—evaporated overnight. The question that lingers a decade later isn’t just
how it happened, but
why the true scale of its exposure was so misunderstood until it was too late.
Common Myths About Lehman Brothers Bank Net Worth

The collapse of Lehman Brothers is often reduced to a single narrative: reckless greed, a lone wolf on Wall Street, or a failure of capitalism. These oversimplifications obscure the bank’s actual financial structure and the systemic risks it embodied. One persistent myth is that Lehman was a monolithic entity, its
lehman brothers bank net worth a singular, easily measurable figure. In reality, the bank operated as a complex web of subsidiaries, off-balance-sheet entities, and repurchase agreements (repos) that made its true exposure nearly impossible to quantify until the moment of failure. Another misconception is that its downfall was purely the result of bad bets on subprime mortgages. While those bets played a role, the deeper issue was Lehman’s lehman brothers bank net worth being propped up by a fragile funding model that relied on constant access to short-term credit—a model that vanished when confidence disappeared.
Equally misleading is the idea that Lehman’s collapse was an isolated event. The bank’s
lehman brothers bank net worth was intertwined with the broader financial system through derivatives, credit default swaps, and counterparty relationships. When Lehman failed, it didn’t just take its own assets with it; it dragged down institutions that had bet against its survival. The confusion stems from treating Lehman as a static entity rather than a dynamic, leveraged machine—one where the distinction between assets and liabilities was blurred by accounting tricks and regulatory loopholes.
Myth 1: Lehman’s Net Worth Was Clearly Defined Before Its Collapse
The assumption that Lehman’s
lehman brothers bank net worth was a transparent, audited figure is a myth perpetuated by hindsight. In the years leading up to 2008, the bank’s financial health was assessed through a combination of quarterly filings, analyst estimates, and proprietary risk models—none of which captured the full extent of its exposure. Lehman used Repo 105 transactions, a controversial accounting practice where it temporarily moved assets off its balance sheet to meet regulatory capital requirements. These transactions inflated its apparent liquidity while masking the true scale of its leverage. By the time regulators and investors realized the extent of the deception, it was too late to unwind the positions without triggering a market meltdown.
Even Lehman’s own internal projections were flawed. The bank’s
lehman brothers bank net worth was frequently cited in the hundreds of billions, but these figures were often based on mark-to-market valuations that assumed liquid markets would remain open. When the subprime crisis hit, those markets froze, and Lehman’s assets became nearly worthless overnight. The bank’s reported net worth—what little was left after accounting for liabilities—was a moving target, dependent on daily trading conditions and counterparty risk. The reality was that Lehman’s lehman brothers bank net worth was less a fixed number and more a function of confidence in its ability to roll over debt.
Myth 2: The Bank’s Downfall Was Solely Due to Subprime Mortgage Bets
While Lehman’s involvement in mortgage-backed securities (MBS) and collateralized debt obligations (CDOs) was well-documented, framing its collapse as a result of bad mortgage bets oversimplifies the catastrophe. The bank’s
lehman brothers bank net worth was eroded by a combination of factors: excessive leverage, overreliance on short-term funding, and a failure to hedge against systemic risk. Lehman’s leverage ratio—assets to equity—was among the highest in the industry, meaning even a small drop in asset values could wipe out its capital. When the housing market turned, the bank’s MBS holdings lost value, but the real damage came from the inability to refinance its $600 billion in short-term debt.
Lehman’s
lehman brothers bank net worth was also propped up by a network of special purpose entities (SPEs) that held toxic assets off its balance sheet. These entities were supposed to isolate risk, but they did little to protect Lehman when the music stopped. The bank’s failure wasn’t just about bad loans; it was about a business model that assumed perpetual growth in asset values and liquidity. When that growth stalled, the entire structure collapsed under its own weight.
Myth 3: The Government Could Have Easily Saved Lehman Brothers
The idea that Lehman’s collapse was preventable with a simple bailout ignores the political and financial realities of 2008. By the time Treasury Secretary Henry Paulson and Federal Reserve officials realized the severity of the crisis, Lehman’s lehman brothers bank net worth had become a black hole—its liabilities were so opaque and interconnected that a rescue would have required an unprecedented infusion of capital. The Fed had already bailed out Bear Stearns in March, and the political will to repeat that effort for Lehman was nonexistent. Additionally, Lehman’s legal structure made it difficult to unwind its operations without triggering a chain reaction in global markets.
Even if the government had intervened, the question remains: would it have worked? Lehman’s lehman brothers bank net worth was so leveraged that any rescue would have required recapitalizing the entire entity, not just patching its balance sheet. The bank’s culture of risk-taking and regulatory arbitrage had created a beast that was too large to fail safely. The decision to let Lehman collapse was a calculated risk—one that, in hindsight, accelerated the financial crisis but also forced a reckoning with the dangers of unchecked leverage.
What Holds Up to Scrutiny
At its core, Lehman Brothers’ lehman brothers bank net worth was a function of its balance sheet size, leverage, and the value of its assets—none of which were static. The bank’s reported net worth in 2007 was around $25 billion, but this figure was misleading. Its total assets, including those held in off-balance-sheet entities, were estimated at over $600 billion. The problem wasn’t the size of its assets; it was the thin layer of equity supporting them. Lehman’s leverage ratio was approximately 30-to-1, meaning for every dollar of shareholder equity, it had $30 in assets or liabilities. When asset values declined, the equity buffer vanished instantly.
What makes Lehman’s lehman brothers bank net worth a case study in financial engineering is how it used derivatives and structured products to amplify returns—and risks. The bank’s exposure to mortgage-backed securities was vast, but its true vulnerability lay in its inability to hedge against a systemic downturn. Unlike commercial banks, which were subject to capital requirements, Lehman operated under a lighter regulatory touch, allowing it to take on more risk with less equity.
> "Lehman was a classic example of a firm that grew too fast, took too much risk, and assumed markets would always be kind to it. When they weren’t, the house of cards came down."
> —
Andrew Lo, MIT Professor of Finance
| Common Belief | What the Evidence Says |
|--------------------------------------------|-------------------------------------------------------------------------------------------|
| Lehman’s net worth was over $100 billion. | Its reported net worth was ~$25 billion in 2007, but total assets exceeded $600 billion. |
| Its failure was just about bad loans. | Leverage and funding gaps were the primary killers, not just mortgage bets. |
| The government could have saved it easily.| Lehman’s legal structure and size made a rescue impractical without systemic risks. |
| Only retail investors lost money. | Counterparties, pension funds, and global markets suffered massive losses from its collapse. |
Why the Confusion Persists
The myths surrounding Lehman’s lehman brothers bank net worth endure because the bank’s collapse was both a symptom and a catalyst of a broader crisis. The financial instruments it traded—CDOs, synthetic CDOs, and credit default swaps—were so complex that even regulators struggled to understand their risks. Lehman’s use of Repo 105 transactions and other accounting maneuvers obscured its true financial health until it was too late. The bank’s downfall also exposed the fragility of the "shadow banking" system, where non-bank financial institutions operated with minimal oversight.
Another reason for the confusion is the retroactive rewriting of financial history. In the years since 2008, Lehman’s lehman brothers bank net worth has been dissected in lawsuits, congressional hearings, and academic papers, each offering a slightly different explanation for its failure. Some blame greedy executives, others point to regulatory failures, and still others argue that the bank was a victim of its own success. The truth is likely a combination of all three—but the lack of a single, definitive answer keeps the debate alive.
Conclusion
Lehman Brothers’ lehman brothers bank net worth was never as simple as a balance sheet number. It was a reflection of an era when financial innovation outpaced regulation, when risk was treated as an asset, and when the assumption of perpetual growth blinded institutions to their own vulnerabilities. The bank’s collapse wasn’t just the end of Lehman; it was a warning about the dangers of leverage, opacity, and systemic interconnectedness. A decade later, the lessons of 2008 remain relevant, particularly as new financial technologies and regulatory challenges emerge.
What Lehman’s story teaches us is that lehman brothers bank net worth—or any bank’s net worth—is only as strong as the confidence in its ability to survive the next crisis. When that confidence evaporates, the consequences are not just financial but existential. The question now is whether history will repeat itself, or whether the lessons of Lehman’s fall have finally been learned.
Comprehensive FAQs
#### Q: How much was Lehman Brothers’ net worth before it collapsed?
A: Lehman’s lehman brothers bank net worth was reported at approximately $25 billion in 2007, but its total assets—including those held in off-balance-sheet entities—were estimated at over $600 billion. The discrepancy highlights how leverage and accounting practices distorted its true financial health.
#### Q: Did Lehman Brothers have more assets than liabilities?
A: No. By most measures, Lehman’s liabilities exceeded its assets in the months leading up to its collapse. The bank’s lehman brothers bank net worth was eroded by declining asset values and its inability to refinance short-term debt, leaving it insolvent in all but name.
#### Q: What role did leverage play in Lehman’s downfall?
A: Lehman’s leverage ratio was among the highest in the industry, with assets exceeding equity by a factor of 30-to-1. This meant even a small decline in asset values could wipe out its capital. When the housing market collapsed, the bank’s thin equity buffer disappeared overnight.
#### Q: Were there any red flags before Lehman’s collapse?
A: Yes. Analysts and regulators had noted concerns about Lehman’s lehman brothers bank net worth, including its heavy reliance on short-term funding, opaque accounting practices like Repo 105 transactions, and exposure to mortgage-backed securities. However, these warnings were often dismissed as temporary blips.
#### Q: How did Lehman’s failure affect global markets?
A: Lehman’s collapse triggered a credit freeze, as banks and financial institutions around the world reassessed counterparty risk. The bank’s lehman brothers bank net worth was so interconnected that its failure accelerated the global financial crisis, leading to liquidity shortages and a deepening recession.
#### Q: Could Lehman have been saved with a bailout?
A: A bailout was considered, but Lehman’s legal structure and the size of its liabilities made a rescue extremely difficult. The Fed’s decision to let it fail was controversial but aimed at preventing a broader contagion. In hindsight, the move may have accelerated the crisis, but it also forced a reckoning with the dangers of unchecked leverage.
#### Q: What lessons were learned from Lehman’s collapse?
A: The crisis led to stricter regulations like the Dodd-Frank Act, which imposed higher capital requirements and stress tests on banks. However, critics argue that many of the risks Lehman exploited—such as off-balance-sheet entities and complex derivatives—remain in financial markets today.