Where It All Began
The origins trace back to a garage in the late 1990s, where two engineers debated whether the internet was a fad or the foundation of the next economy. Their bet paid off when they launched a search engine that didn’t just answer queries but predicted what users would ask before they did. Early investors, including a little-known venture firm, saw potential in a model that monetized attention rather than physical goods. By 2004, the company had gone public at a valuation that made it the largest company in net worth in its sector overnight. The first decade was defined by brute-force expansion: acquisitions of competitors, aggressive hiring of talent from rivals, and a relentless push into adjacent markets. Each move was framed as "synergistic," but the real strategy was simple—eliminate alternatives. When critics questioned its dominance, executives pointed to consumer choice. The data told a different story: 90% of searches in key markets routed through its platform. The largest company in net worth wasn’t just winning; it was rewriting the definition of competition.The Early Signs
The warning signs appeared in regulatory filings. While competitors reported flat growth, this company’s revenue streams diversified at an alarming rate. A side project in digital advertising became its most profitable division. Then came the cloud computing gambit—a bet that businesses would outsource their infrastructure rather than build it. Skeptics called it a distraction. By 2012, it was generating more revenue than the entire company had in 2008. The final clue was its balance sheet. Most tech firms listed assets like servers and patents. This one held something far more valuable: user data. The more people used its services, the more valuable the data became—and the harder it was for rivals to compete. The largest company in net worth wasn’t just growing; it was creating a moat no one could scale.The Turning Point
The inflection occurred in 2017, when a single product launch—an AI-powered assistant—demonstrated the company’s ability to turn data into predictive power. Analysts had spent years debating whether its core business was mature. The assistant proved otherwise. Within months, it became the default tool for millions, embedding the company deeper into daily life. The market reacted instantly. Share prices surged, and the phrase "largest company in net worth" entered earnings calls as a given. What had been a slow burn became a sprint. The company’s valuation crossed a psychological threshold: $1 trillion. Not because it had invented something new, but because it had become indispensable."Dominance isn’t about being the best—it’s about being the only option people don’t realize they’re choosing." — Former competitor executive, 2018
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2004–2008 | IPO at historic valuation; acquisition spree begins (e.g., YouTube); transition from search to "digital lifestyle" platform. |
| 2009–2013 | Mobile strategy accelerates; Android integration locks in global user base; cloud division (later a standalone giant) launches. |
| 2014–2017 | AI research division expands; advertising revenue hits $100B+; first trillion-dollar valuation milestone. |
| 2018–Present | Regulatory scrutiny intensifies; diversification into hardware (e.g., smart devices); largest company in net worth status solidified. |
Lessons From the Journey
- Data as currency: The company’s real asset wasn’t code or hardware—it was the feedback loop of user behavior. Every interaction became raw material for future products.
- Regulatory arbitrage: Early moves into tax-friendly jurisdictions set a precedent for how multinational tech firms structure operations to minimize liabilities.
- Ecosystem lock-in: By making its services the default in operating systems, browsers, and devices, it ensured competitors couldn’t dislodge it without rebuilding entire platforms.
- Cultural dominance: The company didn’t just sell products; it shaped digital identity. To younger generations, its tools were as fundamental as electricity.
Where Things Stand Today
The largest company in net worth now operates in a paradox: it’s both a monolith and a shadow. Its market cap fluctuates with macroeconomic trends, but its underlying assets—data, algorithms, and network effects—depreciate at a far slower rate than traditional businesses. Governments have tried to reign it in with antitrust actions, but each case has only reinforced its position as the default infrastructure of the internet. The real question isn’t whether it will remain the largest company in net worth—it’s what happens when its influence extends beyond economics into governance. Already, its lobbying power rivals that of nation-states. Critics argue it’s too big to fail; supporters say it’s too big to regulate. Either way, the experiment continues.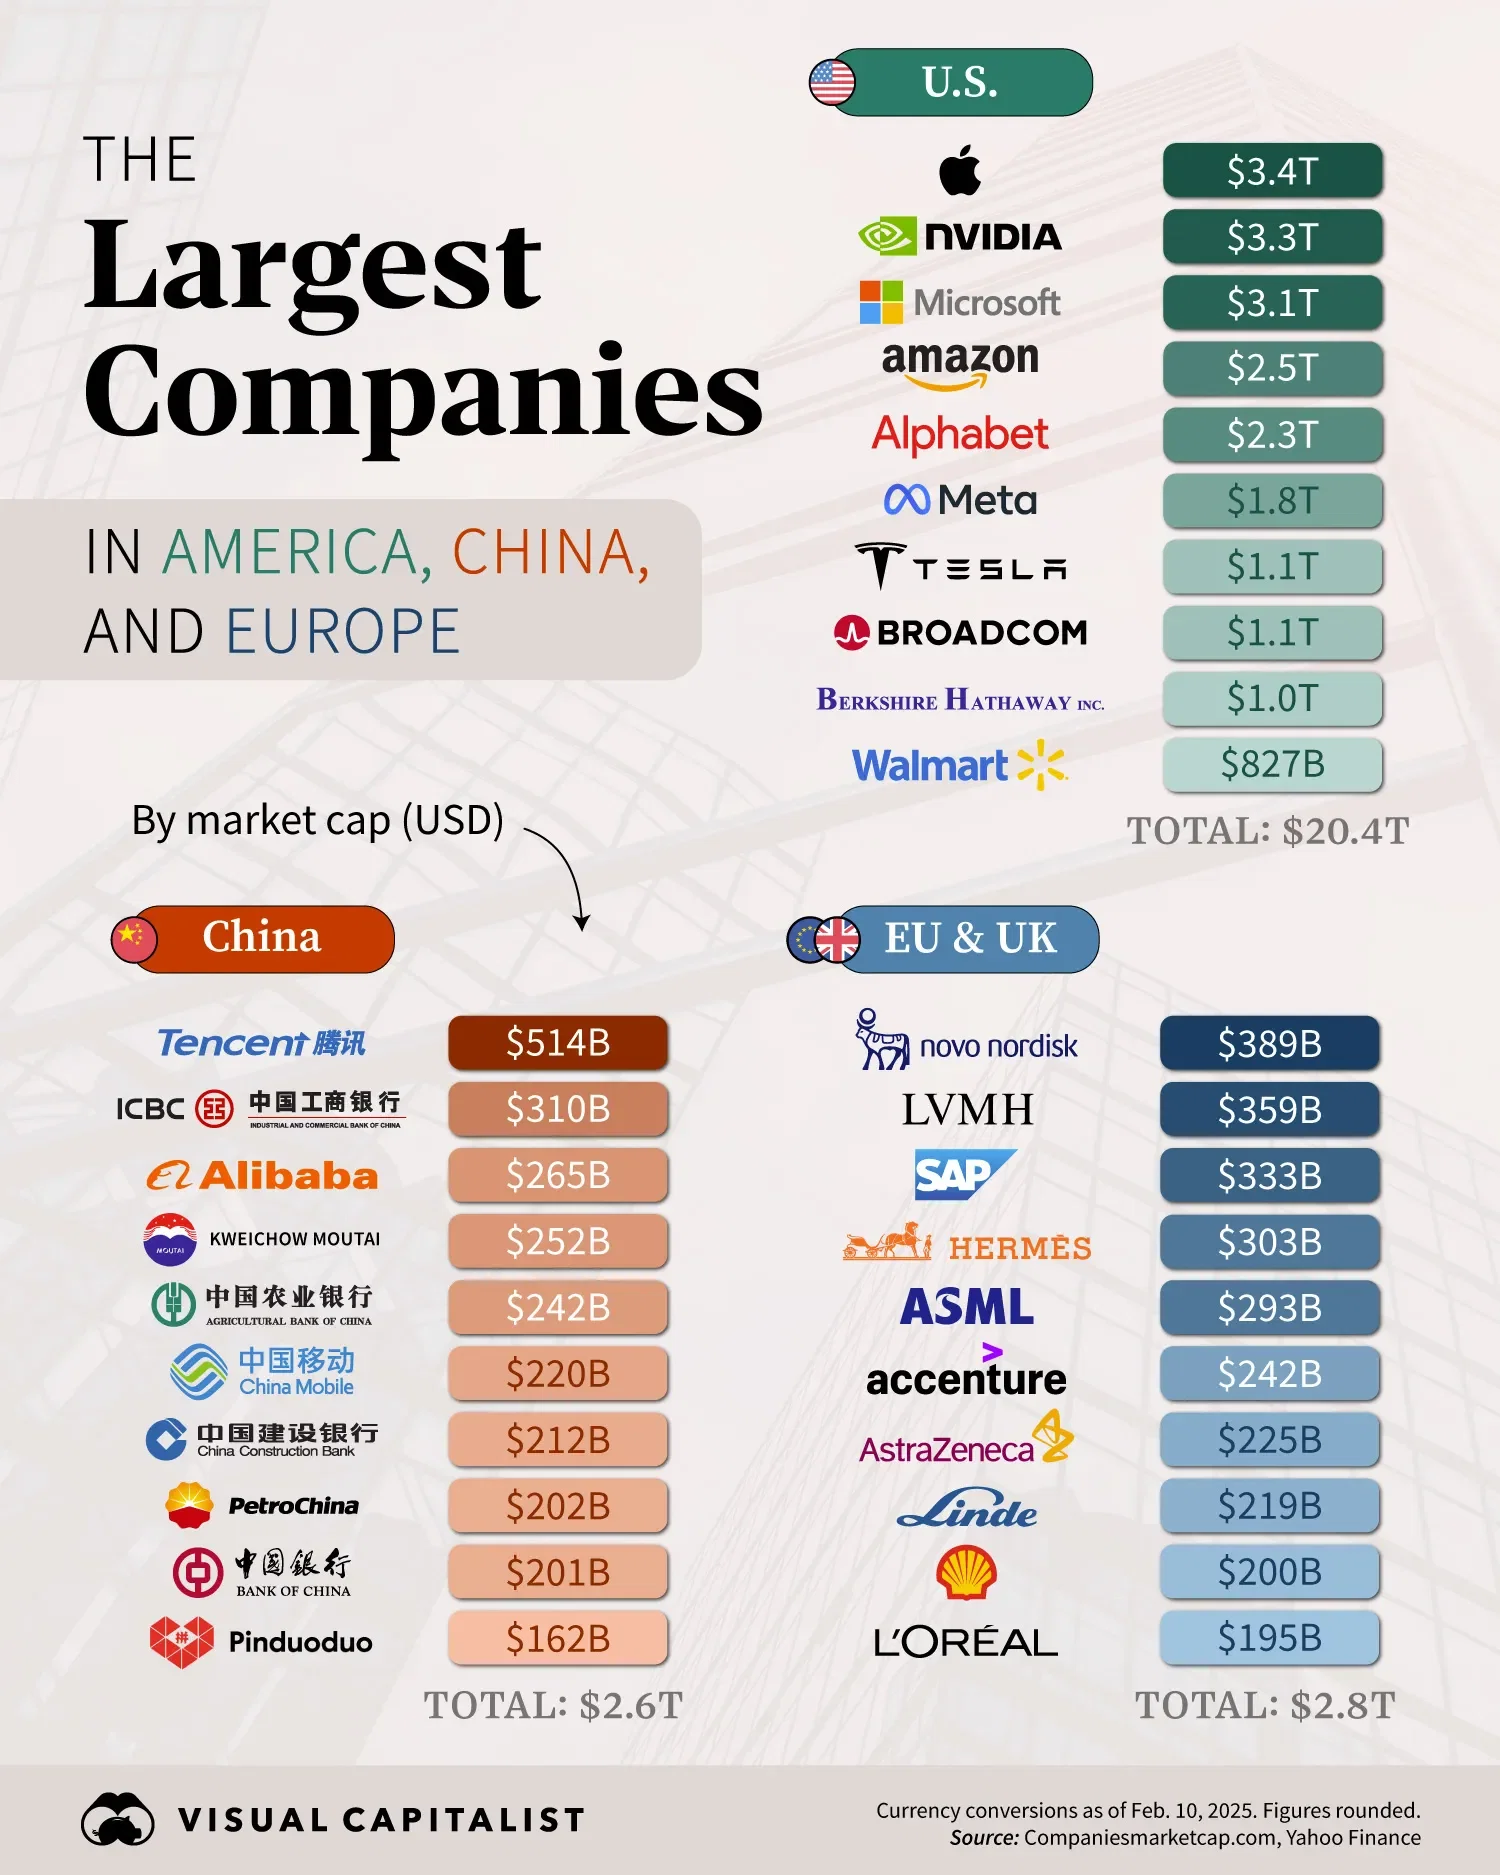
Conclusion
The rise of the largest company in net worth is a case study in how capitalism adapts to technological disruption. It didn’t invent the future; it simply ensured that the future would look like its business model. The lesson for other firms? Dominance isn’t about being first—it’s about being the last option people consider before settling. For investors, the story is one of patience rewarded. For regulators, it’s a cautionary tale about the limits of oversight in a digital economy. And for the public? The largest company in net worth has already won. The only question left is whether anyone will notice the trade-offs.Comprehensive FAQs
Q: How does the largest company in net worth compare to traditional industrial giants like ExxonMobil or GE?
The largest company in net worth in the digital era operates on fundamentally different economics. While industrial giants rely on physical assets (oil reserves, machinery), this company’s value comes from intangibles: data, algorithms, and network effects. Its profit margins are consistently higher, and its growth isn’t tied to commodity prices or manufacturing cycles.
Q: Are there any competitors that could challenge its dominance?
Several firms have attempted to compete, but none have replicated its ecosystem. Microsoft and Amazon come closest in cloud computing, while Meta dominates social media. However, the largest company in net worth maintains an advantage in search, advertising, and AI—three areas where switching costs are prohibitively high for users and businesses alike.
Q: What role does government regulation play in its growth?
Regulation has been a double-edged sword. Antitrust actions have forced divestitures (e.g., selling ad-tech units) but haven’t dented its core business. Meanwhile, tax policies in its home country have allowed it to repatriate profits at minimal cost. The largest company in net worth has mastered the art of operating within regulatory gray areas while lobbying for rules that favor its model.
Q: How does its valuation hold up during economic downturns?
Unlike cyclical industries, the largest company in net worth has shown resilience in recessions. During the 2008 financial crisis, its advertising revenue dipped but rebounded quickly as businesses shifted budgets online. In 2020, its cloud and digital services became essential for remote work, leading to record profits. Its valuation is less tied to short-term cycles and more to long-term trends in digitization.
Q: What are the biggest risks to its continued dominance?
The primary risks are regulatory overreach, technological disruption (e.g., a rival AI platform), and geopolitical fragmentation (e.g., data localization laws). Internally, talent retention and innovation fatigue could also pose challenges. However, its scale means it can absorb setbacks that would cripple smaller firms.
Q: How does it maintain its edge in innovation?
The company invests heavily in R&D, but its real advantage lies in data-driven innovation. By analyzing user behavior at scale, it can predict trends before competitors. For example, its AI research division often releases papers months before commercial applications, ensuring it stays ahead of the curve.
Q: Is there a point where it could lose its title as the largest company in net worth?
While no empire lasts forever, the largest company in net worth has structural advantages that make it difficult to dethrone. A hypothetical challenger would need to solve three problems simultaneously: build a superior product, acquire a critical mass of users, and replicate its data infrastructure. Even then, network effects would likely favor the incumbent.
