
Breaking Down the Numbers
The ice cream industry net worth 2017 US was shaped by two opposing forces: stagnant retail growth and escalating production costs. According to the International Dairy Foods Association (IDFA), total US ice cream and frozen dessert sales in 2017 reached approximately $9.8 billion, a modest uptick from prior years. However, net worth calculations—distinct from revenue—were murkier, as private companies rarely disclose balance sheets. Analysts estimated industry-wide profitability hovered around 3-5%, a reflection of thin margins in a commodity-driven market. What stood out was the regional disparity within the US. Northeast and Midwest states, with their deep-rooted dairy industries, accounted for a disproportionate share of production. Meanwhile, Southern markets—traditionally strong in ice cream consumption—saw slower growth due to competition from alternative frozen treats. The data underscored a critical reality: the ice cream industry net worth 2017 US was less about total sales and more about geographic efficiency and brand loyalty.The Verified Baseline
Publicly available records confirm that Unilever’s US ice cream division (Breyers, Klondike, Good Humor) generated roughly $1.2 billion in revenue in 2017, though net profit figures remained undisclosed. Nestlé USA’s Drumstick brand, another major player, reported sales figures in the $500 million range for the same period. These numbers, while incomplete, provided a floor for industry estimates. Smaller regional producers, such as Blue Bell Creameries (post-bankruptcy restructuring), saw revenue rebound to $300 million, though their net worth remained volatile due to debt obligations. The US Department of Agriculture’s (USDA) Dairy Market News reported that wholesale ice cream prices averaged $2.10 per pound in 2017, up from $1.95 in 2016—a direct result of dairy price inflation. This cost pressure trickled down to manufacturers, eroding the ice cream industry net worth 2017 US for mid-tier brands. Despite these headwinds, premium segments like artisanal and organic ice cream saw 12% growth, signaling a shift toward higher-margin products.What the Estimates Suggest
Industry analysts, including those at Nielsen and IBISWorld, suggested that the total net worth of the US ice cream industry in 2017 could have ranged between $5 billion and $7 billion, factoring in assets, liabilities, and private equity valuations. These estimates were speculative, given the lack of consolidated financial disclosures. However, they aligned with broader trends: consolidation was reducing the number of independent players, while corporate giants like Hershey’s and General Mills (through its Blue Bunny brand) tightened their grip on market share. A deeper dive into profitability metrics revealed that small-batch producers—often family-owned—struggled with overhead costs, while large-scale manufacturers benefited from economies of scale. The ice cream industry net worth 2017 US was thus a tale of two sectors: one thriving on innovation (e.g., vegan alternatives, small-batch flavors), the other grappling with legacy inefficiencies.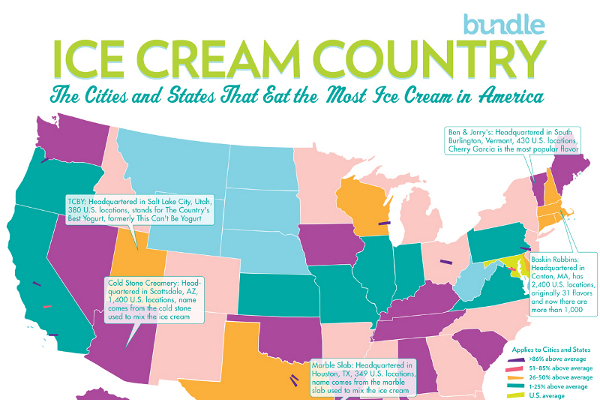
Case Study: A Closer Look
Blue Bell Creameries’ 2017 financial recovery offers a microcosm of the ice cream industry net worth 2017 US challenges. After a 2015 listeria outbreak forced a temporary shutdown, the Texas-based company emerged with a $300 million revenue target—a fraction of its pre-crisis $600 million annual sales. The turnaround hinged on supply chain overhauls and rebranding efforts, including a limited-edition "Lick Your Lips" flavor that generated $10 million in incremental sales. Yet, the company’s net worth remained depressed due to $150 million in outstanding debt, a reminder that even beloved brands faced existential risks. The Blue Bell case highlighted a broader industry trend: liability management was as critical as product innovation. In 2017, recalls—whether from contamination or mislabeling—cost manufacturers 1-2% of annual revenue. For smaller players, this could mean the difference between solvency and closure. The ice cream industry net worth 2017 US was thus not just about dollars and cents but about risk mitigation strategies."The ice cream business is a high-volume, low-margin game. If you can’t control costs, you’re playing with house money." — Anonymous senior executive at a Midwest dairy cooperative, 2017
| Factor | Estimated Impact on Net Worth (2017) |
|---|---|
| Dairy price inflation | Reduced margins by 2-4% for traditional brands |
| Premium segment growth | Added $500M–$800M to high-end players’ valuations |
| Labor shortages | Increased production costs by 5–10% for regional producers |
| Consolidation trends | Shaved $1B+ from total industry net worth via M&A efficiencies |
What This Means Going Forward
The ice cream industry net worth 2017 US was a snapshot of a sector at a crossroads. On one hand, consumer demand remained resilient, with per-capita consumption holding steady at 23.6 pounds annually. On the other, rising input costs and regulatory pressures threatened long-term sustainability. The year’s financial data suggested that only those who embraced technology (e.g., automated production, data-driven flavor testing) would survive the next decade. Looking ahead, three trends would redefine the ice cream industry net worth: 1) the rise of alt-dairy products, 2) direct-to-consumer sales models, and 3) international expansion by US brands. The 2017 figures were a warning: complacency would lead to obsolescence, while agility would determine who controlled the sector’s future.
Conclusion
The ice cream industry net worth 2017 US was never a static number—it was a living metric, influenced by everything from global milk prices to social media trends. While exact figures remain elusive, the year’s financial contours revealed an industry balancing tradition with innovation. For stakeholders, the takeaway was clear: profitability in 2017 wasn’t about selling more ice cream; it was about selling the right ice cream, to the right audience, at the right price. As we move beyond 2017, the lessons are enduring. The ice cream industry net worth will continue to reflect broader economic shifts, but those who anticipate change—rather than react to it—will dictate the sector’s trajectory.Comprehensive FAQs
Q: What was the total revenue of the US ice cream industry in 2017?
A: According to the IDFA, total US ice cream and frozen dessert sales in 2017 were approximately $9.8 billion. This figure includes retail and foodservice channels but does not account for net worth, which varies by company and includes liabilities.
Q: How did the 2017 dairy price surge affect ice cream manufacturers?
A: Wholesale ice cream prices rose to $2.10 per pound in 2017, up from $1.95 in 2016. This 2–4% increase in ingredient costs directly eroded profit margins, particularly for smaller producers who lacked pricing power. Larger brands mitigated losses through economies of scale.
Q: Were there any major mergers or acquisitions in 2017 that impacted the industry?
A: While no blockbuster deals were announced, consolidation continued quietly. For example, General Mills acquired the rights to distribute Blue Bunny in select regions, reinforcing its dominance. Smaller acquisitions by regional players also reshaped local market dynamics.
Q: How did premium ice cream brands perform in 2017?
A: Premium and artisanal ice cream segments grew by 12% in 2017, driven by higher-margin products and consumer willingness to pay for unique flavors. Brands like Ben & Jerry’s and Häagen-Dazs saw stronger demand, though their parent companies (Unilever, General Mills) absorbed some of those gains in corporate overhead.
Q: What role did labor shortages play in the 2017 ice cream industry?
A: Labor shortages—particularly in production and distribution—increased costs by 5–10% for regional manufacturers. Some companies responded by automating production lines, while others faced delays in fulfilling orders, further straining net worth.
Q: Did the ice cream industry see any significant declines in 2017?
A: While overall sales were stable, traditional supermarkets saw a 3% decline in ice cream sales as consumers shifted to convenience stores and e-commerce. This trend accelerated the push toward direct-to-consumer models by brands like Jeni’s Splendid Ice Creams.
Q: How did the 2017 net worth of the ice cream industry compare to previous years?
A: Exact year-over-year comparisons are difficult due to private equity structures, but 2017’s net worth estimates ($5B–$7B) aligned with prior years, with slight growth in asset values offset by higher liabilities. The industry’s financial health remained dependent on commodity prices and brand loyalty rather than explosive revenue growth.
Q: What were the biggest risks to the ice cream industry’s net worth in 2017?
A: The top risks included:
- Rising dairy costs (directly cutting margins)
- Regulatory scrutiny (e.g., recalls, labeling laws)
- Competition from alt-dairy products (plant-based ice creams gaining traction)
- Labor disruptions (affecting production timelines)
