
Where It All Began
The modern obsession with homeownership as a wealth anchor traces back to the post-WWII era, when the GI Bill and FHA loans made buying a house a patriotic duty. For the first time, home equity wasn’t just shelter—it was a forced savings account. By the 1960s, surveys showed that over 60% of American households owned their primary residence, and financial advisors began treating home equity as a cornerstone of long-term stability. The implicit rule? Aim for 30% of net worth in home equity by retirement. It was simple, aspirational, and dangerously one-size-fits-all. The early signs of trouble appeared in the 1970s, when oil shocks and stagflation exposed the fragility of the assumption. A 1978 Wall Street Journal article warned that families with more than 50% of net worth tied to their home were vulnerable to "sudden wealth destruction." Yet the cultural narrative—rooted in the American Dream—dismissed such warnings. Homeownership wasn’t just a financial play; it was identity. The more you owned, the more secure you were. The problem? No one was asking whether the math still held.The Turning Point
The 2008 financial crisis didn’t just crash housing markets—it shattered the myth that home equity was inherently safe. Families who had loaded up on adjustable-rate mortgages and negative-amortization loans found themselves underwater, with home values representing 80% or more of net worth—and no way out. The collapse of Lehman Brothers revealed a harsh truth: The percentage of net worth in home wasn’t just a personal choice; it was a systemic risk. Governments and regulators responded by tightening mortgage standards, but the cultural fixation on homeownership persisted. Today, the median homeowner still allocates 30–40% of net worth to their primary residence, even as economists debate whether that’s prudent."The homeownership rate isn’t just about affordability—it’s about the psychological contract between individuals and their largest asset. When that contract breaks, the fallout isn’t just financial; it’s social." — Dr. Susan Wachter, Wharton Real Estate ProfessorThe turning point wasn’t just the crash itself, but the realization that what percent of net worth should be in home had become a moving target. What worked in 1980—a 30% allocation—felt reckless in 2010. The variables had changed: student debt, stagnant wages, and the rise of alternative investments like index funds. The old rules no longer applied.
The Build-Up, Year by Year
| Period | Key Development |
|---|---|
| 1980s–1990s |
Home equity treated as "risk-free" collateral. Advisors pushed 30–50% net worth allocation for stability. The S&L crisis (1986–1991) exposed bank risks, but homeowners remained shielded. |
| 2000s |
Subprime lending and speculative buying inflated home values to 60–70% of net worth for many. The crash revealed that leverage >50% was catastrophic for marginal buyers. |
| 2010s–Present |
Post-crisis, home equity became a hedge against inflation and market volatility. Millennials, saddled with debt, now allocate 20–30% of net worth to home, prioritizing liquidity over ownership. |
Lessons From the Journey
- Leverage amplifies risk. A home representing 40% of net worth is stable; at 70%, it’s a ticking time bomb. The difference isn’t just percentage points—it’s margin of safety.
- Location matters more than ever. In high-cost cities (e.g., NYC, SF), homeownership can consume 50–60% of net worth without adding meaningful wealth. In low-cost areas, the same allocation may yield equity growth.
- Age and life stage dictate strategy. A 30-year-old with 10% of net worth in home may be prudent; a 60-year-old with the same allocation could be exposed.
- Diversification isn’t optional. Families who treat home equity as their sole asset class face liquidity crises during downturns. Post-2008, advisors now recommend no more than 25–35% of investable assets in real estate.
Where Things Stand Today
Today, the answer to what percent of net worth should be in home depends less on dogma and more on three factors: market conditions, personal risk tolerance, and alternative investment opportunities. In 2023, a family in Austin might allocate 40% of net worth to home equity—only to watch that figure spike to 55% in a year if prices surge. Meanwhile, a retiree in Florida might cap home equity at 20%, freeing up cash for healthcare and taxes. The flexibility of the past has given way to a calculus that demands constant recalibration. The shift reflects a broader truth: homeownership is no longer a binary choice between renting and buying. It’s a spectrum—one where the optimal percentage fluctuates with income volatility, career mobility, and even political stability. For the first time in decades, younger generations are questioning whether tying 30%+ of net worth to a single asset is still wise, given the rise of remote work, digital nomadism, and global investment platforms.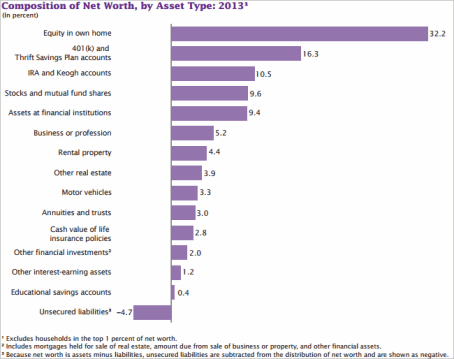
Conclusion
The question what percent of net worth should be in home has no single answer, but it does have guardrails. The data suggests that allocating between 20–40% of net worth to home equity strikes a balance for most households—provided that allocation is intentional, not accidental. The families who thrive are those who treat homeownership as one piece of a larger strategy, not the entire strategy. They diversify, they hedge, and they recognize that a home’s value isn’t just in its bricks and mortar, but in its role within their financial ecosystem. Yet the cultural pull toward homeownership remains strong. For many, the emotional and social benefits outweigh the financial risks. The challenge isn’t just calculating the right percentage—it’s resisting the urge to over-optimize for an asset that, in the end, may be less about wealth and more about belonging.Comprehensive FAQs
Q: Is there a "safe" percentage of net worth that should be in home?
There’s no universal safe percentage, but financial planners often recommend keeping home equity between 20–40% of net worth for most households. This range allows for wealth growth without over-exposure to real estate risk. However, retirees or those in high-cost markets may target 15–25%, prioritizing liquidity. The key is ensuring your home doesn’t become a financial albatross during downturns.
Q: How does student debt affect the ideal homeownership allocation?
Student debt changes the equation by reducing disposable income and liquidity. A 2022 study found that borrowers with student loans exceeding 20% of their annual income often delay home purchases, keeping home equity allocations below 15% of net worth initially. The strategy shifts from maximizing homeownership to preserving cash flow for debt repayment—sometimes indefinitely.
Q: Should I adjust my home equity percentage if I plan to move in 5 years?
If you anticipate moving within five years, keeping home equity under 20% of net worth may be prudent. Selling a home with high equity can trigger capital gains taxes, and transaction costs (agent fees, closing costs) can erode profits. For short-term owners, renting or buying with minimal down payment (e.g., 10%) may be smarter than over-investing in a property you’ll leave behind.
Q: How does homeownership allocation differ for investors vs. primary residents?
Primary residents typically aim for 25–40% of net worth in home equity, balancing shelter with long-term growth. Investors, however, may allocate 50–70%—or more—if they’re leveraging properties for cash flow or appreciation. The difference lies in risk tolerance: investors accept higher volatility for potential returns, while homeowners prioritize stability.
Q: What’s the biggest mistake people make with home equity allocation?
The biggest mistake is treating home equity as a static percentage rather than a dynamic asset. Many homeowners fail to recalculate their allocation after major life events—divorce, inheritance, job loss—or market shifts. For example, a couple whose home grows to 50% of net worth post-pandemic may not realize they’ve become over-exposed until a recession hits. Regular portfolio reviews are critical.
Q: Can I have too little net worth in home?
Yes, if your allocation is consistently below 10% of net worth, you may miss out on forced savings (mortgage payments act as disciplined investments) and tax benefits (mortgage interest deductions, property tax exemptions). However, in high-cost cities or for digital nomads, under-allocating (5–15%) can be strategic—freeing up capital for higher-yield investments or flexibility.
Q: How do I recalculate my home equity percentage if my home value fluctuates?
Recalculate annually or after major market shifts. Subtract your remaining mortgage balance from your home’s current appraised value to determine equity. Then divide that equity by your total net worth (assets minus liabilities). For example: If your home is worth $600K, you owe $200K on the mortgage, and your net worth is $1.2M, your home equity represents 33.3% of net worth. Adjust other investments (stocks, retirement accounts) to maintain your target range.
Q: What’s the impact of inflation on home equity allocation?
Inflation erodes the purchasing power of cash but tends to boost home values over time. Historically, real estate has outperformed inflation by 2–3% annually. However, if inflation spikes (e.g., 2022’s 9% CPI), homeowners with high mortgage debt may see their monthly costs rise faster than their home’s value. In such cases, capping home equity at 25–30% of net worth can provide a buffer against both inflation and mortgage rate hikes.
