
6 Things Worth Knowing About the High Net Worth Umbrella Policy
The high net worth umbrella policy operates on principles most insureds never consider. It’s not merely an extension of existing coverage; it’s a standalone risk management layer designed to interact with primary policies in ways that standard insurance cannot. Below are the six most overlooked yet decisive factors in securing one.1. It’s Not Just About the Limits—It’s About the Exclusions
Most assume a high net worth umbrella policy simply stacks coverage on top of their existing auto or home insurance. In reality, its value hinges on what it excludes. A poorly drafted policy might waive coverage for intentional acts, professional services, or even certain types of cyber liability—leaving gaps that a single lawsuit could exploit. For example, a policyholder who operates a private jet may find their high net worth umbrella policy void if they’re sued for negligence during a flight, unless they’ve explicitly added aviation liability as an endorsement. The exclusions aren’t arbitrary. They reflect the insurer’s assessment of risk tolerance. A family with a history of charitable work might face higher premiums—or stricter exclusions—if their high net worth umbrella policy includes coverage for volunteer-related incidents. The key is negotiating these clauses before signing, not after a claim arises.2. The "Self-Insured Retention" Trap
Many high net worth umbrella policies include a self-insured retention (SIR) clause, which requires the policyholder to pay the first portion of any claim before the insurer steps in. This isn’t a deductible—it’s a permanent reduction in coverage. A £1 million SIR on a £100 million policy means the insurer only pays out after the first £1 million is exhausted. For families with liquid assets, this might seem manageable. But if a judgment exceeds £101 million, the policyholder is on the hook for the remainder, regardless of prior payments. The worst-case scenario? A policyholder assumes they’ve secured £100 million in coverage, only to discover their SIR was £50 million—leaving them exposed to catastrophic losses. Always confirm whether the SIR applies per claim or per occurrence, and whether it erodes with each new incident.3. Umbrella Policies Aren’t Just for the Obvious Risks
The assumption that a high net worth umbrella policy only protects against slip-and-fall lawsuits is outdated. Today’s policies increasingly cover: - Cyber extortion: Ransomware demands targeting personal devices. - Defamation: Social media posts or private messages that spiral into libel suits. - Intellectual property disputes: Accusations of plagiarism or trademark infringement. - Family disputes: Lawsuits from estranged spouses or adult children over inheritance expectations. A tech executive’s high net worth umbrella policy might include coverage for a former employee’s claim of wrongful termination, while a real estate magnate’s policy could address a tenant’s lawsuit over mold exposure. The policy’s breadth depends on how aggressively the insured negotiates endorsements.4. The Geography of Coverage—Where Your Policy Fails You
A high net worth umbrella policy purchased in London may not follow you to the Hamptons, let alone to a secondary residence in Monaco. Jurisdictional risks are non-negotiable. For instance: - U.S. policies often exclude coverage for claims arising outside the U.S., even if the insured is a citizen. - European policies may void claims if litigation occurs in a country with weaker creditor protections (e.g., Dubai or certain Caribbean tax havens). - Offshore policies (common among non-doms) can be invalidated if the insured spends more than 183 days per year in the country where the policy was issued. The solution? A high net worth umbrella policy with a "worldwide" endorsement—but these cost significantly more and may still exclude high-risk activities like yachting or private aviation.5. The Hidden Cost of "Preferred" Insurers
Banks and wealth managers often recommend high net worth umbrella policies from their preferred partners, framing them as a "convenience." The catch? These policies may include clauses that allow the insurer to cancel coverage with 30 days’ notice—or deny claims if the policyholder files more than two lawsuits in a decade. Some even require prior approval for high-value claims, creating delays that can be fatal in litigation. The alternative? Independent brokers who specialize in high net worth umbrella policies can secure better terms, but they charge fees (typically 1–3% of premium). The trade-off? Greater flexibility and fewer surprises during claims.6. The "Nuclear Option"—When Your Policy Becomes a Liability
In rare cases, a high net worth umbrella policy can backfire. If an insured’s primary policy is deemed insufficient (e.g., a homeowner’s policy with £2 million limits on a £50 million estate), the umbrella policy may be treated as the primary coverage—leaving the insured with no recourse. This is why some ultra-wealthy families opt for standalone excess liability policies instead, which operate entirely independently of underlying insurance. Another risk: subrogation clauses. If your high net worth umbrella policy includes subrogation, the insurer can sue third parties (e.g., a contractor) to recover payments made on your behalf—potentially damaging business relationships or personal connections."Most high-net-worth clients assume their policy will cover everything. What they don’t realize is that the fine print on a high net worth umbrella policy can turn a $10 million claim into a $100 million liability overnight." — Mark Reynolds, Partner at Reynolds & Co. Wealth Protection (London)

How These Facts Connect
The high net worth umbrella policy isn’t a static product—it’s a dynamic risk management tool that adapts to the insured’s lifestyle, profession, and global footprint. The six factors above reveal a system where small oversights (like an unendorsed SIR or a jurisdictional gap) can neutralize even the most robust policy. The most effective strategies combine: 1. Customization: Tailoring exclusions and endorsements to the insured’s specific risks. 2. Geographic precision: Ensuring coverage aligns with where the insured lives, works, and recreates. 3. Independent oversight: Avoiding conflicts of interest by working with specialists, not bank-recommended insurers. The table below compares the most critical elements side by side:| Factor | Standard Policy Risk | High Net Worth Solution |
|---|---|---|
| Coverage Limits | £5–10 million (often insufficient) | £50–500+ million (with layered policies) |
| Self-Insured Retention | £1–5 million (hidden exposure) | Negotiated down or waived for key risks |
| Jurisdictional Gaps | Claims denied abroad | "Worldwide" endorsements (with activity restrictions) |
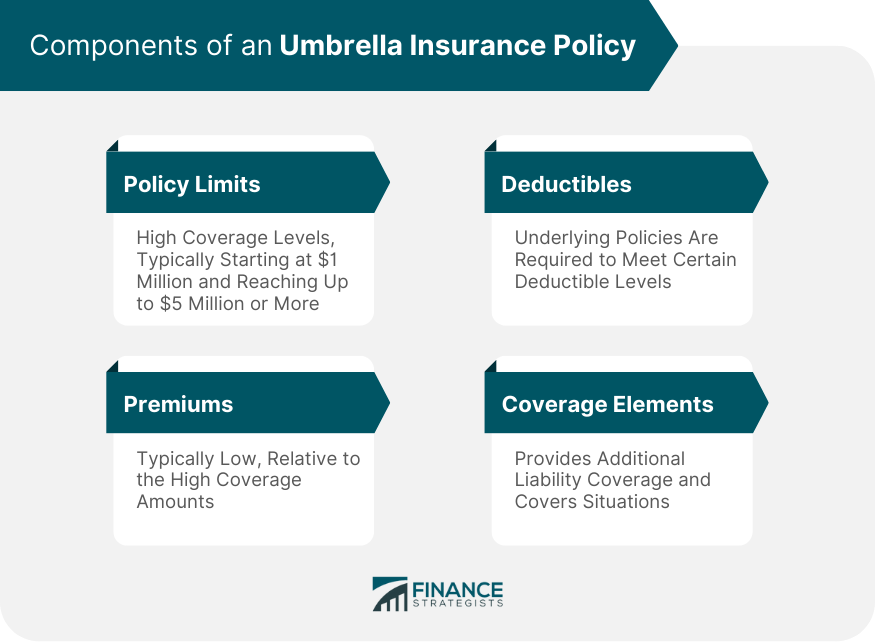
Conclusion
The high net worth umbrella policy is the quietest yet most powerful tool in an ultra-affluent household’s risk arsenal. It doesn’t prevent lawsuits—nothing does—but it ensures that a single adverse judgment doesn’t unravel a lifetime of financial discipline. The challenge isn’t securing coverage; it’s securing the right coverage, with the right exclusions, in the right jurisdictions. For those who treat it as an annual checkbox, the policy will fail when it matters most. For those who treat it as an extension of their wealth preservation strategy, it becomes the difference between resilience and ruin.Comprehensive FAQs
Q: How much does a high net worth umbrella policy cost?
A: Premiums vary widely based on coverage limits, SIR amounts, and the insured’s profession. A £100 million policy for a corporate executive might cost £10,000–£30,000 annually, while a £50 million policy for a retiree could range from £5,000–£15,000. Additional endorsements (e.g., for cyber liability) can add 20–50% to the premium.
Q: Can a high net worth umbrella policy cover business-related lawsuits?
A: Only if explicitly endorsed. Most personal high net worth umbrella policies exclude business activities unless the insured purchases a separate commercial umbrella or excess liability policy. Some insurers offer hybrid policies that blend personal and business coverage, but these are rare and expensive.
Q: What happens if my primary insurance denies a claim?
A: If your home or auto insurer denies coverage, your high net worth umbrella policy may still respond—provided the claim falls under its defined risks. However, if the primary denial stems from an exclusion (e.g., intentional acts), the umbrella policy will likely follow suit. Always review the "underlying insurance" clause in your policy.
Q: Are there alternatives to traditional umbrella policies?
A: Yes. Some ultra-wealthy families opt for: - Standalone excess liability policies: Operate independently of primary insurance. - Captive insurance: Self-insuring via a private entity (complex but offers customization). - Offshore trusts with liability shields: Used in jurisdictions like the Cayman Islands or Bermuda, though these require legal structuring.
Q: How often should I review my high net worth umbrella policy?
A: At least annually, or whenever major life changes occur (e.g., acquiring a new property, starting a business, or relocating). A policy that was adequate five years ago may now have gaps due to inflation, new risks (like AI-related lawsuits), or changes in your insurer’s underwriting standards.
