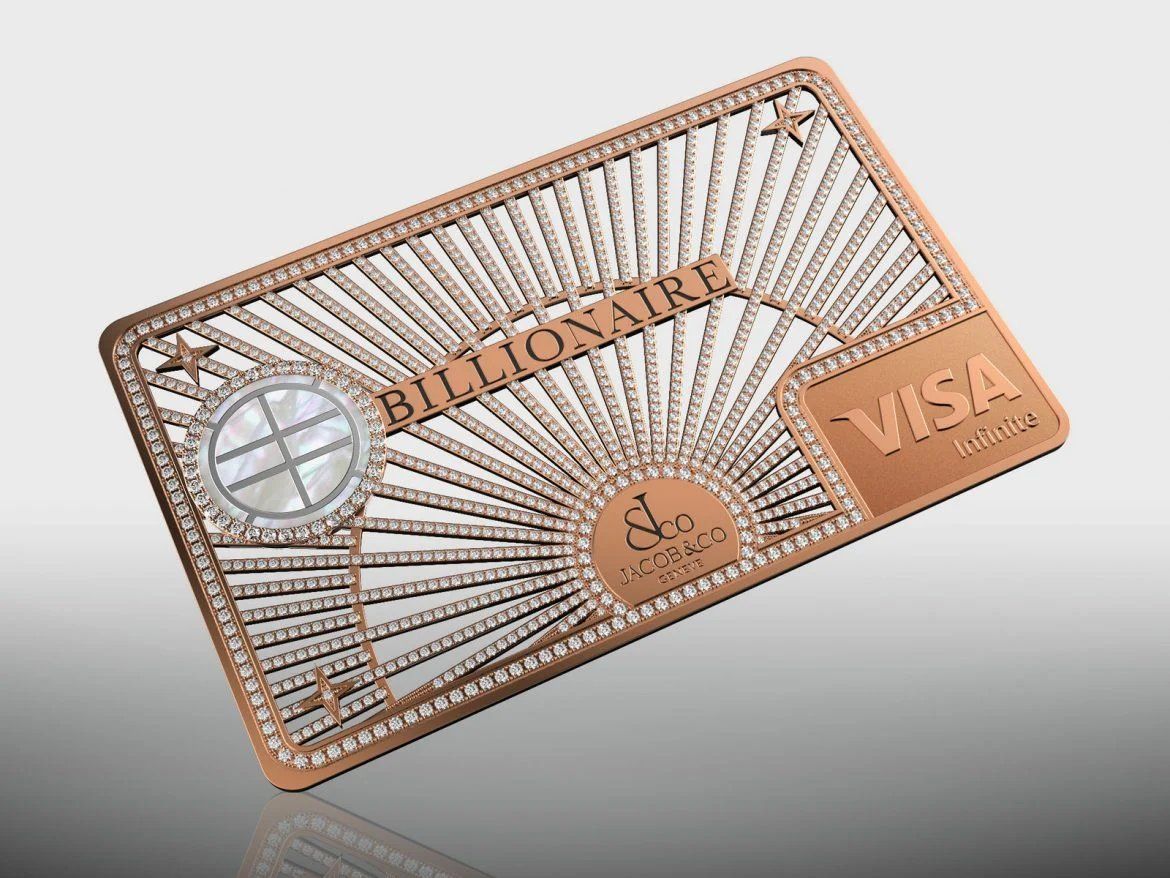
The Short Answers
- Exclusive credit cards for the rich aren’t just about rewards—they’re gated financial tools that provide direct access to elite services, from private jets to concierge-driven problem-solving.
- Qualification isn’t based on credit scores but on asset size, banking relationships, and sometimes social standing, with some cards requiring multi-million-pound net worth minimums.
- Perks vary wildly—some cards offer unlimited first-class flights, while others provide dedicated wealth managers who handle daily expenses as part of the service.
- These cards aren’t advertised; they’re extended through private invitations from wealth managers, often with no public application process.

Deep Dive: The Full Picture
The most powerful exclusive credit cards for the rich don’t function like traditional credit products at all. They’re hybrid financial-concierge tools, blending spending power with direct access to luxury services that would otherwise require separate memberships or contracts. Take, for example, the Amex Platinum Centurion Card, often called the "Black Card." While it offers elite travel benefits, its real value lies in the private network it connects holders to—concierges who can arrange last-minute VIP treatment at Michelin-starred restaurants, secure hard-to-get reservations, or even intercede with hotel managers to resolve disputes. The card isn’t the product; the relationship it unlocks is.
What separates these cards from standard premium offerings is the degree of personalization. A standard platinum card might offer lounge access and hotel upgrades; an elite card will have a dedicated team that remembers your preferences—whether it’s your favorite bottle of wine at a Parisian bistro or the exact type of private jet you prefer for transatlantic trips. The transaction isn’t just a charge; it’s a transactional handshake between the bank and the client, reinforcing loyalty through white-glove service. This level of attention isn’t scalable, which is why these cards are rationed—not by credit limits, but by how many clients a bank can reasonably serve at this level.
#### The Context You Need
The rise of exclusive credit cards for the rich mirrors the evolution of private banking itself. In the 1980s and 90s, wealth managers began offering customized financial products to ultra-high-net-worth individuals (UHNWIs), but the credit card industry lagged behind. By the 2000s, as private banking grew more competitive, issuers realized that rewards alone weren’t enough—they needed to embed access into the product. The first true "elite" cards emerged in the late 2000s, designed for clients who didn’t just want perks but demanded control over their spending experiences. Today, the market is fragmented. Some cards, like Chase’s Sapphire Reserve, cater to high earners with strong credit but not necessarily multi-generational wealth. Others, like HSBC’s Premier World Elite, are invitation-only and tied to existing private banking relationships. The most exclusive? Those issued by private banks like UBS, Credit Suisse, or Julius Baer, where the card is just one part of a broader wealth-management package. The key difference isn’t the rewards—it’s the level of discretion and influence the cardholder wields. A standard platinum card might get you into a lounge; an elite card gets you a private room with a butler. ####The Mechanics
The application process for exclusive credit cards for the rich is deliberately opaque. Unlike consumer cards, which rely on FICO scores and income verification, these products are relationship-driven. You don’t apply online—you’re invited after demonstrating consistent, high-value interactions with a wealth manager. Some banks require minimum asset thresholds, which can range from £5 million to £50 million+, though exact figures are rarely disclosed. Once approved, the cardholder isn’t just given a piece of plastic—they’re onboarded into a private ecosystem. This includes dedicated concierge teams, priority access to events, and sometimes even personal shoppers for high-end purchases. The real mechanics lie in the back-end infrastructure: these cards often interface directly with luxury service providers, bypassing standard booking systems. Need a last-minute table at Nobu Tokyo? The concierge calls the GM. Want to charter a Gulfstream for a weekend? The bank’s private aviation partner handles it. The card itself is just the entry ticket—the magic happens in the private networks it unlocks.Details That Change the Picture
Not all exclusive credit cards for the rich are created equal. Some are public-facing but ultra-restrictive, like the Amex Black Card, which requires invitation and a minimum spend of £150,000 annually. Others are completely private, issued only to clients of certain private banks and never advertised. The perks vary just as widely: while one card might offer unlimited first-class flights on Emirates, another could provide 24/7 access to a team of lawyers, doctors, and private security—effectively turning the card into a personal emergency response system.
The psychology of these cards is just as important as their features. Holding one isn’t just about what you can buy; it’s about what doors it opens. A standard platinum card might get you preferred seating at a concert; an elite card gets you backstage access to meet the artist. The difference isn’t in the transactional value but in the social capital the card represents. Banks understand this implicitly—hence the scarcity tactics, like limiting card issuance per region or requiring personal referrals from existing clients.
"These cards aren’t about rewards—they’re about control. The rich don’t want perks; they want leverage. A card that can get you into a sold-out restaurant isn’t just a tool—it’s a weapon of social engineering." — Wealth manager at a top European private bank (anonymized)
| Card Type | Key Distinction |
|---|---|
| Public Elite (e.g., Amex Black, Chase Palladium) | Invitation-only, high spend requirements, publicly acknowledged but ultra-exclusive. |
| Private Bank Cards (e.g., UBS Penta, Credit Suisse Premier) | Issued only to existing private banking clients, often with no separate application process. |
| Concierge-Driven (e.g., Barclays Platinum, HSBC Premier World Elite) | Focus on personalized service over traditional rewards, with dedicated teams for problem-solving. |
| Ultra-High-Net-Worth (UHNW) Cards | No public details, issued based on asset size and relationship depth, often with custom perks. |

Conclusion
The world of exclusive credit cards for the rich isn’t about plastic—it’s about access, influence, and the unspoken rules of elite finance. These cards don’t just move money; they reshape how the ultra-wealthy interact with the world. The most powerful ones aren’t even marketed as credit products—they’re membership passes to a parallel economy where discretion, connections, and financial firepower determine what’s possible.
For the rest of us, the allure is obvious: the idea of a card that can solve problems before they arise, or open doors that would otherwise remain closed. But the reality is more nuanced. These cards aren’t just financial tools—they’re symbols of a system where wealth isn’t just measured in numbers but in the networks you control. And in that system, the card itself is just the first handshake.
Comprehensive FAQs
#### Q: How do I qualify for an exclusive credit card for the rich?
There’s no public application process. Qualification depends on existing relationships with wealth managers, asset size (often £5M+ net worth), and discretionary spending habits. Some cards, like the Amex Black, require invitation and a minimum annual spend of £150,000+. Others are only offered to private banking clients—you’d need to be a high-value client of a bank like UBS or Julius Baer first. Cold applications are rare and usually rejected.
####Q: What’s the biggest perk of these cards?
It depends on the card, but the most valuable perk isn’t the rewards—it’s the access. For example:
- A private concierge who can resolve disputes (e.g., getting a hotel to refund a non-refundable booking).
- Priority access to sold-out events, restaurants, or even private clubs.
- Dedicated wealth managers who handle daily expenses (e.g., paying for a child’s school fees or a yacht charter).
- Private aviation credits that bypass commercial booking systems.
Q: Are these cards worth the fees?
For the target audience, yes—but only if you use the perks strategically. A £20,000 annual fee might seem steep, but if the card saves you £50,000 in last-minute travel upgrades, private school placements, or legal fees, it’s a no-brainer. However, misusing the card (e.g., treating it like a standard credit card) can make it a money pit. The value isn’t in the spending limit but in the network it unlocks.
####Q: Can I get one if I’m not a private banking client?
Unlikely. Most truly exclusive cards are only issued to existing private banking clients. If you’re not already a high-value client of a bank like J.P. Morgan, UBS, or Credit Suisse, your best bet is to:
- Build a relationship with a wealth manager who can sponsor your application for a public elite card (e.g., Amex Black).
- Increase your assets to the £5M+ range, which opens doors to invitation-only programs.
- Leverage existing luxury spending (e.g., high-end real estate, private jet purchases) to signal to banks that you’re a viable candidate.
Q: What’s the most exclusive card in the world?
There isn’t a publicly named "most exclusive" card, but two categories dominate:
- Private bank cards (e.g., UBS Penta, Credit Suisse Premier)—issued only to ultra-high-net-worth clients with no public details. These often come with custom perks tailored to the client’s lifestyle.
- Invitation-only cards like the Amex Black Card (Centurion), which has waitlists and spend requirements that make it one of the hardest to obtain in the public space.
Q: Do these cards have spending limits?
Officially, yes—but in practice, no. Most elite cards don’t have hard credit limits in the traditional sense. Instead, they operate on:
- Spend thresholds (e.g., you must spend £150,000+ annually to keep the card active).
- Pre-approved budgets for certain categories (e.g., £50,000/year on travel).
- Discretionary approvals—if you’re a long-term client, the bank may override limits for high-value purchases (e.g., a yacht, private island).
