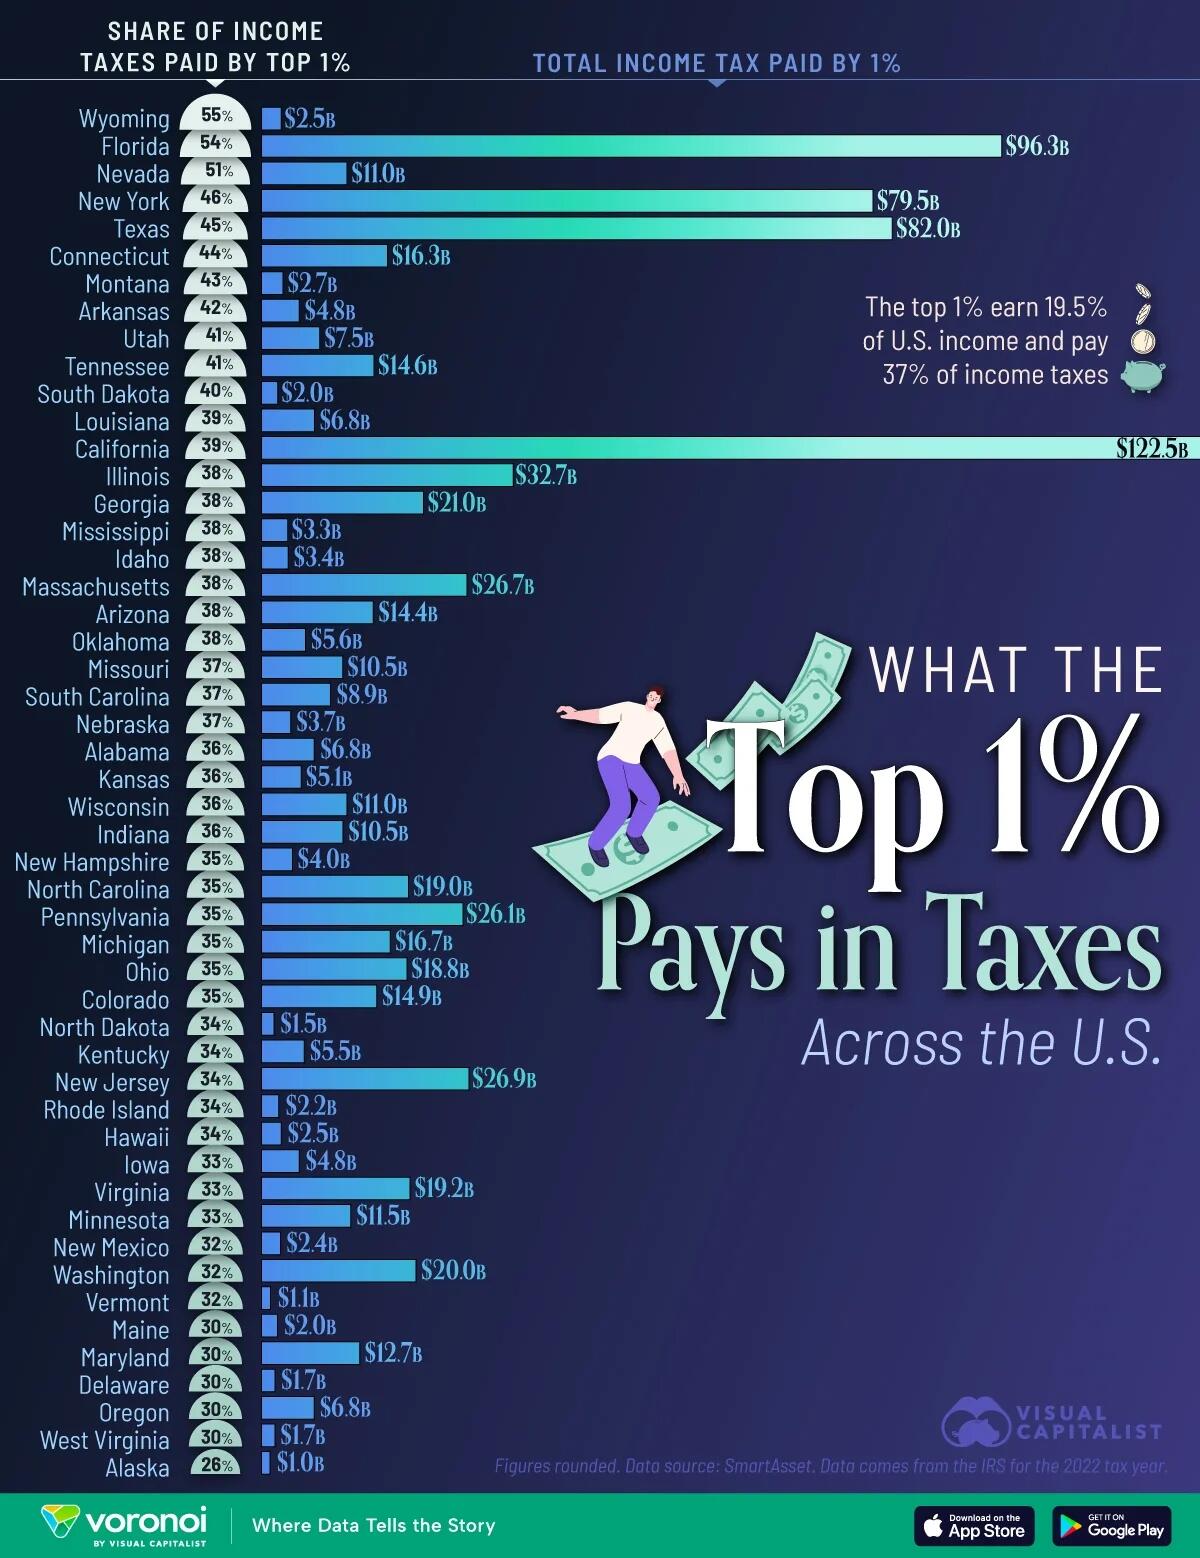
Common Myths About the Net Worth Top 1% US Taxpayers
The first misconception is that this group is dominated by young, self-made entrepreneurs. While Silicon Valley founders and crypto moguls grab headlines, the reality is that age and inheritance play a far larger role. A 2022 Federal Reserve study found that 60% of the net worth top 1% US taxpayers derive at least some wealth from family transfers—whether through direct inheritances, gifting strategies, or trusts established decades earlier. The average age of a top 1% household? Late 50s or early 60s. The second myth is that their wealth is primarily liquid—cash, stocks, or easily tradable assets. In truth, real estate and private business holdings account for nearly half of their portfolios. A single Manhattan penthouse or a stake in a closely held company can push a family into this tier overnight, yet these assets don’t show up in public filings. Another persistent belief is that this group is homogeneous, consisting mostly of white males. While men still dominate the upper echelons—70% of the top 0.1%—women and minorities are increasingly visible, particularly in legacy wealth. The Walton family (heirs to Walmart) and the Mars family (owners of Mars Inc.) are prime examples of how wealth persists across generations, regardless of gender. The final myth is that their wealth is "earned" in the traditional sense. Many fortunes are the result of asset appreciation, tax arbitrage, or monopolistic market positions—think pharmaceutical patents, media conglomerates, or agricultural land held for centuries. The line between enterprise and entitlement blurs when wealth compounds at rates most Americans can’t match.Myth 1: The Net Worth Top 1% US Taxpayers Are Mostly Tech Billionaires
The narrative that this group is defined by tech founders obscures a far more diverse economic landscape. While figures like Elon Musk or Jeff Bezos occasionally dip into the top 1%, their net worths are volatile—subject to stock market swings, lawsuits, or shifts in public perception. The true backbone of this cohort lies in older, more stable industries: finance, real estate, and legacy manufacturing. A 2023 Pew Research analysis noted that only 12% of the net worth top 1% US taxpayers have primary wealth tied to technology. The rest? Private equity managers, commercial landlords, and heirs to industrial dynasties like the Kochs or the Pritzkers. What’s often missed is how passive income sustains these fortunes. Dividends, rental yields, and trust distributions require little active labor—just maintenance of existing assets. A single family might own a portfolio of apartment buildings, a vineyard, and a stake in a regional bank, generating cash flow without needing to "work" in the conventional sense. The tech billionaire stereotype also ignores the global dimension of wealth. Many in this tier hold significant assets abroad, from European châteaux to Caribbean islands, further insulating their portfolios from domestic economic shocks.Myth 2: They Pay a Fair Share of Taxes
The idea that the net worth top 1% US taxpayers contribute proportionally to public revenues is a political talking point, not a financial reality. While they do pay more in absolute dollars than any other group, their effective tax rates often fall below those of middle-class earners. A 2022 Tax Policy Center report found that the top 400 taxpayers—those with the highest adjusted gross incomes—paid an average effective rate of 16.6%, compared to the 22%+ paid by households earning between $100,000 and $200,000. The discrepancy stems from deductions, exemptions, and the preferential treatment of capital gains, which are taxed at 15% or 20%—far below ordinary income rates. Wealth taxes, often proposed as a solution, face a fundamental obstacle: enforcement. The IRS lacks the resources to audit trusts, private foundations, or offshore accounts with precision. Even when taxes are owed, the net worth top 1% US taxpayers have the legal and financial firepower to delay payments, challenge assessments, or restructure holdings to minimize liabilities. The result? A system where wealth begets more wealth, not just through investment returns, but through tax arbitrage. The ultra-rich don’t just pay taxes—they shape the rules that determine how much they pay.Myth 3: Their Wealth Is Transparent and Easily Tracked
The public assumes that because the IRS publishes aggregate data, individual wealth is knowable. In practice, opaque structures—limited liability companies (LLCs), shell corporations, and dynasty trusts—obscure the true extent of fortunes. A single family might hold billions across dozens of entities, none of which appear on personal tax returns. The Panama Papers and Pandora Papers leaks revealed that even US citizens use foreign trusts to shield assets from scrutiny. While the IRS has improved reporting requirements (e.g., the Foreign Account Tax Compliance Act), loopholes remain, particularly for real estate and private equity, which are often held in entities with minimal disclosure. The lack of transparency extends to valuation challenges. A privately held company or a family-owned farm might be worth millions on paper, but its true market value is anyone’s guess. Appraisals can be manipulated, and without public trading data, regulators struggle to verify claims. This opacity isn’t just a technicality—it’s a strategic advantage. The net worth top 1% US taxpayers don’t just hide wealth; they engineer ambiguity, ensuring that even when taxes are due, the baseline figures are disputed.
What Holds Up to Scrutiny
The most reliable data comes from IRS Statistics of Income and Federal Reserve Survey of Consumer Finances, which track asset accumulation over time. These sources confirm that the net worth top 1% US taxpayers are not a static group—turnover exists, but mobility is rare. A 2021 study found that only 1 in 10 individuals in the top 1% stay there for more than a decade. Most are transient, pushed in by windfalls (IPOs, inheritance) or pulled out by market downturns or poor decisions. What persists is the structural advantage: those who enter with significant capital tend to stay, while newcomers face an uphill battle. The tax code’s role is undeniable. The step-up in basis (inherited assets avoid capital gains taxes) and carried interest (private equity profits taxed as capital gains) are two mechanisms that funnel wealth upward. A 2023 Brookings Institution report estimated that $2.1 trillion in wealth would have been taxed under a 2% annual wealth tax over a decade—yet no such policy exists. The reality is that the net worth top 1% US taxpayers operate within a system designed to preserve their position, not erode it."Wealth inequality isn’t an accident—it’s a feature of a tax system that rewards ownership over labor." — Emmanuel Saez, UC Berkeley economist
| Common Belief | What the Evidence Says |
|---|---|
| The net worth top 1% US taxpayers are mostly young entrepreneurs. | Median age: late 50s. 60% inherit or receive wealth transfers. |
| Their wealth is liquid (cash, stocks, public equities). | 45% held in real estate, private businesses, or illiquid assets. |
| They pay effective tax rates above 30%. | Average effective rate: ~16-18%. Capital gains and deductions reduce liabilities. |
| Wealth mobility is high—people move in and out easily. | Only ~10% remain in top 1% for more than a decade; most are transient. |
| Their wealth is easily tracked by regulators. | Opague structures (LLCs, trusts, offshore entities) obscure true holdings. |
Why the Confusion Persists
Part of the problem is selective visibility. The media focuses on outliers—Elon Musk’s Twitter purchase, Jeff Bezos’ space ventures—while ignoring the quiet accumulation of wealth in insurance annuities, municipal bonds, or family limited partnerships. These assets don’t make headlines, but they preserve generational wealth far more effectively than flashy IPOs. Another factor is political polarization. Progressives frame the net worth top 1% US taxpayers as exploiters, while conservatives argue they’re job creators. Both narratives oversimplify the reality: this group is a mix of meritocrats, beneficiaries of luck, and inheritors of structural advantages. The tax code itself contributes to the confusion. Provisions like the Qualified Business Income Deduction or Opportunity Zones are marketed as tools for small businesses, but they’re disproportionately used by high-net-worth individuals. A 2022 IRS audit found that 40% of Opportunity Zone investments came from taxpayers earning over $1 million annually. The result? Policies intended to spur economic growth instead reinforce wealth concentration. Until this dynamic is acknowledged, the debate will remain stuck between moralizing and mythmaking.
Conclusion
The net worth top 1% US taxpayers are not a monolith, nor are they a transient phenomenon. They are the beneficiaries of a tax system that rewards capital over labor, a legal structure that obscures true wealth, and an economic culture that glorifies ownership. The challenge isn’t just measuring their wealth—it’s understanding how it’s protected, expanded, and passed down. Without addressing the mechanisms that sustain this group, discussions about inequality will remain abstract. The data is clear: this isn’t about individuals failing or succeeding—it’s about a system designed to keep them at the top. The question for policymakers isn’t whether to target the net worth top 1% US taxpayers, but how to redesign the rules so that wealth accumulation doesn’t depend on inheritance, tax avoidance, or monopolistic control. Until then, the numbers will keep rising—not because of exceptional skill, but because the game is rigged.Comprehensive FAQs
Q: How does the IRS define the net worth top 1% US taxpayers?
The IRS doesn’t publish a formal threshold, but economists and tax policy analysts use $13.1 million for single filers and $18.8 million for married couples (2023 figures) based on wealth distribution data. This aligns with the point where the top 1% begins in the Federal Reserve’s Survey of Consumer Finances.
Q: Are most members of this group self-made?
No. Studies show that 60% receive significant wealth from family transfers, whether through direct inheritances, trusts, or gifting strategies. Only about 40% can be classified as "self-made" in the traditional sense.
Q: Do they pay higher taxes than middle-class earners?
In absolute dollars, yes—but their effective tax rates are often lower. The top 400 taxpayers pay an average of 16.6%, while middle-class households (earning $100K–$200K) pay 22%+. Deductions, capital gains treatment, and trusts reduce their liability.
Q: What assets do they hold most?
About 45% of their wealth is in illiquid assets: real estate (commercial and residential), private businesses, and family-owned farms. Only 20% is in public stocks or cash equivalents.
Q: How do they avoid taxes?
They use a mix of legal strategies: trusts (to defer or eliminate estate taxes), private foundations (for charitable deductions), offshore entities (to reduce capital gains exposure), and carried interest (to classify income as long-term capital gains). The IRS lacks resources to audit these structures comprehensively.
Q: Is there turnover in this group?
Yes, but it’s limited. Only ~10% of individuals remain in the top 1% for more than a decade. Most are transient, pushed in by windfalls (inheritance, IPOs) or pulled out by market downturns or poor decisions.
Q: Do they invest differently than other wealthy Americans?
Absolutely. They prioritize asset protection over growth: real estate in low-tax states, private equity with tax-advantaged structures, and alternative investments (art, wine, rare coins) that appreciate outside traditional markets. Public equities are a smaller portion of their portfolios than commonly assumed.
Q: What’s the biggest misconception about this group?
The idea that their wealth is earned in the same way as middle-class savings. Most fortunes are the result of compounding, inheritance, or monopolistic advantages—not just hard work. The system itself is the greatest asset.
