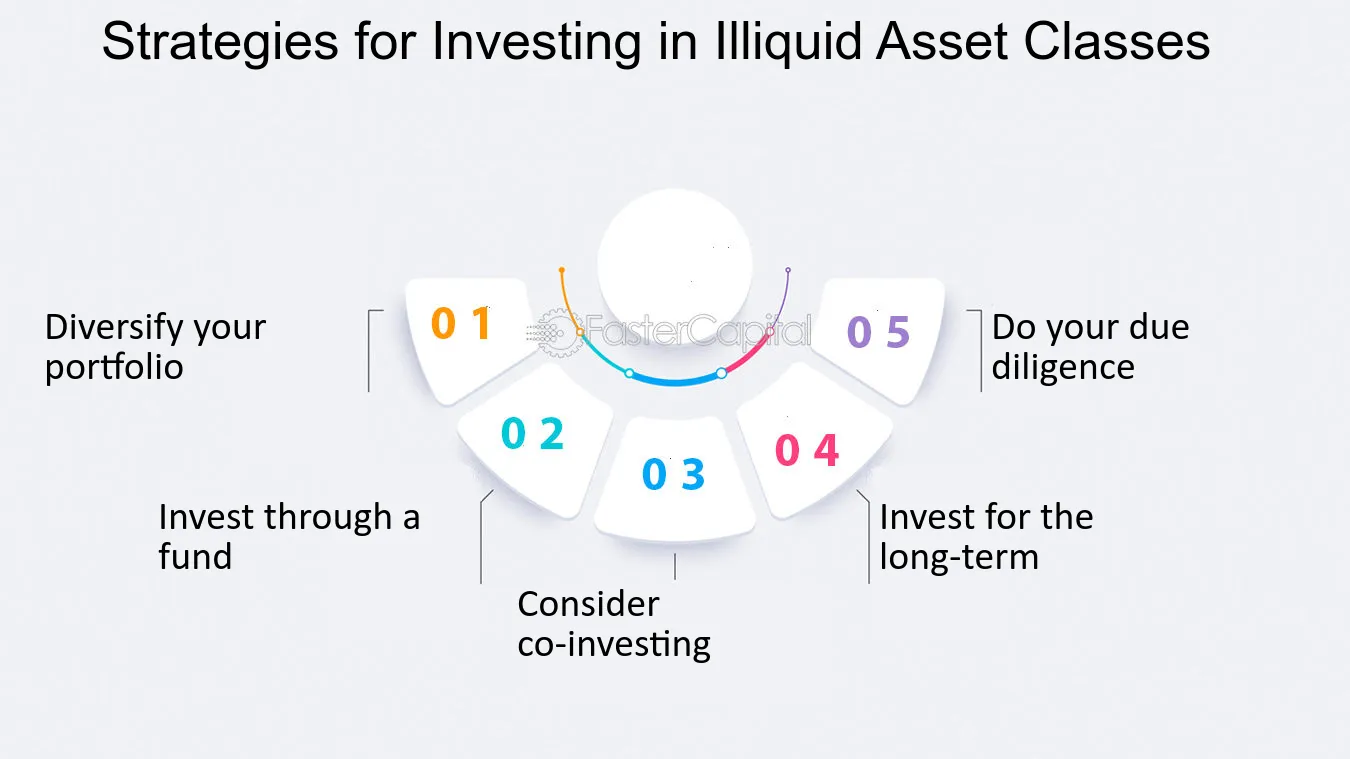
The Complete Overview of Illiquid Net Worth
Illiquid net worth refers to the portion of an individual’s or entity’s total wealth that cannot be quickly converted into cash without significant loss in value, time, or both. Unlike stocks or bonds, which can be sold in seconds, illiquid assets—real estate, private equity, art, collectibles, or even intellectual property—require specialized knowledge, legal processes, or market conditions to realize their full value. This distinction is critical because financial health isn’t measured by what’s on a balance sheet alone, but by what can actually be accessed when needed. The gap between reported net worth and usable net worth is where many high-net-worth individuals face blind spots. A family might list a $20 million art collection as part of their net worth, but selling Picasso’s Les Femmes d’Alger would take years, involve auction houses, and attract scrutiny from regulators. Similarly, a stake in a pre-IPO startup could be worth millions on paper, yet the founder might lack the connections to exit cleanly. The result? A false sense of security. Illiquid net worth is the silent partner in wealth management—often overlooked until a liquidity crisis forces its reckoning.Historical Background and Evolution
The concept of illiquid net worth has evolved alongside the rise of alternative assets. In the 19th century, wealth was predominantly tied to land, shipping fleets, or industrial enterprises—assets that required time and infrastructure to liquidate. The Industrial Revolution accelerated this trend, as family fortunes became concentrated in factories, railways, and raw materials. By the early 20th century, the emergence of public markets allowed some of these assets to be traded, but private holdings remained illiquid by necessity. The Rockefeller family’s Standard Oil stake, for example, was worth billions but couldn’t be sold without dismantling the empire itself. The post-World War II era saw a shift as institutional investors and pension funds began allocating capital to private equity and real estate, further embedding illiquid assets into wealth structures. The 1980s boom in leveraged buyouts and the rise of hedge funds expanded the universe of illiquid holdings, from unlisted companies to distressed debt. Today, the digital age has introduced new categories: cryptocurrency holdings locked in smart contracts, NFTs tied to exclusive memberships, or even intellectual property like patents or film rights. Each represents a form of wealth that exists outside traditional liquidity frameworks.Core Mechanisms: How It Works
Illiquid net worth operates on three key principles: valuation uncertainty, transaction costs, and time horizons. Valuation is the first hurdle. Unlike a publicly traded stock, which has a daily price, a private company’s worth depends on subjective metrics—earnings multiples, industry trends, or founder reputation. Real estate adds another layer: a Manhattan penthouse might appraise at $50 million, but selling it could take six months, with fees eating into 10% of the proceeds. Time horizons matter because illiquid assets are often held for decades, subjecting them to market cycles, regulatory changes, or even personal circumstances (e.g., a divorce requiring asset division). Transaction costs further erode value. Selling a minority stake in a private company might require finding a buyer willing to pay a premium, then negotiating terms that could take months. Art sales involve auction fees, storage costs, and the risk of unsold inventory. Even "liquid" alternatives like private credit funds have lock-up periods of five to seven years. The mechanism isn’t just about access to cash—it’s about the cost of accessing it. A high-net-worth individual might have $100 million in illiquid assets but only $5 million in liquid reserves, creating a structural mismatch between wealth and flexibility.Key Benefits and Crucial Impact
Illiquid net worth isn’t a bug in the wealth management system—it’s a feature. For long-term investors, these assets offer inflation protection, tax efficiency, and diversification that liquid holdings can’t match. Real estate, for instance, tends to appreciate over decades while providing rental income, shielding owners from currency devaluation. Private equity stakes in growing companies can deliver outsized returns, but only if held through market downturns. The trade-off is clear: liquidity for convenience, or illiquidity for potential outperformance. Yet the impact isn’t just financial. Illiquid assets often carry non-monetary benefits—control over a business, cultural legacy, or strategic influence. A family that owns a vineyard isn’t just investing in grapes; they’re preserving a heritage. Similarly, a tech founder’s stake in a startup might be worthless on paper but could unlock future opportunities if the company succeeds. The challenge is aligning these intangible benefits with liquidity needs, because when a medical emergency arises or a business opportunity requires capital, only cash can bridge the gap."Wealth is the ability to say no. Illiquid wealth is the ability to say no for generations." — A former CIO of a European family office
Major Advantages
- Inflation hedging: Tangible assets like real estate or commodities often outpace inflation over time, preserving purchasing power.
- Tax deferral: Illiquid assets (e.g., private company stakes) may qualify for lower capital gains rates or step-up in basis upon inheritance.
- Diversification: Private markets and alternative assets often move independently of public equities, reducing portfolio volatility.
- Control and influence: Owning a stake in a business or property grants operational leverage that liquid investments cannot.
- Legacy planning: Illiquid assets can be structured to pass wealth across generations with minimal tax impact.
- Strategic flexibility: In crises, illiquid assets can be collateralized or restructured (e.g., selling a minority stake) without triggering full liquidation.
Comparative Analysis
| Liquid Net Worth | Illiquid Net Worth |
|---|---|
| Cash, publicly traded stocks, bonds, money market funds | Real estate, private equity, art, collectibles, intellectual property |
| Instant access to capital; high transaction frequency | Valuation depends on subjective metrics; sales cycles of months to years |
| Subject to market volatility but easily rebalanced | Often insulated from short-term market swings but harder to adjust |
Future Trends and Innovations
The next decade will likely see illiquid net worth become even more dominant, driven by technological disruption and regulatory shifts. Blockchain-based assets, such as tokenized real estate or fractionalized art, could reduce some illiquidity by enabling smaller, faster trades. Private markets are also maturing, with platforms like SecondMarket and SharesPost making it easier to buy and sell stakes in private companies. However, these innovations may also introduce new risks—smart contract vulnerabilities, regulatory ambiguity around digital assets, or the potential for market manipulation in niche illiquid markets. Another trend is the institutionalization of illiquid wealth. Family offices and endowments are increasingly allocating capital to private credit, infrastructure, and even agricultural land, treating these as core holdings rather than satellite investments. The rise of evergreen funds—vehicles that continuously roll over capital into new illiquid opportunities—could further blur the line between liquid and illiquid strategies. Yet, as wealth becomes more concentrated in alternative assets, the need for liquidity management tools (e.g., private credit lines, secondary markets) will grow. The future of illiquid net worth isn’t about eliminating it—it’s about integrating it more intelligently into financial planning.
Conclusion
Illiquid net worth is the backbone of sustained wealth, but it demands a different mindset than traditional investing. The mistake isn’t holding illiquid assets—it’s assuming they’re as flexible as cash. A balanced approach requires strategic liquidity buffers, whether through dedicated cash reserves, revolving credit facilities, or diversified liquid asset classes. For high-net-worth individuals, this means treating illiquid holdings as long-term anchors while ensuring short-term needs are covered. The real test comes in crises. During the 2008 financial collapse, many private equity firms found themselves with illiquid stakes in distressed assets, unable to raise cash despite high paper valuations. Similarly, the COVID-19 pandemic exposed vulnerabilities in real estate markets, where tenants defaulted and sales stalled. The lesson? Illiquid net worth is powerful, but it must be managed with the same rigor as liquid assets. The goal isn’t to maximize illiquidity—it’s to align it with life’s unpredictable demands.Comprehensive FAQs
Q: How do I calculate my illiquid net worth?
A: Start by listing all non-liquid assets—real estate, private company stakes, art, collectibles—and estimate their fair market value using appraisals, comparable sales, or industry benchmarks. Subtract any associated liabilities (mortgages, loans). This figure represents your illiquid net worth. Note that valuations can be highly subjective, so periodic reassessments are critical.
Q: Can illiquid assets be converted to cash quickly?
A: Generally no. While some assets (e.g., a minority stake in a public company) might have secondary markets, most illiquid assets require time, expertise, or favorable conditions to sell. Strategies like selling a partial stake, taking a loan against the asset, or finding a strategic buyer can help, but none are guaranteed.
Q: Are there tax advantages to holding illiquid assets?
A: Yes. Illiquid assets often benefit from lower capital gains rates (e.g., the stepped-up basis for inherited property), long-term holding discounts, or tax-deferred exchanges (e.g., 1031 exchanges for real estate). However, illiquidity itself doesn’t create tax savings—proper structuring and professional advice are key.
Q: How much liquidity should I maintain alongside illiquid assets?
A: A common rule of thumb is to keep 12–24 months’ worth of living expenses in liquid form, plus an emergency buffer for unexpected costs. High-net-worth individuals may need more, especially if their illiquid assets are concentrated in volatile sectors (e.g., tech startups). The exact amount depends on risk tolerance, cash flow needs, and the liquidity of specific holdings.
Q: What are the biggest risks of illiquid net worth?
A: The primary risks are valuation risk (assets may be overvalued), liquidity risk (inability to sell when needed), concentration risk (over-reliance on a single asset class), and operational risk (e.g., a private company’s performance declining). Diversification across asset types and geographic regions can mitigate some of these risks.
Q: Can I invest in illiquid assets without professional help?
A: While it’s possible, illiquid assets often require specialized knowledge—whether in real estate appraisals, private equity due diligence, or art authentication. Novice investors risk overpaying, misvaluing, or failing to structure transactions optimally. Working with advisors (wealth managers, tax attorneys, or industry specialists) is strongly recommended.
Q: How do market downturns affect illiquid net worth?
A: Illiquid assets can be less volatile in the short term (e.g., real estate holds value during stock market crashes), but they’re not immune. Private companies may see delayed exits, art markets can freeze, and forced sales during downturns often occur at discounts. The key is to hold illiquid assets for the long term and avoid panic liquidations.
