
Where It All Began
The origins of the "US stock market net worth" trace back to the 18th century, when the Buttonwood Agreement of 1792—signed under a buttonwood tree in New York—formally established what would become the New York Stock Exchange. At the time, the market was a modest affair, trading securities for banks, merchants, and a handful of speculators. The "US stock market net worth" in those days was measured in thousands, not billions, and ownership was limited to those with deep pockets. The first real surge came in the 1920s, when stock prices soared, and the "US stock market net worth" expanded rapidly, luring in retail investors for the first time. The crash of 1929, however, exposed the fragility of this newfound wealth, wiping out fortunes overnight and leaving the market in ruins for decades. The post-World War II era marked the first major shift toward broader participation. The introduction of pension funds and employer-sponsored 401(k) plans in the 1970s and 1980s made stock ownership accessible to the middle class. By the 1990s, the "US stock market net worth" had grown exponentially, fueled by the rise of mutual funds and the proliferation of discount brokerages like Charles Schwab. The internet then accelerated the trend, turning stock trading into a 24/7 activity. What was once a slow, paper-driven process became a high-speed, globally connected system where the "US stock market net worth" could swing by billions in a single trading session.The Early Signs
The first cracks in the old system appeared in the 1970s, when inflation and stagnant wages made traditional savings accounts look like losing propositions. Investors, desperate for returns, turned to stocks in droves. The "US stock market net worth" began to reflect this shift, growing at rates unseen since the Roaring Twenties. The introduction of index funds in the 1970s—popularized by John Bogle’s Vanguard Group—further democratized investing, allowing small investors to mirror the performance of the S&P 500 without picking individual stocks. Yet, the real turning point came with the deregulation of the financial sector in the 1980s and 1990s. The repeal of the Glass-Steagall Act in 1999 blurred the lines between commercial and investment banking, enabling institutions to take on more risk. This era also saw the rise of private equity and hedge funds, which began siphoning off massive chunks of the "US stock market net worth" into alternative assets. The stage was set for the market to evolve from a tool for wealth preservation into a machine for wealth creation—sometimes ethically, sometimes not.The Turning Point
The moment the "US stock market net worth" became a defining feature of the American economy arrived in the late 1990s, during the dot-com boom. For the first time, the market’s growth wasn’t just about corporate profits—it was about hype, speculation, and the belief that technology stocks could defy gravity. The "US stock market net worth" surged past $10 trillion, and ordinary investors, armed with online brokerages, piled in. The bubble’s eventual burst in 2000 was a brutal correction, but it didn’t erase the lesson: the market had become too big to ignore. What followed was a decade of consolidation. The "US stock market net worth" recovered swiftly, powered by low interest rates, corporate buybacks, and a new wave of retail investors drawn in by platforms like Robinhood. The 2008 financial crisis tested the system again, but this time, the response was different. The Federal Reserve’s aggressive intervention—slashing interest rates and injecting trillions into the economy—prevented a repeat of the 1930s collapse. The "US stock market net worth" not only survived but thrived, reaching new highs as the economy slowly stabilized."The market doesn’t just reflect the economy—it shapes it. By the 2010s, the US stock market net worth had become so large that its movements dictated policy, influenced elections, and even altered consumer behavior." — Economist and author Michael Lewis, in The Big Short

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1970s–1980s |
|
| 1990s |
|
| 2000s |
|
| 2010s–Present |
|
Lessons From the Journey
- Wealth creation isn’t linear. The "US stock market net worth" has seen cycles of euphoria and despair, but each downturn has been followed by a stronger recovery.
- Accessibility doesn’t guarantee equity. While more people own stocks, wealth disparities persist—top 10% hold the majority of the "US stock market net worth".
- Technology amplifies both opportunity and risk. The rise of algorithmic trading and social media-driven speculation has made the market more volatile.
- Policy matters. Deregulation in the 1990s and 2000s expanded the "US stock market net worth", but it also contributed to financial instability.
- Patience beats timing. The S&P 500’s long-term growth underscores that consistent investing outperforms market timing.
- The market is a reflection of society. Booms and busts aren’t just economic—they’re social and psychological phenomena.
Where Things Stand Today
As of 2024, the "US stock market net worth" hovers around $60 trillion, a figure so vast it’s nearly incomprehensible. The S&P 500 alone accounts for roughly half of that total, with tech giants like Apple, Microsoft, and Nvidia driving much of the growth. The composition of the market has shifted dramatically: financials and industrials have given way to consumer discretionary and technology stocks, mirroring broader economic trends. Meanwhile, retail investors—now a quarter of all traders—have reshaped the market’s dynamics, with meme stocks and short squeezes becoming regular headlines. Yet beneath the surface, cracks are forming. Valuations in some sectors are stretched, and geopolitical tensions, inflation, and interest rate policies cast shadows over future growth. The "US stock market net worth" is no longer just a measure of economic health; it’s a barometer of global confidence. For better or worse, its fluctuations now ripple across borders, influencing everything from currency markets to geopolitical alliances. The question isn’t whether the market will continue to grow—it’s how sustainably, and who will benefit most.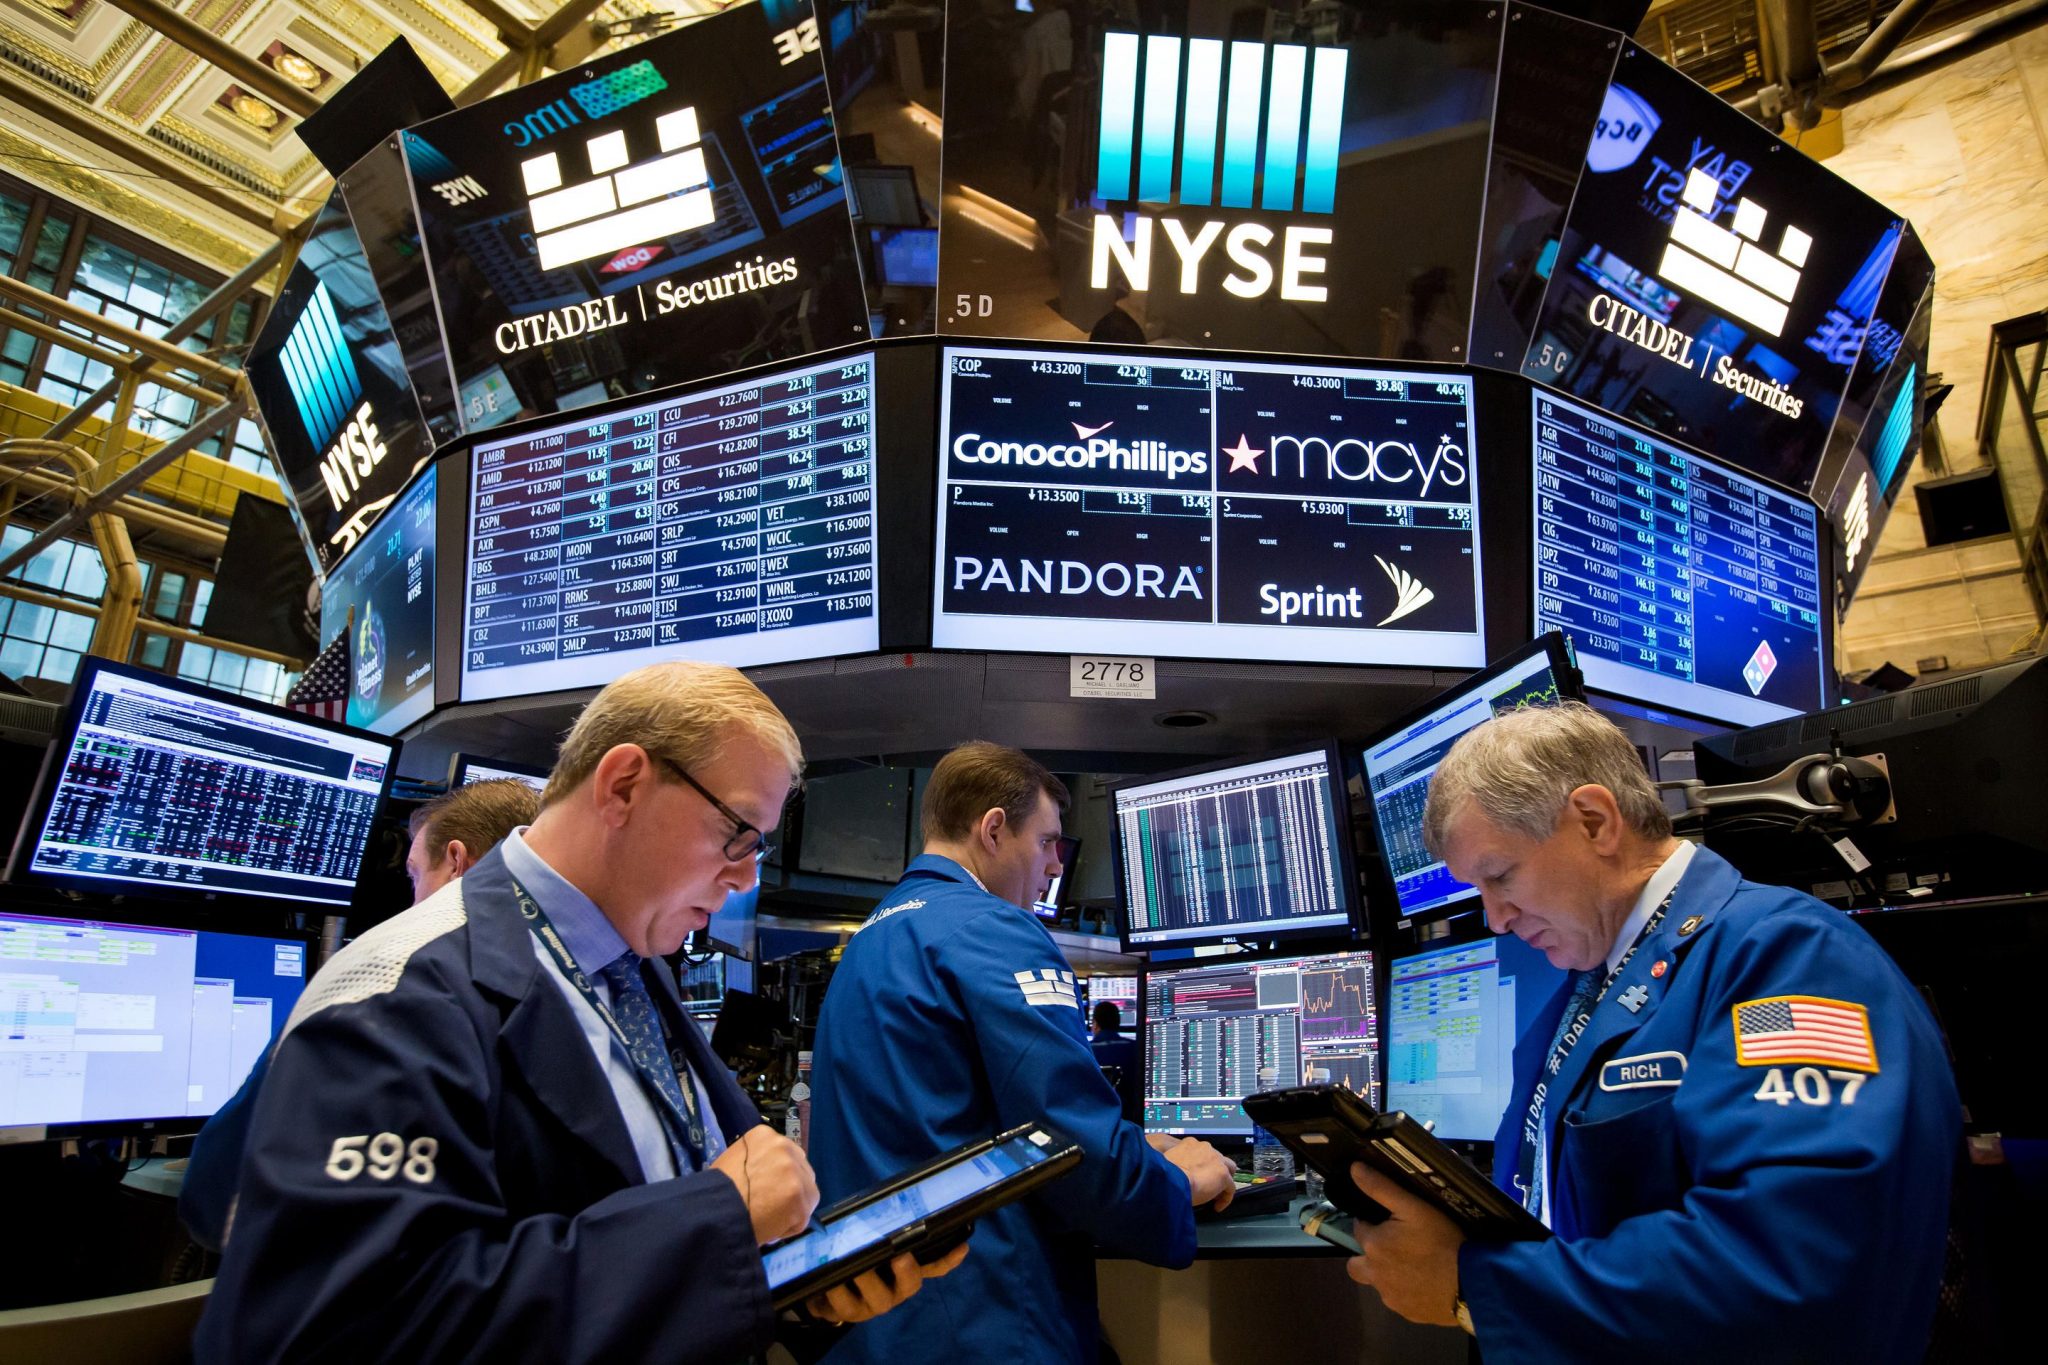
Conclusion
The story of the "US stock market net worth" is more than a financial history—it’s a narrative of ambition, risk, and reinvention. From its humble beginnings under a buttonwood tree to its current status as the world’s largest wealth repository, the market has evolved alongside America itself. It has rewarded innovation, punished recklessness, and repeatedly proven that wealth is as much about timing as it is about strategy. Today, the "US stock market net worth" stands as a testament to capitalism’s power to create—and its capacity to destroy. The challenge ahead is balancing growth with stability. As the market continues to expand, the risks of inequality, speculation, and systemic shocks grow. The lesson from past cycles is clear: the "US stock market net worth" will keep rising, but its sustainability depends on how well society adapts to its ever-changing nature. For investors, policymakers, and everyday Americans alike, the market remains both an opportunity and a warning—a force that can build fortunes or erase them in the blink of an eye.Comprehensive FAQs
Q: How is the "US stock market net worth" calculated?
The "US stock market net worth" is derived by summing the market capitalizations of all publicly traded companies (via indices like the S&P 500) and adding private equity, hedge funds, and retirement accounts tied to equities. It’s a moving target, updated daily with market closes. Unlike GDP, it excludes non-financial assets like real estate or bonds unless they’re equity-linked.
Q: Who owns the majority of the "US stock market net worth"?
According to Federal Reserve data, the top 10% of households hold roughly 80% of all stock market wealth. Institutional investors (pension funds, endowments) own another 30%, while retail investors account for the remaining 20%. The disparity highlights how wealth concentration persists even as ownership broadens.
Q: Can the "US stock market net worth" ever shrink significantly?
Yes. Historically, it has dropped by 30–50% during recessions (e.g., 2008, 2020). However, long-term trends show it always recovers—often within 3–5 years—as economic activity and corporate earnings rebound. The risk isn’t permanent loss but prolonged stagnation, which can erode real returns.
Q: How does the "US stock market net worth" affect everyday Americans?
For those with retirement accounts (401(k)s, IRAs), it directly impacts their savings. Even without direct stock ownership, the market influences wages (via corporate profits), housing costs (linked to interest rates), and job markets (tech-driven growth sectors). Indirectly, it shapes consumer confidence—when the "US stock market net worth" rises, spending and hiring tend to follow.
Q: Are there alternatives to relying on the stock market for wealth?
Yes, but each has trade-offs. Real estate offers tangible assets but lacks liquidity. Bonds provide stability but lower returns. Cryptocurrencies and commodities are speculative. The "US stock market net worth" remains the most reliable long-term wealth builder due to its historical growth (~7% annualized returns), but diversification is key to managing risk.
Q: What’s the biggest threat to the "US stock market net worth" today?
Three factors stand out: overvaluation in high-growth sectors (e.g., tech), geopolitical instability (trade wars, sanctions), and policy missteps (interest rate hikes, regulatory crackdowns). Additionally, demographic shifts (aging boomers withdrawing from markets) and climate risks could disrupt traditional asset classes. The market’s resilience suggests it will adapt—but not without volatility.
