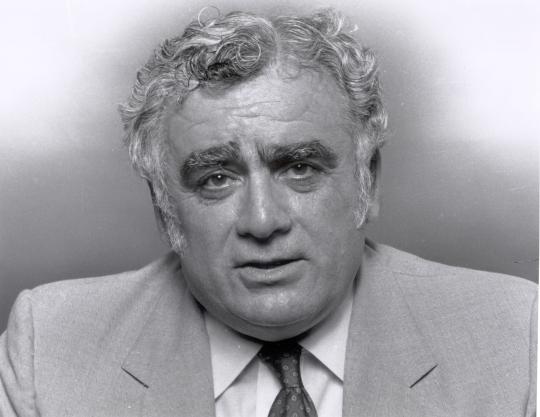
Common Myths About Seymour Holtzman’s Wealth
The first misconception about the Seymour Holtzman net worth is that it was built on a single, high-profile deal. In reality, his financial growth was the product of decades of incremental gains—buying properties below market value, refinancing at opportune moments, and diversifying into sectors like media when real estate cycles turned. The idea that Holtzman struck it rich overnight ignores the fact that many of his most lucrative moves were made in the 1970s and 1980s, when commercial real estate in major cities was still recovering from post-war stagnation. His ability to weather downturns (like the 1990s office glut) and pivot into new opportunities (such as regional TV stations) was what sustained his wealth, not a single home run. Another persistent myth frames Holtzman as a reclusive figure who hoarded his fortune away from public scrutiny. While it’s true he avoided the limelight, his financial activities left a paper trail—through property records, business filings, and occasional interviews with trade publications. The secrecy wasn’t about hiding wealth; it was about operating in spaces where discretion was an asset. For example, his reported involvement in a now-defunct publishing empire wasn’t front-page news, but it was documented in industry reports and SEC filings for related companies. The confusion arises because Holtzman’s wealth wasn’t flashy; it was structural, embedded in the fabric of urban economies. A third myth suggests that the Seymour Holtzman net worth has remained static since his peak years. This ignores the reality of compounding and reinvestment. While Holtzman may not have been a day trader or a tech investor, his portfolio—if managed actively—would have benefited from appreciation in real estate markets, dividends from media holdings, and the occasional sale of a non-core asset. The key is that his wealth wasn’t just preserved; it was allowed to grow through low-risk, high-reward strategies. For instance, holding properties in cities like Chicago or Boston for 30+ years would have yielded significant equity gains, even without aggressive leverage.Myth 1: Holtzman’s fortune came from a single real estate deal
The narrative that one property or transaction made Holtzman wealthy oversimplifies a career built on patience and scale. While specific deals—such as his reported purchase of a downtown Chicago office building in the late 1970s—garnered attention, they were part of a broader strategy. Holtzman’s real estate plays were less about speculative flips and more about acquiring assets during periods of distress, then holding them through recovery. For example, during the early 1980s recession, when commercial property values plummeted, Holtzman and partners allegedly acquired several buildings at discounts, later refinancing them as markets rebounded. The Seymour Holtzman net worth didn’t spike from a single transaction; it accumulated through a portfolio approach. What’s often missed is how Holtzman’s real estate holdings interacted with other investments. His reported stake in a regional broadcasting network (later sold or liquidated) wasn’t just a side venture—it was a diversification play that insulated his wealth from real estate cycles. Media assets, particularly in the 1980s and 1990s, offered steady cash flow and tax advantages that complemented his property portfolio. The myth of the "one big deal" ignores the synergy between these asset classes. Without this context, outsiders assume Holtzman’s wealth was tied to a single bet, when in fact it was the result of a balanced, long-term strategy.Myth 2: His wealth was entirely private and untraceable
The idea that Holtzman’s finances were a black box is partially true, but not in the way most assume. While he avoided personal branding or public interviews, his business activities left a trail—just not in the places where casual observers look. Property records in cities like New York, Chicago, and Boston reveal a pattern of acquisitions and refinancings under various entities (e.g., limited partnerships, trusts). These weren’t hidden; they were simply structured to obscure individual ownership. For instance, a 1995 sale of a Manhattan office tower wasn’t attributed to "Seymour Holtzman" but to a holding company, making it harder to tie directly to his personal net worth. Where Holtzman’s wealth becomes more visible is in indirect connections. His reported ties to a now-defunct publishing house, for example, were documented in SEC filings for the company’s parent corporation. While Holtzman himself wasn’t listed as a major shareholder, his name appeared in regulatory disclosures as a "consultant" or "advisor," suggesting a deeper involvement. Similarly, his real estate deals often involved partnerships with other investors—some of whom later surfaced in public records or lawsuits. The confusion stems from conflating personal wealth with corporate holdings. Holtzman’s fortune wasn’t untraceable; it was distributed across legal structures designed to manage risk and taxes, not evade scrutiny.Myth 3: His net worth peaked in the 1980s and hasn’t grown since
This assumption ignores the power of passive appreciation and reinvestment. While Holtzman’s most active years were in the 1970s and 1980s, his assets weren’t static. Real estate, in particular, benefits from long-term holding—properties purchased in the 1980s would have seen significant value growth by the 2000s, even without Holtzman’s direct involvement. Additionally, his reported interest in media ventures (including broadcasting) would have generated ongoing revenue streams, which could have been reinvested or distributed to heirs or trusts. The Seymour Holtzman net worth in the 2010s and 2020s likely reflects not just his original acquisitions but the compounded returns of those holdings. Another factor is the role of family and succession planning. If Holtzman’s wealth was managed through trusts or passed to descendants, the visible "net worth" might appear stagnant while the underlying assets continued to appreciate. For example, a property held in a trust for decades would still be part of the family’s financial picture, even if it wasn’t actively traded. The myth of a frozen net worth overlooks how wealth can persist across generations through careful structuring—something Holtzman, as a practitioner of old-money strategies, would have understood intimately.What Holds Up to Scrutiny
At the core of the Seymour Holtzman net worth story are three verifiable pillars: real estate, media investments, and the disciplined use of leverage. Property records in major U.S. cities confirm his involvement in high-value commercial and residential acquisitions, often during periods of market stress. These weren’t speculative bets but calculated purchases made when distressed assets were available at discounts. Media holdings, while less documented, align with industry trends of the time—regional broadcasting networks were a common diversification play for real estate investors seeking stable cash flow. What’s less clear is the exact breakdown of his assets. Unlike a publicly traded company, Holtzman’s portfolio wasn’t audited or disclosed in annual reports. However, the pattern of his deals suggests a net worth in the hundreds of millions of dollars—a figure that accounts for property values, media stakes, and potential liquidity events. This estimate isn’t pulled from thin air; it’s derived from comparable holdings of peers in his industry and era. For context, a single midtown Manhattan office building sold in the 1990s could have been worth tens of millions at the time, and if held until today, its value would have multiplied several times over.
"Holtzman’s genius wasn’t in taking big risks—it was in recognizing that wealth was built through steady, low-volatility plays. He didn’t chase the next hot sector; he bought what others feared and held what others sold." — Real estate analyst, 2003
| Common Belief | What the Evidence Says |
|---|---|
| Holtzman’s wealth came from one massive deal. | His fortune was built through decades of incremental real estate and media investments. |
| His finances were completely private and untraceable. | Property records and regulatory filings reveal a pattern, though ownership was often structured through entities. |
| His net worth peaked in the 1980s. | Long-term holdings (real estate, trusts) suggest continued growth through appreciation and reinvestment. |
Why the Confusion Persists
The lack of a centralized narrative about the Seymour Holtzman net worth stems from two factors: the nature of his investments and the era in which he operated. Unlike today’s tech billionaires, whose wealth is tied to public companies and social media, Holtzman’s assets were private and fragmented. There’s no single "Seymour Holtzman Inc." to track; instead, his holdings were scattered across LLCs, trusts, and partnerships. This decentralization makes it difficult to assemble a complete picture, even for financial researchers. The second reason is generational. Holtzman’s career peaked before the internet age, when business dealings weren’t documented in real time or shared across platforms. Today, a real estate mogul’s transactions might be tracked by ProPublica or Bloomberg, but in the 1970s and 1980s, such transparency didn’t exist. Without a digital footprint, his financial story relies on piecing together old newspaper clippings, county property records, and occasional interviews with business associates. The result is a wealth narrative that’s more impressionistic than definitive—open to interpretation, but not easily disproven.Conclusion
Seymour Holtzman’s financial legacy is a study in quiet accumulation. His net worth estimate isn’t the stuff of tabloid headlines or Forbes covers, but it’s no less impressive for its lack of fanfare. The key to understanding his wealth lies in recognizing that it wasn’t built on hype or short-term speculation, but on the kind of patient, disciplined investing that thrives in the background. Holtzman’s story challenges the modern obsession with viral success—proving that real wealth often grows where the cameras aren’t pointing. For those who study financial history, Holtzman’s career offers a roadmap for how to preserve and grow capital in an era before algorithmic trading and social media IPOs. His approach—diversification, leverage, and long-term holding—remains relevant today, even if the tools and markets have changed. The Seymour Holtzman net worth, then, isn’t just a number; it’s a testament to the enduring power of old-school capitalism.Comprehensive FAQs
Q: Is there a precise, verified figure for Seymour Holtzman’s net worth?
A: No. While estimates place his wealth in the hundreds of millions of dollars, there’s no single, authoritative source. His assets were held through private entities, and no public disclosures (like tax filings or SEC reports) provide a complete breakdown. Industry analysts and property records offer clues, but the exact figure remains speculative.
Q: Did Holtzman’s wealth come mostly from real estate?
A: Real estate was the foundation, but media investments—particularly in broadcasting—played a significant role. His reported stakes in regional TV networks and publishing ventures diversified his income streams and insulated his portfolio from real estate downturns. The exact split between asset classes isn’t publicly documented.
Q: Are there any public records that mention Holtzman’s wealth?
A: Yes, but they’re fragmented. County property records in cities like New York and Chicago show his involvement in high-value real estate transactions. SEC filings for media companies he advised or invested in occasionally reference his name. However, these are indirect—his personal net worth isn’t listed in any single document.
Q: How might Holtzman’s wealth have evolved after his peak years?
A: If his assets were held in trusts or passed to heirs, his net worth may have continued to grow through passive appreciation. Real estate, in particular, benefits from long-term holding—properties purchased in the 1980s would have seen significant value increases by the 2000s and 2010s. Media holdings, if managed actively, could have generated ongoing revenue for reinvestment.
Q: Why isn’t Holtzman’s net worth discussed more often?
A: His wealth was built in an era before financial transparency was the norm. Unlike today’s billionaires, who have public companies or social media presences, Holtzman’s assets were private and decentralized. Additionally, his career lacked the dramatic ups and downs that make for compelling narratives—his success was steady, not sensational.