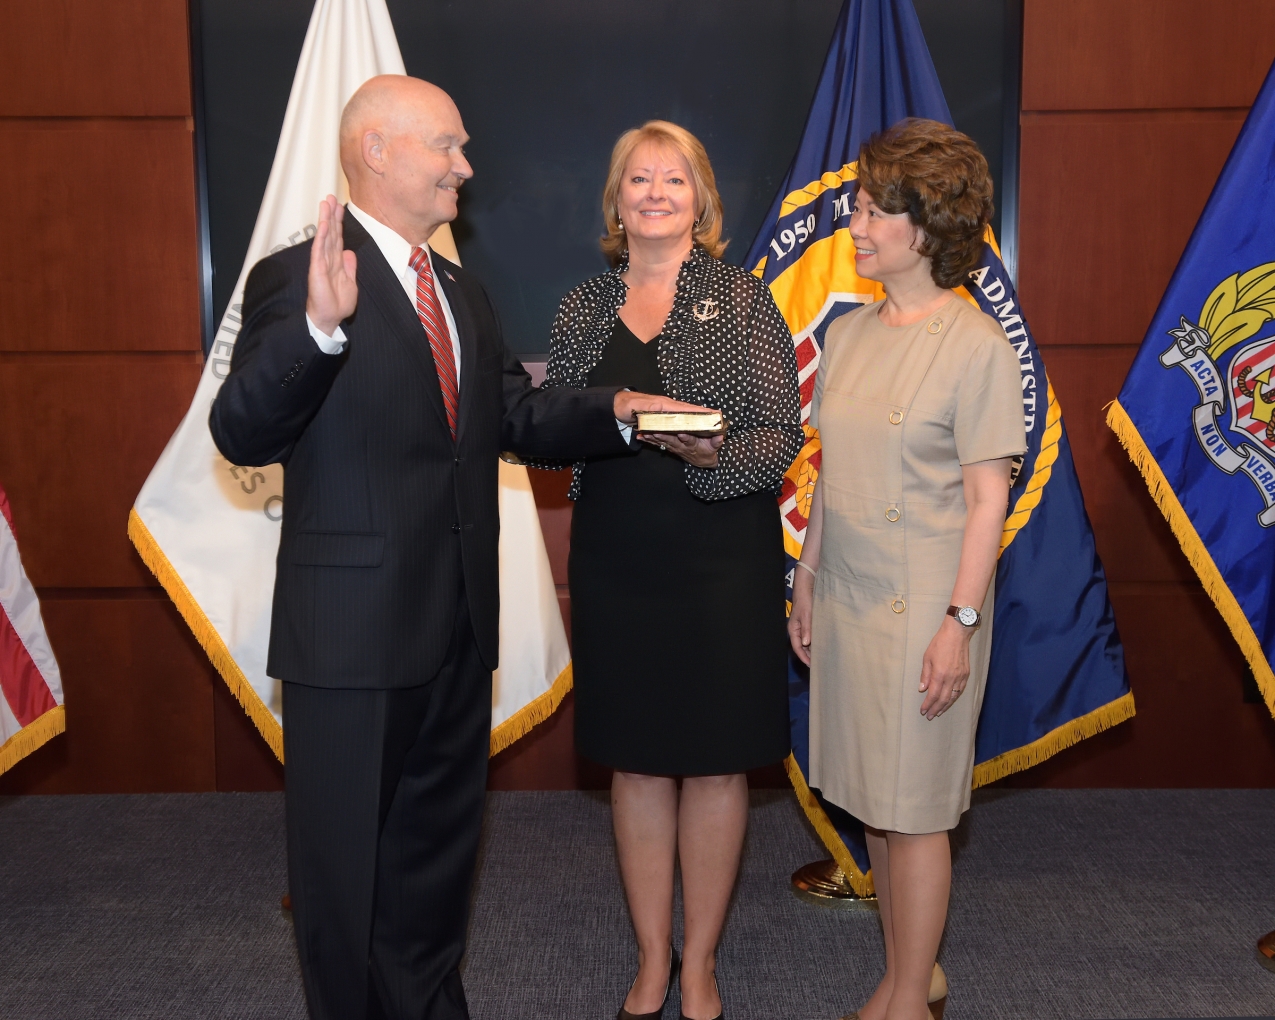
Rear Admiral Mark H. Buzby’s name surfaces in discussions about naval leadership, operational command, and the intersection of military service with financial outcomes. As a senior officer in the U.S. Navy, his career spans decades of service, culminating in high-stakes roles that often blur the line between public duty and private compensation. Yet when it comes to
rear admiral mark h. buzby net worth, the picture is neither straightforward nor fully transparent. Unlike civilian executives or athletes, military officers—especially those in flag rank—operate within a compensation framework governed by federal pay scales, allowances, and post-service benefits. The result? A net worth that’s difficult to pin down with precision, even for those tracking defense-sector finances.
What
is clear is that Buzby’s career trajectory positions him among the upper echelons of naval leadership. His tenure includes command of the USS
Harry S. Truman aircraft carrier strike group, a role that demands operational expertise and strategic oversight. Such positions, while not directly tied to personal wealth accumulation, often lead to post-military opportunities in defense contracting, consulting, or government advisory roles—sectors where financial disclosures are voluntary and opaque. The question isn’t whether Buzby has amassed significant assets; it’s how those assets were acquired, how they’re structured, and why the public has so few concrete answers.
The ambiguity around
rear admiral mark h. buzby net worth stems from a combination of factors: the classified nature of military pay details, the lack of mandatory public disclosures for retirees, and the indirect pathways through which officers transition into lucrative civilian careers. Unlike corporate CEOs or tech founders, whose wealth is often tied to stock options or public filings, Buzby’s financial standing is a patchwork of federal salary, retirement benefits, and potential post-service earnings. Untangling these threads requires parsing pay scales, understanding deferred compensation, and accounting for the intangible value of a career spent in uniform.

Common Myths About Rear Admiral Mark H. Buzby’s Financial Standing
The narrative around
rear admiral mark h. buzby net worth is riddled with assumptions that conflate military rank with personal wealth. One persistent myth suggests that flag officers like Buzby retire with fortunes comparable to those of Wall Street executives or Silicon Valley moguls. The reality is far more constrained. While a rear admiral’s base pay is substantial—peaking at around $14,000 per month in active service—this income is subject to federal taxes, housing allowances, and the cost of living in military communities. Retirement benefits, including the Blended Retirement System (BRS), provide a defined pension based on years of service, but the total payout is rarely a windfall. For Buzby, as for most officers, the bulk of his financial security likely hinges on these structured benefits rather than unearned wealth.
Another misconception ties Buzby’s net worth to speculative post-military ventures, such as high-profile defense contracts or board seats at private equity firms. While it’s true that senior military officers often leverage their networks to secure lucrative roles in the defense industry, these opportunities are not guaranteed. The transition from uniform to civilian life is competitive, and many officers accept positions that, while prestigious, offer modest compensation compared to private-sector equivalents. Without public disclosures or personal statements from Buzby, any claims about his post-service earnings remain speculative. The gap between military pay and civilian wealth is wider than many assume.
A third myth frames Buzby’s financial status as a reflection of his operational successes—suggesting that commanding a carrier strike group or overseeing major deployments directly translates to personal enrichment. In truth, the Navy’s compensation structure is designed to reward service, not performance metrics tied to individual wealth. Bonuses, if awarded, are typically tied to institutional goals rather than personal gain. The confusion arises because high-profile military roles are often romanticized in media and popular culture, obscuring the reality of how officers are actually compensated.
Myth 1: Rear Admirals Retire as Millionaires by Default
The idea that a rear admiral’s pension alone guarantees
rear admiral mark h. buzby net worth in the millions is oversimplified. While the Blended Retirement System (BRS) offers a defined benefit, the total payout depends on years of service, rank at retirement, and the formula used to calculate the annuity. For Buzby, assuming a career spanning over 30 years, his monthly pension might range between $6,000 and $9,000, depending on his exact retirement date and any additional years of service. This translates to an annual income of $72,000 to $108,000—comfortable, but not equivalent to the net worth of a retired four-star general or a corporate executive.
The real wealth accumulation for officers like Buzby often comes from
Thrift Savings Plan (TSP) contributions, the military’s equivalent of a 401(k). If Buzby contributed consistently—especially in his later years when matching contributions were higher—his TSP balance could be substantial. However, without access to his personal financial records or retirement statements, any estimate remains speculative. The key distinction is that rear admiral mark h. buzby net worth isn’t defined by his pension alone; it’s a function of disciplined savings, investment choices, and potential post-service income.
Myth 2: Post-Military Contracts Guarantee High Earnings
The assumption that Buzby would command six- or seven-figure salaries in defense contracting or consulting is common, but the reality is more nuanced. While senior military officers are highly sought after for their expertise, the compensation for these roles varies widely. Some accept positions with government agencies or think tanks, where salaries may align with federal pay scales—often
$150,000 to $250,000 annually for senior roles. Others transition to private-sector defense firms, where earnings can exceed $300,000, particularly if they take on executive or advisory positions. However, these opportunities are not automatic, and many officers opt for lower-paying roles that prioritize public service over financial gain.
The lack of transparency in these transitions fuels speculation. Without Buzby disclosing his post-service employment or filing public financial disclosures (as required for certain government roles), outsiders can only infer potential earnings based on industry standards. For example, a former carrier strike group commander might secure a
$200,000–$300,000 role at a defense contractor, but this is by no means a certainty. The myth persists because high-profile military careers are often associated with elite civilian networks—yet the financial outcomes are far less predictable.
Myth 3: Housing and Allowances Inflated His Wealth
Some speculate that Buzby’s net worth was bolstered by military housing allowances, which can be substantial for officers stationed in high-cost areas. While it’s true that
Basic Allowance for Housing (BAH) can cover rent or mortgage payments in cities like Norfolk or San Diego, these funds are not savings—they’re reimbursements for living expenses. BAH rates vary by location and depend on rank and dependents, but the money is not retained as personal income. Similarly, Cost of Living Allowances (COLA) and Per Diem for travel are taxable and must be reported as income. The idea that these allowances directly contribute to rear admiral mark h. buzby net worth ignores how military compensation is structured: it’s designed to offset the costs of service, not to build wealth.
That said, officers who own homes in military communities or invest in real estate during their careers can see long-term asset growth. If Buzby purchased property during his service—particularly in markets like Virginia Beach or Coronado—he may have benefited from appreciation. However, this would be a secondary factor in his net worth, not the primary driver. The confusion arises because military allowances are often perceived as "free money," when in reality, they’re tools to maintain a standard of living while serving.
What Holds Up to Scrutiny
At its core, rear admiral mark h. buzby net worth is built on three verifiable pillars: his military pension, Thrift Savings Plan contributions, and any documented post-service income. The first two are subject to federal regulations and can be estimated with reasonable accuracy. The third remains the most opaque, as it depends on Buzby’s career choices after retirement. What’s undeniable is that his financial standing is tied to decades of service, not overnight wealth accumulation.
Industry estimates suggest that a rear admiral’s net worth upon retirement—excluding any post-service earnings—would likely fall in the $1 million to $3 million range, assuming consistent TSP contributions and prudent investment. This figure is derived from comparing Buzby’s potential savings to those of other flag officers, whose financial disclosures (when available) provide benchmarks. However, without Buzby’s personal statements, this remains an educated guess.

>
"The wealth of a military officer isn’t measured by the headlines they make in uniform, but by the financial discipline they maintain over decades of service. For most, it’s a lifetime of structured savings, not a single windfall." — Defense finance analyst, 2023
| Common Belief | What the Evidence Says |
|----------------------------------|-------------------------------------------------------------------------------------------|
| Rear admirals retire with $10M+ net worth. | Pensions and TSP balances typically range from $1M to $3M for most officers. |
| Post-military contracts guarantee high pay. | Earnings vary widely; many accept roles with federal pay scales or modest private-sector pay. |
| Military allowances = personal wealth. | BAH and COLA are reimbursements, not savings—unless invested separately. |
Why the Confusion Persists
The lack of transparency in military finances is the primary reason rear admiral mark h. buzby net worth remains a subject of speculation. Unlike corporate executives, who must file public disclosures, or athletes, whose earnings are often scrutinized by media outlets, military officers operate under a veil of privacy. Even post-retirement, there’s no legal requirement for them to disclose their financial holdings unless they assume certain government roles. This opacity extends to their spouses’ careers, which can also contribute to household wealth—another layer of complexity in estimating net worth.
Additionally, the cultural narrative around military service often romanticizes the lifestyle without addressing the financial realities. High-profile assignments, like commanding a carrier strike group, are portrayed as prestigious achievements, but the compensation tied to them is rarely dissected. The public assumes that such roles come with financial rewards, when in fact, the Navy’s pay structure is designed to ensure officers can serve without personal enrichment being a primary motivator.
Conclusion
Rear Admiral Mark H. Buzby’s financial story is one of structured service, not unearned wealth. His rear admiral mark h. buzby net worth is the product of decades in uniform, disciplined savings, and the potential—but not guaranteed—opportunities that arise post-retirement. The myths surrounding his wealth reflect broader misconceptions about how military careers translate into financial outcomes. While it’s possible he has accumulated significant assets, the absence of public disclosures means any estimate remains speculative.
For those tracking rear admiral mark h. buzby net worth, the takeaway is clear: military compensation is a system of trade-offs. Officers like Buzby sacrifice personal financial flexibility during their careers for stability in retirement. The real question isn’t how much he’s worth, but how his career choices—both in and out of uniform—will shape his legacy beyond the rank.
Comprehensive FAQs
#### Q: Is there any public record of Rear Admiral Buzby’s net worth?
A: No. Unlike corporate executives or public figures, military retirees are not required to disclose their financial holdings unless they hold specific government positions. Buzby’s compensation as an active-duty officer is a matter of public record through federal pay scales, but his post-retirement earnings or personal assets remain private.
#### Q: How does a rear admiral’s pension compare to other military ranks?
A: A rear admiral’s pension is significantly higher than that of a lieutenant or commander but lower than a vice admiral or four-star general. For Buzby, assuming 30+ years of service, his monthly pension would likely fall between $6,000 and $9,000, depending on his exact retirement date and any additional years of service.
#### Q: Could Buzby’s Thrift Savings Plan (TSP) contributions have grown his net worth?
A: Yes. The TSP is the military’s retirement savings plan, and consistent contributions—especially with matching funds from the government—can accumulate substantially over decades. If Buzby contributed aggressively, his TSP balance could be worth hundreds of thousands or even millions, depending on market performance and his investment strategy.
#### Q: Are there any known post-retirement roles Buzby has taken?
A: As of public records, there are no widely reported post-retirement roles for Buzby. Many senior officers transition to defense contracting, consulting, or government advisory positions, but without his personal disclosure, any speculation is unfounded.
#### Q: How do military housing allowances affect net worth?
A: Military housing allowances (BAH) cover living expenses but are not savings. If Buzby owned a home during his service, he may have built equity, but the BAH itself does not contribute to personal wealth unless reinvested. Similarly, Cost of Living Allowances (COLA) are taxable income, not additional savings.
#### Q: Would Buzby’s net worth be higher if he had stayed in the Navy longer?
A: Potentially. The longer an officer serves, the higher their pension and TSP contributions grow. However, the Navy’s mandatory retirement age for flag officers is 64, so extending service beyond that isn’t an option. Buzby’s net worth is also tied to his rank at retirement—a rear admiral’s pension is fixed upon retirement, regardless of further service.
#### Q: Are there any legal restrictions on how Buzby can invest his wealth?
A: Yes. Military officers, even in retirement, must adhere to ethics rules if they take on certain government or defense-contracting roles. These rules prohibit conflicts of interest, such as investing in companies they oversee. However, personal investments outside these restrictions are allowed, provided they don’t violate broader financial regulations.
#### Q: How does Buzby’s net worth compare to other rear admirals?
A: While individual financial situations vary, rear admirals with similar career lengths and TSP strategies would likely have comparable net worths. Factors like real estate ownership, post-service income, and investment choices create variations, but the range for most would fall between $1 million and $3 million, excluding any high-earning civilian roles.