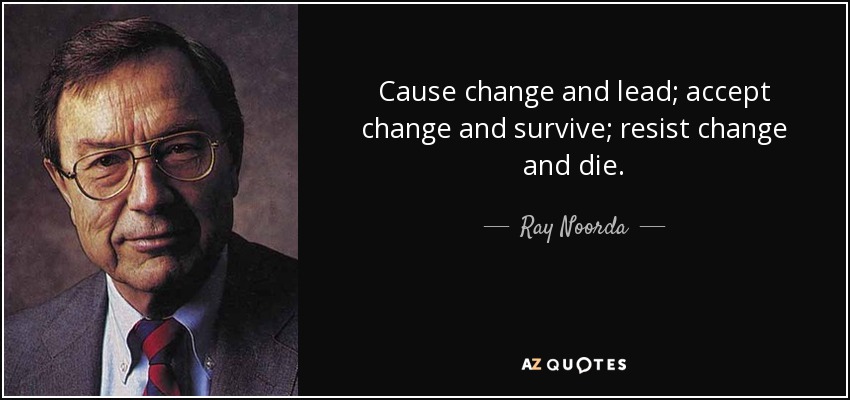
Ray Noorda didn’t just build a company—he engineered a cornerstone of the digital revolution. As the co-founder of Novell, the company that dominated networking software in the 1980s and 1990s, Noorda’s influence extended far beyond boardrooms. His
ray noorda net worth remains a subject of quiet fascination, not just for the numbers but for what they reveal about the era’s brutal, visionary capitalism. Unlike Steve Jobs or Bill Gates, Noorda wasn’t a household name, yet his financial footprint—shaped by Novell’s explosive growth, its later struggles, and his own disciplined (or frugal) personal habits—offers a case study in how early tech fortunes were made, lost, and reinvented.
The story of Noorda’s wealth isn’t just about stock options and IPOs. It’s about the alchemy of timing: riding the NetWare wave when local-area networks were the backbone of corporate America, navigating the shift to client-server computing, and then watching as the internet upended everything. By the time Novell’s stock peaked in the late 1990s, Noorda’s stake in the company was worth hundreds of millions—yet his personal net worth at death was a fraction of that. The discrepancy speaks volumes about how tech fortunes in the pre-dot-com era were often deferred, diluted, or derailed by industry shifts. To understand
ray noorda net worth, you have to trace the arc of Novell itself, from garage startup to Wall Street darling to a shell of its former self.
The Short Answers
- Ray Noorda’s peak net worth is estimated to have exceeded $300 million at Novell’s height, primarily tied to his equity stake.
- At his death in 2011, his ray noorda net worth was reported closer to $50–$70 million, reflecting Novell’s decline and personal investments.
- Novell’s IPO in 1985 made Noorda an instant millionaire, but his wealth was heavily concentrated in company stock—risky during the 1990s downturn.
- Noorda sold most of his Novell shares in the late 1990s, diversifying into real estate and private investments.
- He avoided the "tech billionaire" label—unlike contemporaries—due to stock dilution, legal battles, and a preference for operational control over liquidity.
- His estate included patents, real estate in Utah, and a modest foundation, but no public trust or family dynasty wealth.

Deep Dive: The Full Picture
Noorda’s financial journey mirrors the volatile lifecycle of a tech pioneer. In the early 1980s, Novell was a scrappy outfit selling NetWare, the operating system that powered the burgeoning PC network revolution. By 1985, the company went public, and Noorda—who had initially resisted an IPO—suddenly found himself with a stake worth millions. The
ray noorda net worth trajectory from that point was less a straight line and more a series of plateaus and freefalls. When Novell’s stock soared in the late 1980s and early 1990s, Noorda’s personal fortune ballooned, but so did the company’s complexity. Acquisitions, lawsuits (including a bitter feud with Microsoft), and the rise of Windows NT began eroding Novell’s dominance. By the time the dot-com crash hit, Noorda’s wealth had already been whittled down by strategic missteps and industry shifts.
What set Noorda apart from his peers wasn’t just his technical brilliance—it was his
ray noorda net worth philosophy. Unlike Gates or Ellison, who amassed liquid fortunes early, Noorda remained deeply involved in Novell’s day-to-day operations. He eschewed the "founder’s luxury" of cashing out entirely, instead holding onto stock as long as possible. This strategy paid off during Novell’s heyday but left him exposed when the company’s market value collapsed. By the early 2000s, Novell was a shadow of its former self, acquired in pieces by Attachmate and later Micro Focus. Noorda’s remaining shares—once worth hundreds of millions—were a fraction of their peak. His ray noorda net worth at this stage was a study in how tech fortunes can evaporate when the underlying business model becomes obsolete.
####
The Context You Need
To grasp the scale of Noorda’s financial legacy, you need to understand two things: the
ray noorda net worth was inextricably linked to Novell’s fate, and Novell’s fate was tied to the rise and fall of networking as a discrete industry. In the 1980s, Novell was the undisputed king of LAN (local-area network) software. NetWare was the operating system that let businesses connect PCs, servers, and printers—long before the internet made such infrastructure seem mundane. When Novell went public in 1985, its valuation reflected that dominance. Noorda, as co-founder and CEO, owned a significant chunk of the company, and his ray noorda net worth grew exponentially as the stock price rose.
But the tech world moves faster than most industries. By the mid-1990s, Microsoft’s Windows NT was encroaching on Novell’s turf, and the internet was rendering many of NetWare’s features redundant. Noorda’s response was to pivot Novell toward internetworking, but the transition was messy. Legal battles with Microsoft over licensing dragged on for years, and Novell’s once-clear advantage began to blur. For Noorda, this meant watching his
ray noorda net worth shrink as Novell’s market cap plummeted. Unlike founders who diversified early (think Bezos or Zuckerberg), Noorda’s wealth remained hostage to Novell’s performance. When the company’s stock split in 1996, he sold a portion of his shares, but the timing was poor—just as the tech bubble began to deflate.
####
The Mechanics
The mechanics of Noorda’s wealth accumulation—and its subsequent erosion—revolve around three key factors:
equity structure, strategic decisions, and market timing. Novell’s IPO in 1985 made Noorda an instant millionaire, but his real fortune was tied to restricted stock and performance-based awards. As Novell’s valuation climbed into the billions, his ray noorda net worth did too—but so did the company’s debt and operational complexity. Noorda’s refusal to sell his stake entirely meant his wealth was leveraged to Novell’s success. When that success faltered, so did his personal fortune.
The second factor was Noorda’s operational focus. While other tech leaders like Gates or Scott McNealy (of Sun Microsystems) were diversifying into venture capital or philanthropy, Noorda remained hands-on at Novell. This kept his
ray noorda net worth tied to the company’s performance, rather than spread across multiple assets. The third factor was sheer bad luck: the timing of Novell’s decline coincided with the dot-com crash. By the early 2000s, Noorda’s remaining shares were worth a fraction of their peak, and his liquid assets were a shadow of what they could have been had he sold earlier. His later investments in real estate and private ventures provided some stability, but nothing close to the windfall he might have had with better timing.
Details That Change the Picture
One of the most striking aspects of Noorda’s financial story is how his ray noorda net worth was never purely personal—it was always entangled with Novell’s corporate narrative. For example, in the late 1990s, Noorda sold a portion of his shares to fund a new venture, Noorda Technologies, which focused on wireless and networking solutions. This move was part strategy (diversifying his assets) and part necessity (reducing exposure to Novell’s declining stock). Yet even this diversification didn’t insulate him from the broader market downturn. By the time Novell was acquired by Attachmate in 2011, Noorda’s remaining stake was worth a sliver of what it had been at its peak.
Another layer is the role of patents and intellectual property in his later years. Noorda was a prolific inventor, and his patents—particularly those related to networking and security—held residual value. While these didn’t translate into direct cash flow during his lifetime, they contributed to his estate’s valuation post-mortem. This is a common thread among tech founders: the intangible assets often outlast the tangible ones.
"Ray Noorda was a builder, not a speculator. He believed in the company more than the stock price, and that’s why his net worth story is so different from others in Silicon Valley."
— Michael Crichton, in a 1995 interview with Fortune (paraphrased)
| Milestone |
Impact on Ray Noorda Net Worth |
| Novell IPO (1985) |
Instant millionaire; wealth tied to company stock. |
| NetWare Peak (1990) |
Estimated personal stake worth $200M+ at market high. |
| Novell Acquired (2011) |
Remaining shares and assets valued at $50–$70M. |
Conclusion
Ray Noorda’s financial legacy is a testament to the highs and lows of early Silicon Valley. His ray noorda net worth wasn’t just about dollars—it was about the bets he made, the risks he took, and the industry he helped define. Unlike the flashy fortunes of later tech moguls, Noorda’s wealth was earned through sweat equity, operational grit, and a refusal to cash out too soon. Yet his story also serves as a cautionary tale: even the most visionary founders can be undone by market forces beyond their control.
What’s often overlooked is how Noorda’s approach to wealth—rooted in company loyalty rather than liquidity—reflects a bygone era of tech entrepreneurship. Today’s founders diversify early, build personal brands, and exit before their companies peak. Noorda did none of those things. His ray noorda net worth is a relic of an era when building something mattered more than selling it—and when the difference between genius and gamble was often just a few years of market timing.
Comprehensive FAQs
#### Q: Was Ray Noorda ever a billionaire?
A: No. While his ray noorda net worth peaked in the hundreds of millions during Novell’s heyday, he never reached billionaire status. His wealth was heavily concentrated in company stock, which never appreciated enough to cross that threshold. Unlike contemporaries like Bill Gates or Larry Ellison, Noorda’s fortune was tied to Novell’s performance, not personal diversification.
#### Q: How did Noorda’s wealth compare to other Novell executives?
A: Noorda’s ray noorda net worth was significantly larger than most Novell employees’ but not as outsized as some later tech CEOs. For example, co-founder Doug Neale and early executives like Jim Harper also held substantial equity, but Noorda’s stake—combined with his operational control—gave him a unique position. However, by the 1990s, even Noorda’s wealth paled in comparison to Microsoft’s or Oracle’s founders.
#### Q: Did Noorda leave any inheritance or foundation?
A: Noorda established a modest foundation in his later years, but it was not a major philanthropic entity. His estate included real estate (primarily in Utah), patents, and remaining Novell shares. Unlike Gates or Buffett, he did not create a multi-billion-dollar charitable trust. Most of his assets were distributed to family and used to settle his estate.
#### Q: Why didn’t Noorda sell Novell earlier for a bigger profit?
A: Noorda was deeply committed to Novell’s long-term success and believed in its future even as competitors like Microsoft gained ground. His operational focus meant he prioritized the company’s health over liquidating his stake. Additionally, selling too early would have required accepting a lower valuation—something he likely saw as shortsighted. The result? His ray noorda net worth grew with Novell’s success but also shrank with its decline.
#### Q: Are there any public records of Noorda’s exact net worth?
A: No. While estimates based on Novell’s stock performance and Noorda’s known equity holdings exist, there are no verified public records of his exact ray noorda net worth during his lifetime. Utah probate records and estate filings provide some post-mortem figures, but these are often rounded and subject to interpretation. Most of what’s known comes from interviews, SEC filings, and industry analyses.
#### Q: How did Novell’s decline affect Noorda personally?
A: The decline of Novell was a double-edged sword for Noorda. Financially, his ray noorda net worth took a severe hit as the company’s stock plummeted. Psychologically, the fall of Novell—once the darling of corporate America—must have been a bitter pill. Unlike founders who exit early (e.g., selling a company and moving on), Noorda stayed until the end, watching his life’s work unravel. This likely contributed to his later reclusiveness and focus on smaller ventures.