Where It All Began
Radiology’s financial ascent mirrors its technological evolution. In the 1970s, when CT scanners first rolled into hospitals, radiologists were the gatekeepers of a new diagnostic frontier. Their expertise wasn’t just medical—it was technical, requiring mastery of machines that cost millions and produced images worth interpreting. Early adopters of these technologies found themselves in a unique position: their skills were scarce, and the demand for their services was rising faster than supply. Hospitals and private clinics scrambled to hire them, offering salaries that reflected their critical role. By the 1980s, radiology net worth for those in academic or high-volume practices began to diverge sharply from other specialties. A radiologist in a major city could earn 20–30% more than a family physician, a gap that would only widen. The financial foundation was laid not just by higher paychecks, but by the structure of radiology itself. Unlike surgeons or primary care doctors, radiologists often worked in groups—interpretation is a solitary task, but the business of running a department or private practice requires collaboration. This led to the rise of radiology groups, where multiple physicians pooled resources to buy equipment, negotiate contracts, and share profits. The model was simple: more volume meant more revenue, and the radiology net worth of early group founders grew exponentially as they reinvested earnings into additional scanners, MRI machines, and even real estate. By the 1990s, some of these groups had become regional powerhouses, their financial health tied to the same market forces that drove hospital mergers and insurance reimbursement rates.The Early Signs
The first cracks in the facade appeared in the late 1990s, when managed care began squeezing hospital budgets. Radiologists, who had long enjoyed autonomy, suddenly found themselves negotiating with insurers over reimbursement rates. The shift from fee-for-service to value-based care didn’t just affect their income—it forced them to think like business owners. Those who resisted the change saw their radiology net worth stagnate, while early adopters who embraced practice management or tele-radiology saw their financial trajectories accelerate. The lesson was clear: radiology wasn’t just a medical specialty anymore. It was a business. At the same time, the rise of teleradiology—where images were read remotely—created a new tier of financial opportunity. Companies like Radiology Partners and later, private equity-backed firms, began acquiring radiology practices en masse. For radiologists, this meant two paths: sell their practice for a lump sum (often a multiple of annual revenue) and walk away with a radiology net worth windfall, or stay on as employees, trading ownership for stability. The choice wasn’t just financial; it was philosophical. Some saw the sales as a betrayal of their calling, while others viewed them as a shrewd exit strategy in an industry where burnout rates were climbing.The Turning Point
The real inflection point came in the 2010s, when private equity firms turned radiology into a high-stakes investment class. Firms like Oak Hill Capital and Bain & Company began acquiring radiology groups not just for their revenue streams, but for their radiology net worth potential—speculating that consolidation would drive up profits. The strategy worked, at least initially. By 2015, the average sale price for a radiology practice had surged, with some deals fetching 8–10 times annual earnings. Radiologists who had spent decades building their practices suddenly found themselves in the crosshairs of Wall Street, offered life-changing sums for their equity. The shift had unintended consequences. As private equity firms tightened their grip, independent radiology groups became rarer. Many radiologists, now employees rather than owners, saw their salaries rise—but so did their overhead. The radiology net worth of the new generation of radiologists became more volatile, tied to the whims of corporate balance sheets rather than the steady cash flow of a self-owned practice. Meanwhile, those who had sold out early found their windfalls evaporating as the market corrected, a reminder that even in radiology, wealth isn’t permanent."We used to think we were just doctors. Then we realized we were sitting on assets. The question wasn’t whether to sell—it was when." — Dr. Michael Chen, former radiology group founder (anonymized for privacy)
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1980s–1990s |
|
| 2000s |
|
| 2010s–Present |
|
Lessons From the Journey
- Ownership matters more than ever. Radiologists who retained equity in their practices saw radiology net worth grow faster than those who sold early.
- Location is still king—but not in the way you think. Urban practices command higher sale prices, but rural radiologists often earn more per hour due to lower overhead.
- Specialization pays. Subspecialties like interventional radiology or cardiac imaging yield higher reimbursements and faster wealth accumulation.
- Timing is critical. Selling a practice during a private equity frenzy can mean a windfall—but it can also lock in future financial constraints.
- The business of medicine is now inseparable from the medicine itself. Radiologists who treat their career as a financial asset outperform those who see it purely as a vocation.
Where Things Stand Today
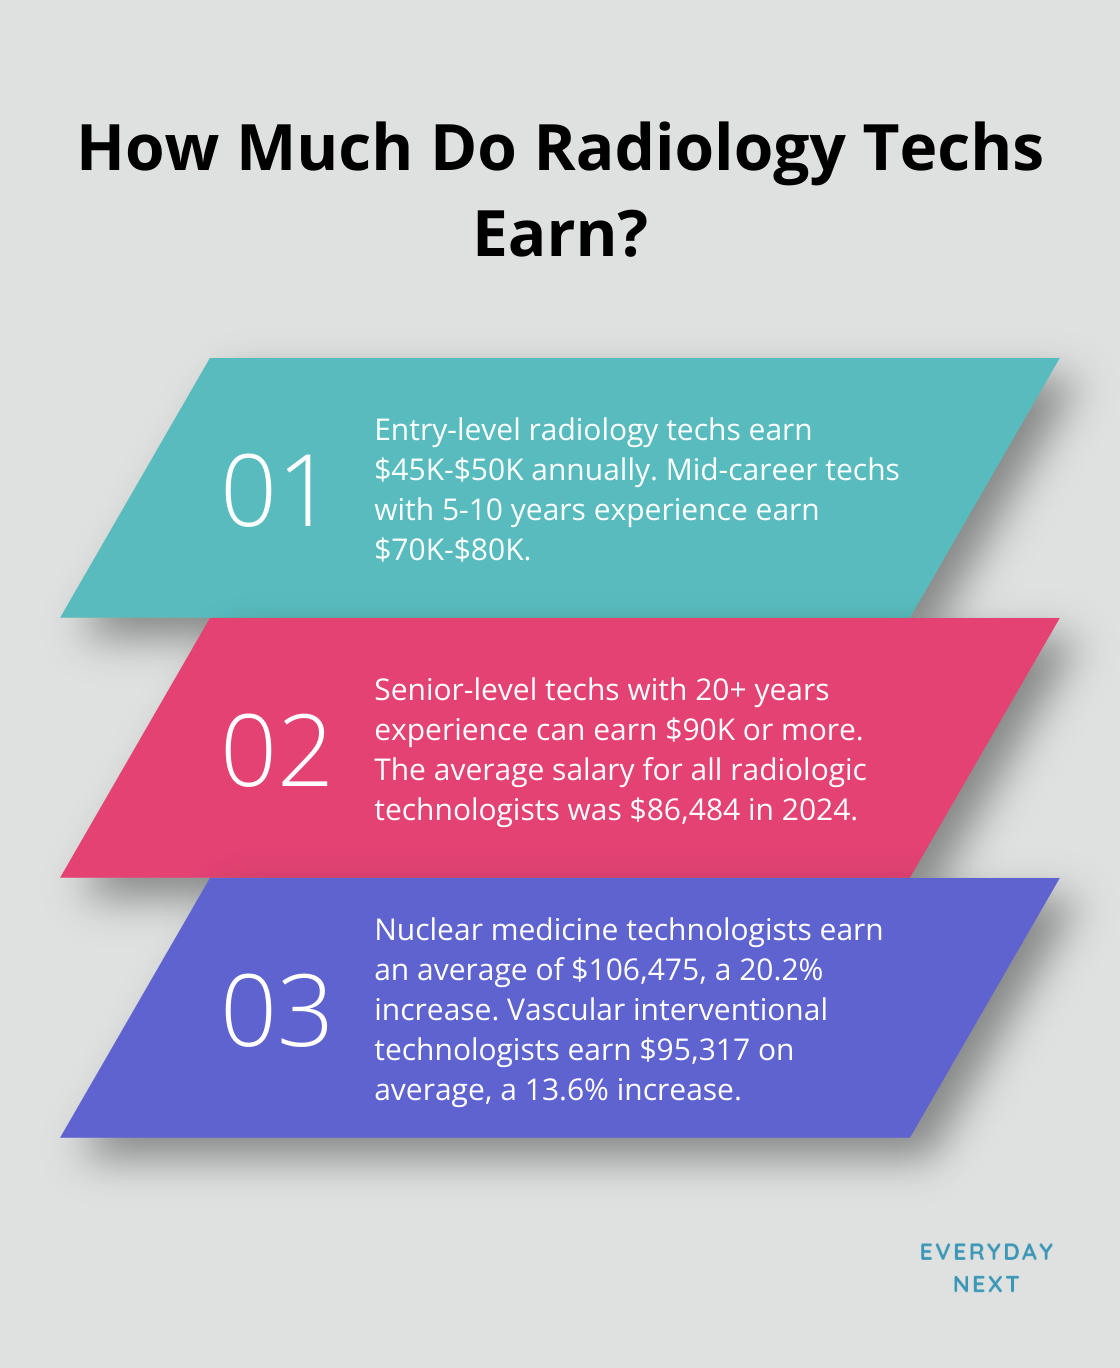
Today, the radiology net worth landscape is a study in contrasts. At the top, a handful of radiologists—those who sold their practices at peak valuations or who work in high-margin subspecialties—enjoy financial security that borders on the luxurious. Their portfolios may include real estate, private investments, or even secondary careers in healthcare consulting. For them, radiology was never just a job; it was a vehicle for wealth creation. But the story isn’t uniform. Younger radiologists, saddled with student debt and entering a market dominated by corporate ownership, face a different reality. Their radiology net worth growth is slower, tied to the whims of hospital budgets and the unpredictable nature of employment contracts. Many are turning to side hustles—tele-radiology, AI-assisted diagnostics, or even content creation—to supplement their incomes. The result? A generational divide: the founders of radiology’s financial boom and the inheritors of its risks.
Conclusion
Radiology’s financial story is more than a tale of high salaries and lucrative exits. It’s a case study in how medicine and capitalism collide. The specialty’s radiology net worth trajectory reveals much about the broader healthcare economy: the rise of corporate medicine, the commodification of expertise, and the enduring tension between patient care and profit. For radiologists, the lesson is clear—financial success requires more than clinical skill. It demands an understanding of market forces, a willingness to embrace (or resist) consolidation, and the foresight to navigate an industry where the lines between doctor and investor are blurring. Yet for all its financial allure, radiology remains a field where the stakes are ultimately human. The same technologies that drive radiology net worth also shape patient outcomes. The challenge for the next generation will be to harness the financial opportunities of the specialty without losing sight of its core purpose: healing. The question isn’t whether radiologists can get rich—it’s whether they can do so without selling their soul.Comprehensive FAQs
Q: How does a radiologist’s salary compare to other medical specialties?
Radiologists consistently rank among the highest-earning physicians, with median salaries in the $400,000–$500,000 range for those in private practice or high-volume settings. However, radiology net worth varies widely—subspecialists like neuroradiologists or interventionalists can earn significantly more, while general radiologists in academic settings may see lower take-home pay due to research or teaching obligations. Compared to surgeons (who often earn more but face higher malpractice costs), radiologists benefit from lower liability risks and higher productivity per hour.
Q: Is it better to own a radiology practice or work as an employee?
Ownership historically yields higher radiology net worth over time, but it comes with risks. Practice owners bear the burden of equipment costs, staffing, and regulatory compliance, which can erode profits. Employees, meanwhile, enjoy stability but miss out on equity appreciation. The decision depends on risk tolerance: those who sell their practices at the right time can achieve financial independence, while employees may see slower but steadier wealth accumulation. Many radiologists now opt for hybrid models—owning a portion of a group or working part-time in private practice while consulting.
Q: How has private equity affected radiology’s financial landscape?
Private equity’s entry into radiology has compressed the timeline for wealth accumulation. Practices sold to PE firms often fetch 6–10 times annual earnings, providing radiologists with liquidity—but at the cost of long-term control. The downside? Consolidation has reduced competition, potentially driving up costs for patients and hospitals. Some radiologists now view PE-backed groups as "golden handcuffs," where the allure of a large exit check comes with strings attached, like mandatory stay clauses or profit-sharing structures that favor investors over physicians.
Q: What are the biggest threats to radiology’s financial future?
The most immediate threats are burnout (which reduces supply), AI disruption (which may automate routine readings), and further consolidation (which could limit negotiation power). Another wild card is reimbursement policy: if insurers continue to cut rates for imaging services, radiology net worth could stagnate unless radiologists pivot to higher-margin services like interventional procedures. Geopolitical factors—such as supply chain disruptions for medical equipment—also pose risks. The specialty’s financial resilience will depend on its ability to adapt to these challenges without losing its clinical edge.
Q: Can radiology still be a path to wealth in the next decade?
Yes, but the playbook is changing. Traditional routes—like owning a practice—remain viable, but radiologists will need to diversify. Subspecialization, international consulting, and even non-clinical roles (e.g., medical device innovation) are becoming critical. Those who leverage data analytics or AI to enhance their practice’s efficiency may see outsized returns. The key will be balancing financial strategy with the reality that radiology’s future depends on its ability to prove its value in an era of cost-conscious healthcare.
