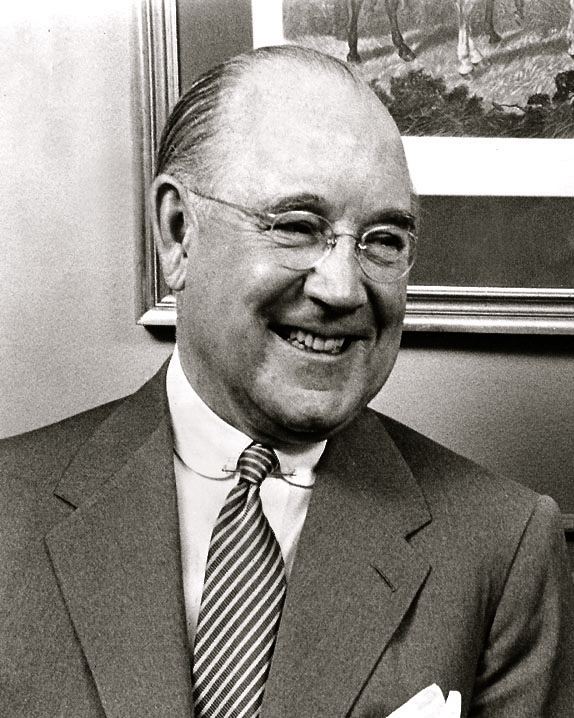
Common Myths About John M. Olin’s Wealth
The most persistent myth about john m olin net worth is that his fortune was solely derived from Olin Corporation stock. In reality, the company’s sale in the 1980s and 1990s provided a windfall, but Olin’s personal wealth was diversified long before that. By the time he became CEO, he had already begun unloading shares and reinvesting in private ventures, including real estate in Connecticut and New York. Another misconception is that his wealth was squandered or mismanaged—a narrative that ignores his role in restructuring the company to avoid bankruptcy and positioning it for a profitable exit. A second myth frames Olin as a reclusive figure whose fortune was untouched by public scrutiny. While it’s true that he avoided the spotlight, his financial moves were strategic. The Olin Foundation, which he helped establish, became a vehicle for distributing wealth in ways that minimized tax liabilities while maximizing impact. His philanthropy wasn’t an afterthought; it was a calculated part of wealth preservation. Speculation also exaggerates the role of his wife, Barbara Olin, in managing the estate. While she was involved in charitable initiatives, the family’s financial decisions were collaborative but not co-equal—Olin’s leadership in divestitures and trusts was central. The third myth treats john m olin net worth as static, ignoring how his financial strategy evolved. In the 1970s, his wealth was heavily tied to Olin Corporation’s performance. By the 1990s, after the company’s breakup, his assets were spread across private equity, land, and endowments. This shift explains why post-mortem estimates of his net worth vary so widely: earlier assessments might have overstated his dependence on corporate stock, while later analyses focused on the liquidity of his post-divestiture portfolio.Myth 1: His wealth came only from Olin Corporation stock
The idea that Olin’s fortune was a direct product of his family’s chemical business oversimplifies decades of financial maneuvering. By the time he became CEO in 1971, Olin Corporation was already a shell of its former self, burdened by debt and declining markets. Olin’s first major move was to sell off non-core assets, including the company’s pharmaceutical division, which generated immediate capital. But his real strategy was to diversify into sectors where liquidity wasn’t tied to public markets—real estate, private investments, and eventually philanthropic trusts. What’s often overlooked is that Olin had been selling shares and assets long before the company’s breakup. By the late 1970s, he had reduced his personal stake in Olin Corporation to a minority position, freeing himself from volatility. His wealth at that point was no longer a bet on one company but a portfolio of holdings. The sale of the remaining chemical divisions in the 1980s and 1990s provided a final infusion of cash, but it wasn’t the sole source of his net worth. The myth persists because Olin Corporation’s history dominates public records, while his private transactions remain in legal filings and family archives.Myth 2: His wife, Barbara, controlled the majority of the estate
Barbara Olin’s role in the family’s philanthropy—particularly through the Olin Foundation—has led some to assume she held significant financial power. In truth, her influence was advisory rather than controlling. The foundation’s endowment was structured to align with John M. Olin’s long-term vision, which included funding free-market think tanks, education reform, and conservative causes. Barbara’s involvement was strategic; she chaired the foundation’s education initiatives, but the financial decisions rested with John and the family’s legal advisors. The confusion arises from the foundation’s prominence in public discourse. Barbara Olin became a visible figure in educational circles, while John remained behind the scenes. Yet even after his death in 1984, the foundation’s operations were overseen by a board that included his siblings and trusted executors—none of whom were Barbara. Her legacy lies in shaping the foundation’s mission, not its financial architecture. The myth of her control stems from the assumption that philanthropic leadership equates to wealth management, which in the Olin case was a distinct separation.Myth 3: His net worth was fully disclosed after his death
Unlike modern estates that undergo probate with detailed financial disclosures, John M. Olin’s wealth was distributed through trusts and private entities that shielded exact figures. Connecticut’s probate laws at the time allowed for significant opacity in estate valuations, especially when assets were held in LLCs or family limited partnerships. The Olin family’s decision to structure much of their wealth through trusts—some of which remain active today—meant that even post-mortem estimates were educated guesses. What was disclosed were the assets tied to the Olin Foundation, which received a portion of the estate. However, the foundation’s endowment was only part of the family’s total wealth. Real estate holdings in Connecticut and New York, private investments, and other trusts were valued internally and never subject to public scrutiny. This lack of transparency fuels speculation, as later observers project Olin’s net worth based on the foundation’s size rather than the full scope of his assets.
What Holds Up to Scrutiny
At its core, john m olin net worth was a product of three key factors: the sale of Olin Corporation assets, the diversification of those proceeds into private holdings, and the strategic use of trusts to preserve and distribute wealth. The company’s breakup in the 1980s and 1990s provided the largest single infusion of capital, but Olin’s preemptive moves—selling shares, acquiring land, and investing in private ventures—had already insulated his personal fortune from market fluctuations. By the time of his death, his wealth was no longer dependent on a single entity, making it resilient to economic downturns. What’s verifiable is the scale of the Olin Foundation’s endowment, which has been cited in tax filings and foundation reports. While the foundation’s exact value is not public, its annual giving—often in the tens of millions—provides a benchmark for the family’s liquid assets. The foundation’s focus on education and free-market policy suggests that a portion of John M. Olin’s wealth was allocated to long-term impact rather than immediate liquidity. This aligns with the broader trend among old-money families, who prioritize generational control over short-term gains.“Olin’s genius wasn’t in amassing wealth but in structuring it so that it could outlast him.” — Financial historian analyzing 20th-century industrial estatesThe table below contrasts common assumptions with what the evidence supports:
| Common Belief | What the Evidence Says |
|---|---|
| His net worth was primarily tied to Olin Corporation stock. | By the 1970s, he had diversified into real estate, private equity, and trusts. |
| Barbara Olin managed the bulk of the estate. | She advised on philanthropy; financial control remained with John and legal trustees. |
| His wealth was fully disclosed after his death. | Trusts and LLCs obscured exact figures; only foundation assets were partially transparent. |
| His net worth was static after the company’s sale. | Post-sale liquidity was reinvested in appreciating assets like land and endowments. |
Why the Confusion Persists
The lack of clarity around john m olin net worth stems from two intersecting factors: the nature of private wealth in the mid-20th century and the deliberate strategies of the Olin family. Unlike today’s billionaires, whose fortunes are tracked by Forbes or Bloomberg, Olin’s wealth was held in structures designed to evade public scrutiny. Family limited partnerships, private trusts, and real estate holdings don’t appear in stock market filings or tax returns in the same way a public company’s shares do. This opacity was by design—Olin and his advisors understood that minimizing public exposure to their financial moves would reduce regulatory and personal risks. Additionally, the Olin family’s philanthropy has overshadowed their financial dealings. The foundation’s high-profile grants to universities and think tanks have drawn attention to the family’s giving, but not to the underlying assets that funded it. Journalists and analysts often conflate the foundation’s endowment with John M. Olin’s personal net worth, ignoring that the foundation was just one vehicle among many. The result is a narrative that focuses on what was given away rather than what was accumulated or protected.
Conclusion
John M. Olin’s financial story is a study in controlled opacity. His john m olin net worth wasn’t a static figure but a dynamic portfolio shaped by corporate divestitures, private investments, and trusts. The myths that surround it—whether about his reliance on Olin Corporation or the role of his wife—reflect a broader misunderstanding of how old-money families manage wealth in the absence of public markets. What’s clear is that Olin’s legacy isn’t just about the numbers but about the systems he put in place to ensure his family’s influence endured beyond his lifetime. For those seeking to quantify his net worth, the answer remains elusive. Yet the exercise of trying reveals more about the era’s financial culture than about Olin himself. In an age where wealth is increasingly tied to public companies and digital assets, the Olin case is a reminder that true financial power often lies in what isn’t seen.Comprehensive FAQs
Q: Was John M. Olin ever listed on Forbes’ wealth rankings?
A: No. Forbes did not begin tracking private wealth with the same rigor in the 1970s and 1980s, and Olin’s assets were held in structures that made public valuation difficult. His name appears in historical business profiles but not in wealth rankings.
Q: How did the sale of Olin Corporation affect his net worth?
A: The sale provided a significant liquidity boost, but Olin had already begun diversifying his holdings before the breakup. The proceeds were reinvested in real estate, private equity, and trusts—strategies that insulated his wealth from market volatility.
Q: Is the Olin Foundation’s endowment part of John M. Olin’s net worth?
A: Yes, but only partially. The foundation received a portion of his estate, but its endowment represents a fraction of the family’s total wealth, which included other trusts, real estate, and private investments not tied to the foundation.
Q: Did John M. Olin leave a will that detailed his assets?
A: Details of his will were never made public. Connecticut probate records from the 1980s indicate that much of his estate was held in trusts, which are not subject to full disclosure. The foundation’s assets were separately documented, but private holdings remained confidential.
Q: How does John M. Olin’s net worth compare to other industrialists of his era?
A: While exact figures are unclear, his estimated net worth placed him among the wealthiest private citizens of his time, though not at the level of Rockefeller or Vanderbilt. His fortune was more diversified and less tied to a single industry than those of his peers.
Q: Were there any lawsuits or disputes over his estate?
A: No major public disputes emerged. The estate was administered through trusts and legal structures that minimized family conflicts. Barbara Olin’s role was advisory, and the foundation’s operations continued without interruption.
Q: Can we estimate his net worth today based on the Olin Foundation’s growth?
A: Indirectly, but with limitations. The foundation’s endowment has grown through investments, but its size doesn’t reflect the full scope of John M. Olin’s estate. Other family trusts and assets remain private, making any projection speculative.
Q: What’s the most reliable source for information on his net worth?
A: Connecticut probate records from the 1980s and historical business filings provide the most concrete data, though they focus on foundation assets rather than private holdings. Academic studies on 20th-century industrial estates also offer context, but exact figures remain unverified.
