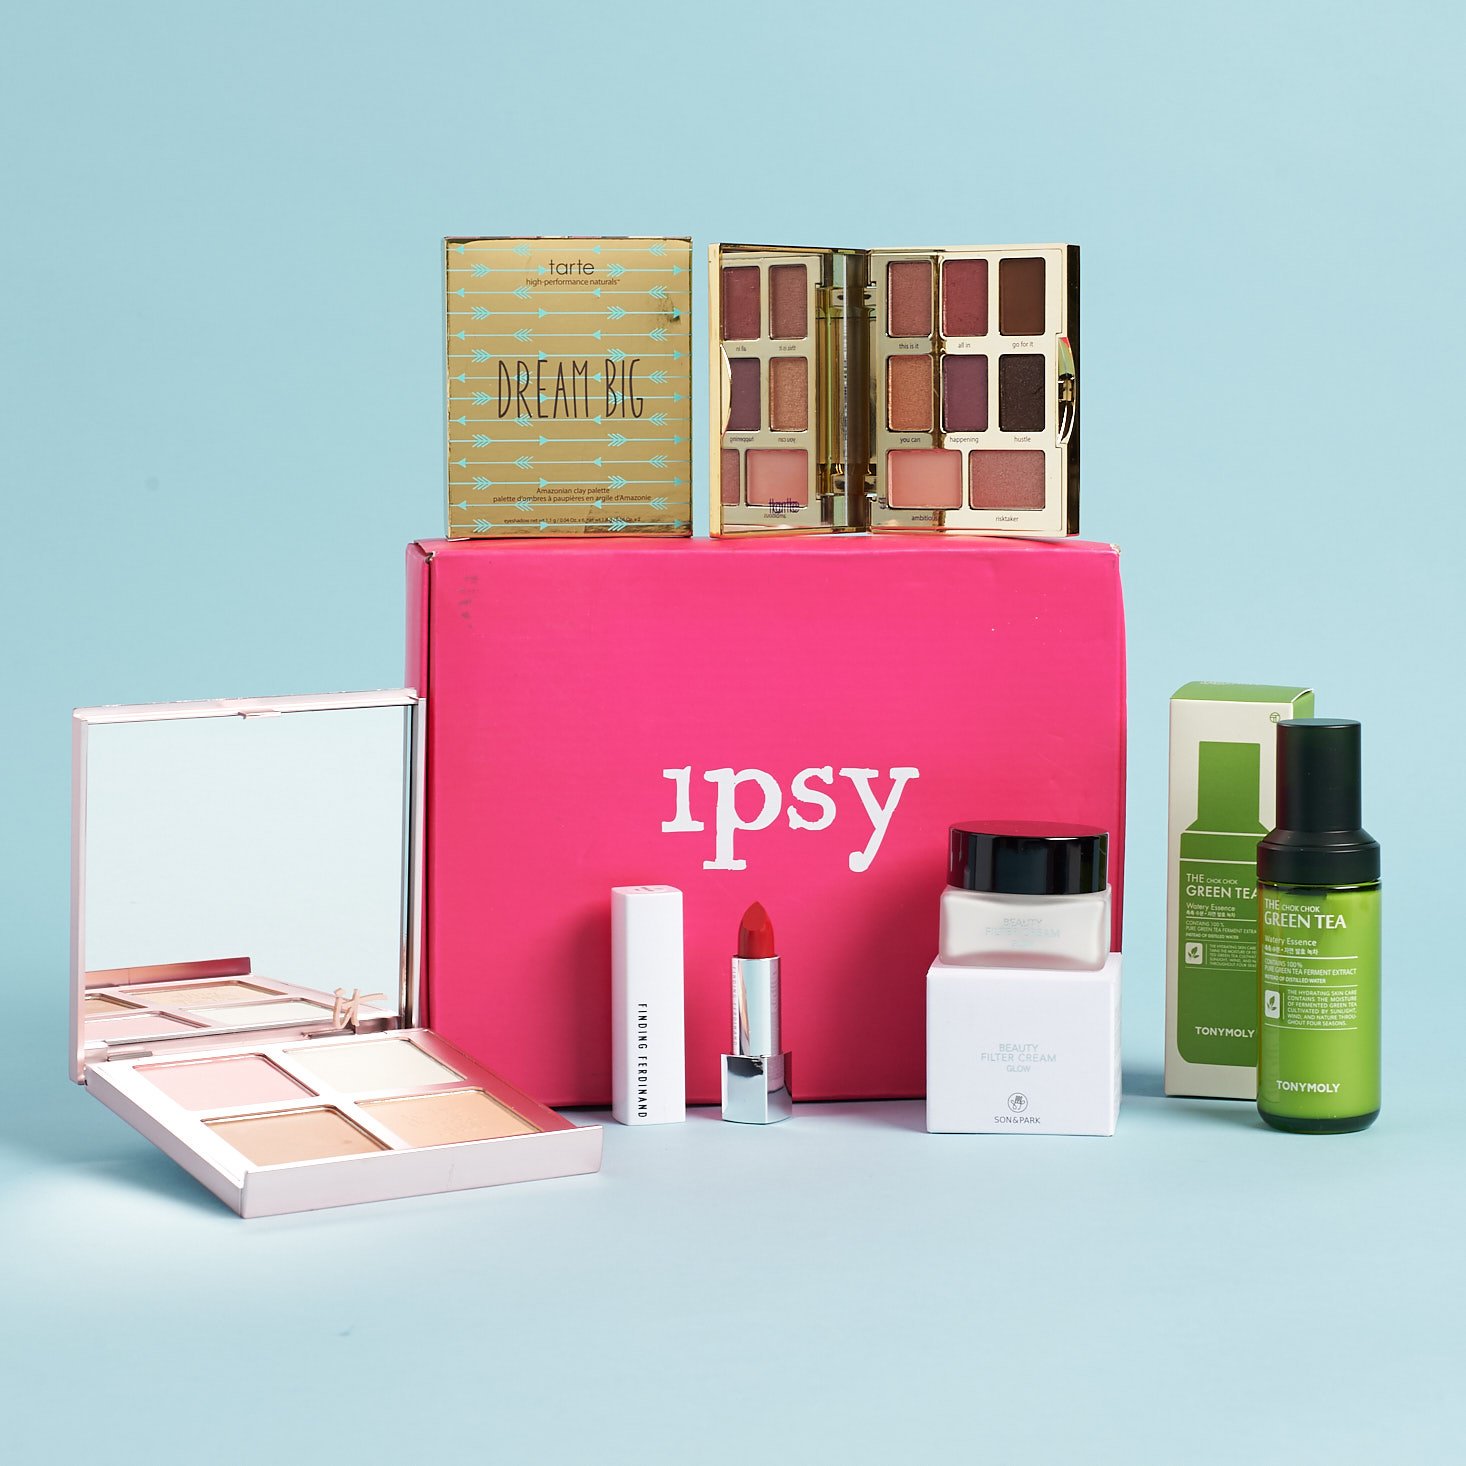
Where It All Began
Ipsy’s origin story reads like a Silicon Valley myth, but with a twist: the product was makeup, not code. Founded in 2011 by Andrew Goodman and Mark Leonard, the company emerged from the ashes of a failed venture capital firm, Goodman Ventures. The duo had noticed a gap in the beauty market—consumers wanted to try products before committing, but brick-and-mortar stores and even online retailers lacked a low-risk entry point. Their solution? A monthly subscription box delivering full-size samples of new releases, paired with discounts on full-priced items. The model was simple, but the execution required something rare in retail: trust. Early adopters weren’t just buying a box; they were betting on Ipsy’s ability to curate products they’d actually use. The early signs of what would become a multi-million-dollar enterprise were subtle. By 2012, Ipsy had secured a $10 million Series A led by Bessemer Venture Partners, a firm known for backing disruptive tech plays like Uber and Airbnb. The investment wasn’t just about the boxes—it was about the data. Ipsy’s proprietary algorithm analyzed customer feedback, return rates, and social media chatter to refine its selections. This wasn’t just a beauty subscription; it was a behavioral lab. The company’s first major breakthrough came when it partnered with Sephora, allowing customers to purchase full-size versions of Ipsy samples in-store. Suddenly, the samples weren’t just a hook—they were a bridge to higher-margin sales.The Early Signs
The real inflection point arrived in 2013, when Ipsy introduced its "Ipsy Beauty Box"—a premium-tier subscription priced at $30 a month, offering higher-end brands like MAC, Too Faced, and Smashbox. This wasn’t just an upsell; it was a strategic repositioning. The company had realized that its core audience wasn’t just bargain hunters. They were beauty enthusiasts willing to pay for convenience and exclusivity. The move paid off: by the end of 2013, Ipsy’s revenue had surged to $50 million, and it was profitable for the first time. Analysts at the time noted that Ipsy’s customer acquisition cost (CAC) was among the lowest in e-commerce, thanks to word-of-mouth referrals and viral social media campaigns. Yet, the company’s growth wasn’t without controversy. Critics argued that Ipsy’s model relied too heavily on impulse purchases—customers often bought full-size products on a whim after receiving samples, only to regret it later. Return rates for full-priced items hovered around 20%, a figure that raised eyebrows in an industry where returns typically exceeded 30%. But Ipsy’s leadership saw this as a feature, not a bug. The data confirmed that customers who purchased full sizes were three times more likely to become repeat buyers. The company doubled down on this insight, refining its algorithm to predict which samples would drive the most conversions. By 2014, Ipsy had expanded beyond the U.S., launching in the UK and Canada, further diversifying its revenue streams.The Turning Point
The moment Ipsy’s financial trajectory shifted irrevocably came in 2015, when it secured a $75 million investment from L Brands, the parent company of Victoria’s Secret and Bath & Body Works. The deal valued Ipsy at $1 billion, making it one of the most valuable private beauty companies at the time. For L Brands, the acquisition was a bet on digital-native retail. While its legacy brands were struggling with declining mall traffic, Ipsy represented a new paradigm: direct-to-consumer, data-driven, and influencer-powered. The investment allowed Ipsy to accelerate its expansion, including the launch of Ipsy TV, a short-form video platform showcasing makeup tutorials—an early foray into what would later become TikTok’s dominant beauty niche. The acquisition also marked a shift in Ipsy’s business model. No longer just a subscription service, the company began selling full-size products directly on its website, cutting out middlemen like Sephora and Ulta. This move was risky: competing with retailers that had decades-long relationships with brands. But Ipsy’s data gave it an edge. It knew exactly which products resonated with its audience—and at what price. The result? By 2016, Ipsy’s direct sales accounted for 40% of its revenue, a figure that would continue to climb. The company’s gross merchandise value (GMV)—a key metric in retail—exceeded $500 million annually, a milestone that caught the attention of private equity firms eyeing an exit strategy."We’re not just selling products; we’re selling an experience—and that experience is powered by data." — Andrew Goodman, Ipsy Co-Founder (2016)

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2011–2012 |
|
| 2013–2014 |
|
| 2015–2017 |
|
Lessons From the Journey
- Data beats intuition. Ipsy’s ability to leverage customer behavior—not just sales data but social media sentiment and return patterns—allowed it to refine its offerings faster than competitors.
- Influencers are currency. Early partnerships with micro-influencers (5K–50K followers) proved more effective than celebrity endorsements, offering higher engagement at lower costs.
- Subscription fatigue is real. Ipsy’s pivot to direct sales mitigated churn by giving customers more control over purchases beyond the monthly box.
- Private equity is a double-edged sword. The L Brands investment provided capital but also pressured Ipsy to scale aggressively, leading to later missteps in international expansion.
- Brand loyalty is fragile. Despite its cult following, Ipsy struggled to retain customers post-purchase, with lifetime value (LTV) declining as competitors like FabFitFun and Birchbox entered the market.
- Regulation lurks. The rise of FTC guidelines on influencer disclosures forced Ipsy to overhaul its marketing partnerships, adding compliance costs.
Where Things Stand Today
As of 2024, Ipsy’s net worth remains a closely guarded figure, given its private status. However, industry estimates place its enterprise value in the $500 million to $1 billion range, depending on revenue multiples and debt levels. The company has undergone significant restructuring since its peak in 2016. In 2018, L Brands spun off Ipsy into a separate entity, L Brands Ventures, as part of a broader shift toward digital assets. This move allowed Ipsy to explore new revenue streams, including licensing its algorithm to other retailers and expanding into skincare and fragrance categories. Yet, the road hasn’t been smooth. The rise of DTC brands like Glossier and Rare Beauty forced Ipsy to rethink its positioning. While it still dominates the subscription box market, its market share has slipped as younger consumers gravitate toward TikTok-driven discovery over curated boxes. In response, Ipsy has doubled down on personalization, using AI to tailor boxes to individual preferences. It’s also experimented with limited-edition collaborations, such as partnerships with Kylie Cosmetics and Fenty Beauty, to stay relevant. Financially, the company remains profitable but operates in a highly competitive landscape, where margins are thin and customer acquisition costs continue to rise.Conclusion
Ipsy’s story is more than a tale of beauty and algorithms; it’s a masterclass in how data-driven retail can disrupt traditional industries. The company’s net worth trajectory mirrors the broader shift from physical retail to digital-first models, proving that samples, subscriptions, and social proof can build empires. Yet, its journey also serves as a cautionary tale about the pitfalls of over-reliance on private equity and the challenges of scaling too quickly. Today, Ipsy stands at a crossroads: it can either double down on its AI and influencer strengths or risk becoming another casualty of the DTC gold rush. What’s undeniable is that Ipsy rewrote the rules of beauty retail. Whether its net worth peaks at $1 billion or stabilizes at $500 million, its legacy lies in proving that convenience, personalization, and viral culture can outperform legacy brands. For entrepreneurs watching its path, the lesson is clear: disruption isn’t about the product—it’s about the data behind it.Comprehensive FAQs
Q: Is Ipsy publicly traded?
Ipsy has never gone public. As a private company, its financials are not disclosed to the public, though industry estimates and private equity filings provide occasional insights. Its parent entity, L Brands Ventures, occasionally releases high-level performance updates, but exact revenue or profit figures remain confidential.
Q: How much did L Brands pay to acquire Ipsy?
In 2015, L Brands invested $75 million in Ipsy as part of a strategic acquisition. At the time, this valuation placed Ipsy at $1 billion, though the exact terms of the deal—including equity stakes and earn-outs—were not publicly disclosed.
Q: What’s Ipsy’s biggest revenue driver today?
While its subscription boxes remain iconic, Ipsy’s largest revenue stream is now direct sales of full-size products through its website. The company has also diversified into licensing its tech to other retailers and limited-edition collaborations, which account for a growing share of its GMV.
Q: Has Ipsy ever filed for bankruptcy?
No, Ipsy has never filed for bankruptcy. However, it has undergone restructuring under L Brands Ventures, including cost-cutting measures and a shift toward higher-margin digital products. Financial stress points emerged in 2019–2020 due to supply chain disruptions and changing consumer habits, but the company avoided insolvency.
Q: How does Ipsy’s net worth compare to competitors like Birchbox or FabFitFun?
Ipsy’s estimated net worth ($500M–$1B) far exceeds that of Birchbox (reportedly valued at $100M–$300M) and FabFitFun (acquired for $200M in 2017). However, FabFitFun’s broader product range—including fitness gear—gives it a more diversified revenue base, while Birchbox’s focus on luxury skincare positions it as a niche player. Ipsy’s advantage lies in its scalable tech and influencer network, which competitors struggle to replicate.
Q: What’s the future outlook for Ipsy’s net worth?
Analysts predict modest growth for Ipsy’s net worth, contingent on its ability to monetize AI personalization and expand into adjacencies like wellness. Risks include increased competition from TikTok Shop and regulatory pressures on influencer marketing. A potential exit via acquisition remains a possibility, particularly if private equity firms see value in its data assets.
