The Complete Overview of Fortune Builders Net Worth
The study of fortune builders net worth reveals a paradox: wealth isn’t just a byproduct of success—it’s a system of reinforcement. Take Jeff Bezos, whose Amazon fortune ballooned from $0 to over $200 billion, but whose early years were defined by reinvesting every dollar back into the business. This cycle—sacrifice now, exponential return later—is the bedrock of high-net-worth trajectories. Yet for every Bezos, there are dozens of entrepreneurs who hit jackpot status only to see their fortunes evaporate through mismanagement or poor timing. The modern era has democratized access to wealth-building tools, but the outcomes remain starkly unequal. A 2023 Oxfam report highlighted that the richest 1% now control nearly half of global wealth, a concentration driven by asymmetric opportunities—private equity, venture capital, and inherited advantages. The question isn’t whether fortune builders net worth is growing; it’s how the rules of the game continue to favor those who already play them.Historical Background and Evolution
The concept of accumulated wealth as a measurable metric emerged in the 19th century, when industrialists like Andrew Carnegie and John D. Rockefeller first made their fortunes public. But the modern framework for tracking fortune builders net worth didn’t solidify until the mid-20th century, with the rise of Forbes’ annual rankings. These lists weren’t just vanity projects; they reflected a shift toward transparency as power. By quantifying wealth, the ultra-rich could signal stability to investors, creditors, and even governments—turning personal balance sheets into instruments of influence. The digital revolution accelerated this trend. The 1990s saw the first tech billionaires, while the 2010s introduced crypto and NFTs as speculative wealth multipliers. Today, fortune builders net worth is no longer static; it’s a dynamic variable influenced by algorithmic trading, AI-driven investments, and even meme-stock frenzies. The barrier to entry has lowered, but the asymmetry of outcomes remains as pronounced as ever. A 2022 study by Credit Suisse found that the top 1% of global wealth holders now hold 45.8% of total assets, up from 42.1% in 2000—a trend that suggests wealth concentration is accelerating, not slowing.Core Mechanisms: How It Works
At its core, fortune builders net worth is a function of three interlocking forces: income generation, asset appreciation, and tax efficiency. The most successful operators don’t just earn money—they engineer environments where capital compounds autonomously. Consider the case of a private equity firm like Blackstone, which leverages debt to amplify returns, or a family office like the Mercers, which deploys wealth across hedge funds, real estate, and even farmland. The result? A self-sustaining wealth machine that requires minimal active management. The mechanics vary by sector. In tech, equity dilution and IPOs are the primary drivers, while in traditional industries, dividend reinvestment plans (DRIPs) and share buybacks dominate. Even philanthropy plays a role: high-net-worth individuals often structure donations through charitable trusts, which can reduce taxable income while maintaining control over assets. The most sophisticated fortune builders net worth strategies blend these elements into a multi-layered portfolio, where no single asset represents more than 10-15% of total holdings—a classic risk-mitigation tactic.Key Benefits and Crucial Impact
The primary advantage of fortune builders net worth isn’t just the money—it’s the leverage it provides. A net worth of $1 billion doesn’t just buy yachts; it buys political access, exclusive networks, and the ability to shape industries. For example, a single donation from a high-net-worth individual can sway a presidential election, while a strategic investment can dictate the future of a city’s skyline. The impact isn’t limited to the personal; it ripples through economies, funding everything from space exploration to underground art scenes. Yet the benefits aren’t just external. Wealth concentration also creates asymmetric opportunities for the next generation. A child born into a family with a $100 million net worth starts with advantages that dwarf those of peers from middle-class backgrounds—access to elite education, private healthcare, and pre-arranged business connections. The system isn’t just about money; it’s about inheriting the infrastructure of success."Wealth isn’t just about what you have; it’s about what you can make happen with it." — A private wealth advisor, speaking off-record in 2023
Major Advantages
- Tax Optimization: Utilizing offshore accounts, trusts, and wealth-preservation vehicles to minimize liabilities while maintaining liquidity.
- Diversification Across Asset Classes: Spreading risk between public equities, private equity, real estate, and alternative investments like wine or classic cars.
- Generational Transfer: Structuring wealth to bypass estate taxes through family limited partnerships (FLPs) or dynasty trusts.
- Influence in Capital Markets: Access to pre-IPO rounds, private credit, and sovereign wealth funds—opportunities closed to retail investors.
- Philanthropic Leverage: Using charitable giving to reduce taxable income while funding pet projects or securing legacy influence.
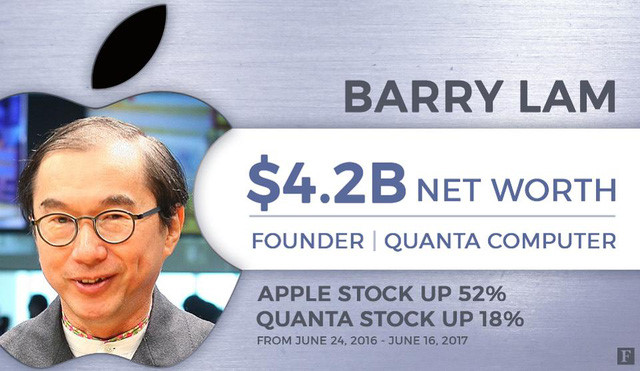
Comparative Analysis
| Wealth-Building Model | Key Characteristics |
|---|---|
| Tech Moguls (e.g., Zuckerberg, Musk) | Volatile net worth tied to public equity; high-risk, high-reward scaling strategies. |
| Industrial Dynasties (e.g., Rockefellers, Waltons) | Stable, compounding wealth from dividends and trust structures; lower volatility. |
| Hedge Fund Managers (e.g., Soros, Dalio) | Net worth fluctuates with fund performance; relies on leverage and macroeconomic bets. |
| Private Equity Operators (e.g., Blackstone, KKR) | Wealth grows through debt-fueled acquisitions; less public scrutiny than tech. |
| Legacy Inheritors (e.g., heirs to Vanderbilt, Rothschild) | Wealth preserved through family offices and dynastic trusts; minimal personal risk-taking. |
Future Trends and Innovations
The next decade will see fortune builders net worth evolve in three critical directions. First, AI and algorithmic trading will democratize—but also concentrate—wealth creation. High-frequency trading firms and quant funds will dominate liquid markets, while decentralized finance (DeFi) could emerge as a new frontier for high-net-worth speculators. Second, geopolitical fragmentation will force the ultra-rich to diversify assets across safe-haven jurisdictions, from Switzerland to Singapore. Finally, sustainability-linked investments will become a non-negotiable for the next generation of fortune builders. ESG (Environmental, Social, Governance) criteria are already shaping private equity deals, and carbon credits may soon join stocks and bonds as a core asset class. The question isn’t whether wealth will adapt to these trends—it’s which fortune builders will lead the charge.
Conclusion
The study of fortune builders net worth isn’t just about numbers; it’s about power structures. Whether through inherited privilege, entrepreneurial grit, or financial engineering, the mechanisms of wealth creation have remained surprisingly consistent across centuries. What’s changed is the speed and scale—today’s billionaires don’t just build fortunes; they reshape economies in the process. Yet the most enduring lesson is this: wealth is a tool, not an endpoint. The most successful fortune builders don’t hoard money; they deploy it strategically, whether to launch rockets, fund research, or buy influence. The future of high-net-worth dynamics will depend on how well these players adapt to disruption—and whether they’re willing to share the spoils with the rest of society.Comprehensive FAQs
Q: What’s the difference between gross and net worth for fortune builders?
A: Gross worth includes all assets—stocks, real estate, art, cash—without accounting for liabilities. Net worth, however, subtracts debts (loans, mortgages, taxes owed) to show true liquidity. For example, a tech CEO might list a $5 billion gross worth but have $1 billion in outstanding loans, reducing their net worth to $4 billion. High-net-worth individuals often structure their finances to minimize reported liabilities, making net worth a more accurate reflection of realizable wealth.
Q: How do offshore accounts affect fortune builders net worth?
A: Offshore accounts aren’t just tax avoidance tools—they’re wealth-preservation strategies. By holding assets in jurisdictions with favorable tax treaties (e.g., the Cayman Islands, Luxembourg), fortune builders can reduce capital gains taxes, estate duties, and even currency risks. Some estimates suggest $10-30 trillion of global wealth is held offshore, with the ultra-rich using trusts and private foundations to shield assets from legal claims. However, increased transparency laws (like the Crypto-Asset Reporting Framework) are making these structures harder to exploit.
Q: Can someone with a $10 million net worth be considered a fortune builder?
A: Not traditionally. Fortune builders typically operate at the $100 million+ level, where tax optimization, generational wealth transfer, and high-stakes investments become viable. A $10 million net worth is more common among high earners or mid-tier entrepreneurs, while true fortune builders focus on scaling beyond personal income—through equity stakes, private equity, or inherited wealth. That said, accelerated wealth growth (e.g., via real estate or crypto) can push someone into the fortune builder category faster.
Q: What’s the most common mistake fortune builders make with their net worth?
A: Overconcentration in a single asset class. Many high-net-worth individuals tie their wealth to one company (e.g., Musk’s Tesla), one sector (e.g., crypto), or one geography (e.g., Silicon Valley real estate). When markets correct, the impact can be catastrophic. Diversification—spreading assets across private equity, real estate, commodities, and cash equivalents—is the #1 rule of fortune preservation. Another pitfall? Lifestyle inflation—spending down wealth on luxury goods without reinvesting.
Q: How do fortune builders protect their wealth from lawsuits or creditors?
A: The tools are highly sophisticated:
- Asset Protection Trusts (APTs): Place assets beyond the reach of courts by transferring ownership to a trust in a favorable jurisdiction (e.g., the Cook Islands).
- Limited Liability Companies (LLCs): Isolate high-value assets (e.g., a vacation home) in separate entities to limit exposure in lawsuits.
- Insurance Policies: Umbrella policies (e.g., $50M+ liability coverage) act as a last line of defense.
- Charitable Remainder Trusts (CRTs): Shift assets to a trust where the fortune builder retains income but the principal is protected from creditors.
Q: Is it possible to build a $1 billion net worth from scratch in under 20 years?
A: Rare, but not impossible. The fastest self-made billionaires (e.g., Mark Zuckerberg, Evan Spiegel) did it by:
- Scaling a high-margin business (e.g., SaaS, e-commerce, fintech) to $1B+ in revenue.
- Leveraging VC funding to grow rapidly, then cashing out via IPO or acquisition.
- Reinvesting profits aggressively into private equity, real estate, or new ventures.
Q: What’s the biggest threat to fortune builders net worth today?
A: Regulatory crackdowns and inflation. Governments worldwide are targeting tax havens, private equity loopholes, and wealth hoarding—from the EU’s Digital Services Tax to the U.S. Corporate Minimum Tax. Meanwhile, persistent inflation erodes the purchasing power of cash holdings, forcing fortune builders to shift into hard assets (gold, real estate, collectibles). Other risks include:
- Geopolitical instability (e.g., sanctions on Russian oligarchs freezing assets).
- Cybersecurity threats (e.g., ransomware targeting high-net-worth individuals).
- Generational mismanagement (heirs squandering wealth through poor investments or legal disputes).
