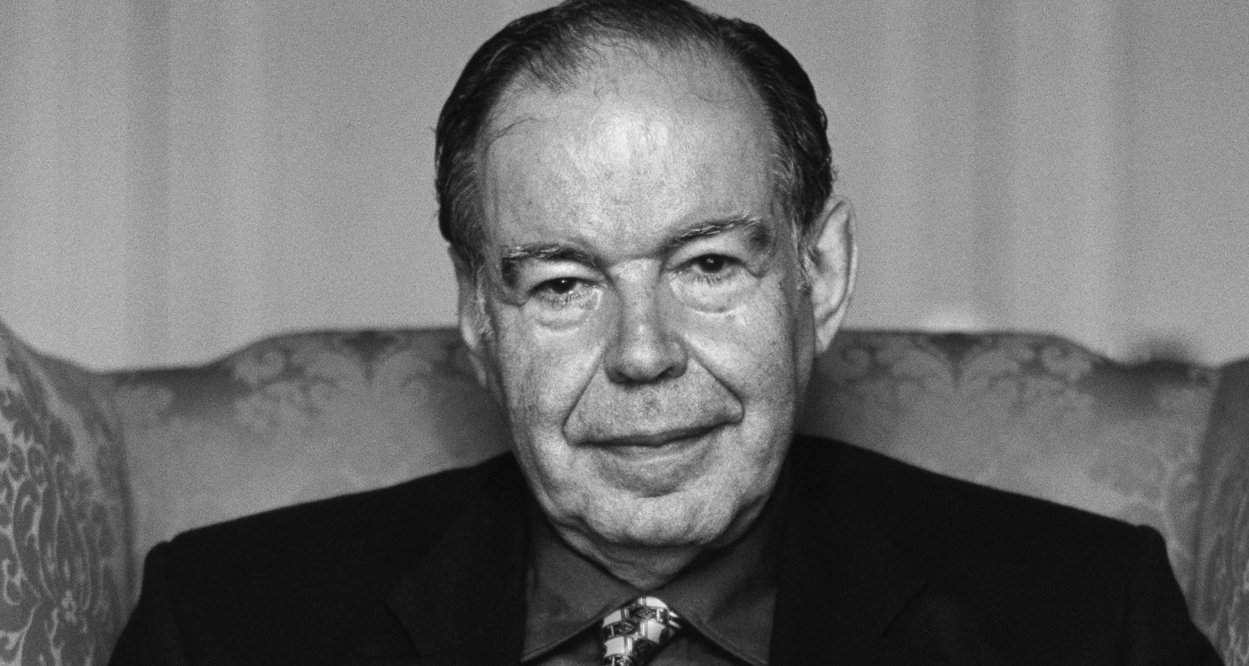
7 Things Worth Knowing About Edward de Bono’s Financial Empire
De Bono’s career offers a masterclass in monetizing abstract thought. His approach wasn’t about inventing a product but systematizing a way of thinking—and then selling access to it. Below are seven key aspects of how his intellectual property translated into lasting wealth.1. The Book Empire: A Self-Sustaining Revenue Stream
De Bono’s over 50 published works form the backbone of his financial legacy. Unlike niche academic texts, his books—Lateral Thinking, Six Thinking Hats, Simplicity—were designed for mass appeal, targeting business leaders, educators, and even children. The secret wasn’t just their ideas but their reusable format. Titles like Six Thinking Hats became perennial bestsellers, with translations in over 30 languages. His publishing deals weren’t one-time payments; they included royalties, reprint rights, and foreign editions, ensuring income long after initial sales. Even decades-old books remained in print, generating steady revenue. The model was simple: create a framework that solves a universal problem (e.g., decision-making paralysis), and the market will keep buying it. What’s less discussed is how de Bono controlled the narrative around his books. He avoided the "guru" trap by positioning himself as a systems designer rather than a charismatic speaker. This meant his works weren’t just read—they were licensed, adapted, and repurposed. Corporate training programs, for example, often bundled his methodologies into leadership courses, creating secondary revenue streams. His estate continues to earn from these adaptations, proving that intellectual property retains value when it’s modular and adaptable.2. Trademarked Thinking: The Business of Lateral Methods
De Bono didn’t just write about thinking—he patented it. His most lucrative innovations were trademarked frameworks like the Six Thinking Hats and CoRT (Creativity Research and Training). These weren’t just concepts; they were licensable tools. Companies paid to integrate them into internal workshops, and governments adopted them for public sector innovation programs. The Six Thinking Hats, for instance, became a staple in NASA’s astronaut training and Singapore’s education reforms, generating licensing fees that compounded over time. Unlike open-source ideas, de Bono’s methods were closed systems—controlled, updated, and monetized through certified practitioners. The financial mechanics were straightforward: high initial licensing costs for corporations, followed by ongoing certification fees for trainers. This created a recurring revenue model—similar to how software companies charge annual subscriptions. De Bono’s estate still collects royalties from these licenses, demonstrating how intellectual property can outlive its creator. The key was making his methods actionable yet proprietary, ensuring that only authorized users could claim to teach them.3. The Corporate Training Monopoly
De Bono’s consulting work was where his ideas met real-world revenue. He didn’t just sell books; he sold access to his thinking processes. Fortune 500 firms, military strategists, and even healthcare systems hired him to train their teams in lateral thinking. His fees weren’t modest—reportedly ranging from £50,000 to £200,000 per engagement—but the real money came from scaling his methods. Once a company adopted his frameworks, they often bought bulk licenses for internal use, creating multi-year contracts. His later years saw him franchising his training programs, where certified facilitators (who paid fees to de Bono’s organization) delivered his workshops globally. The corporate sector’s appetite for his methods was driven by measurable outcomes. Companies could track improvements in decision-making speed, creativity metrics, and conflict resolution—all tied to de Bono’s structured approaches. This results-driven selling made his consulting not just a service but an investment. Even after his death, his estate has maintained these corporate relationships, ensuring a steady stream of high-ticket consulting revenue.4. The Malta Advantage: Tax Efficiency and Legacy Planning
De Bono’s choice to base himself in Malta wasn’t coincidental. The island nation’s tax laws—particularly its low corporate tax rates and intellectual property incentives—made it an ideal hub for monetizing his ideas. Malta’s 15% flat tax on royalties (compared to higher rates in the UK or US) meant that licensing fees and book royalties were taxed at a fraction of the cost. Additionally, his estate could structure trusts and holding companies to shield wealth from inheritance taxes, ensuring that his financial empire remained intact across generations. Malta also offered legal protections for intellectual property, allowing de Bono to enforce trademarks aggressively. Any unauthorized use of his frameworks—such as bootleg training programs—could be shut down through local courts, preserving revenue streams. This jurisdictional strategy was critical in maintaining control over his financial legacy, ensuring that his wealth wasn’t eroded by piracy or unlicensed adaptations.5. The Silent Partner: His Wife’s Role in Financial Management
"Edward’s genius was in creating systems, but the real art was in making those systems self-sustaining. That took a business mind—and he had one in his wife, Mary." — A former associate of the de Bono familyMary de Bono, his wife of over 50 years, played a pivotal but understated role in managing his financial affairs. While Edward focused on innovation, Mary handled contract negotiations, estate planning, and licensing deals. Her background in administrative strategy ensured that his intellectual property was commercially viable from the outset. Even after his death, she oversaw the transition of his assets, including the Edward de Bono Institute of Thinking, which continues to generate revenue through research and licensing. Their partnership was a study in complementary skills: de Bono’s creativity paired with Mary’s operational rigor. This dynamic allowed his financial empire to outlast his active career, with revenues still flowing from his estate. The lack of public scrutiny around Edward de Bono net worth may also stem from Mary’s discretion—she ensured that his wealth remained private but productive.
6. The Posthumous Income Machine
One of the most fascinating aspects of de Bono’s financial legacy is how it continued generating revenue after his death. His estate didn’t just preserve his work—it expanded it. New editions of his books, digital adaptations of his training modules, and online courses (licensed through platforms like Coursera) kept his methodologies relevant. The Edward de Bono Institute in Malta became a profit center, offering certifications, research reports, and corporate workshops—all under his name. This posthumous monetization is rare in the world of intellectuals. Most thinkers see their financial impact fade after they’re gone, but de Bono’s structured approach ensured long-term income. Even his archives and unpublished notes have been commercialized, with his estate licensing them for educational use. The result? A self-perpetuating revenue cycle that turns his life’s work into a permanent asset.7. The Philosopher’s Paradox: Wealth Without the Usual Trappings
Here’s the counterintuitive truth about Edward de Bono net worth: he didn’t need to flaunt it. Unlike Silicon Valley billionaires or celebrity entrepreneurs, de Bono’s fortune wasn’t about luxury or status—it was about sustainability. His wealth was invisible in the traditional sense: no mansions in Monaco, no private jets, no high-profile investments. Instead, it was embedded in systems—books on shelves, frameworks in corporate training rooms, and royalties deposited quietly into offshore accounts. This low-key accumulation is why discussions about his financial standing are rare. There were no Forbes lists to track, no public stock portfolios to analyze. His real estate holdings were modest, and his personal spending was frugal by elite standards. Yet his net worth remained substantial and growing, because it wasn’t tied to fleeting trends but to universal human needs: better decision-making, creativity, and problem-solving.
How These Facts Connect
Edward de Bono’s financial story is a blueprint for monetizing intangibles. His career demonstrates that wealth in the knowledge economy isn’t about owning things—it’s about owning processes. The seven pillars outlined above—books, trademarks, corporate training, tax efficiency, family management, posthumous revenue, and quiet accumulation—form a cohesive system where each element reinforces the others. His books generated initial interest, which led to corporate licenses; those licenses required certified trainers, creating a feedback loop of revenue. Malta’s tax laws protected that revenue, while his wife’s administrative skills ensured it was managed efficiently. Even after his death, the system self-sustained, proving that ideas can be as durable as physical assets—if structured correctly. The most striking revelation is how de Bono’s wealth was anti-fragile. Unlike traditional fortunes built on volatile markets or real estate, his relied on human cognition—a need that only grows in an era of automation and complexity. His methods weren’t just sold; they were embedded into organizational DNA, ensuring recurring demand. This structural resilience is what separates his financial legacy from the ephemeral wealth of trend-chasing entrepreneurs. His story suggests that in the 21st century, the most secure wealth isn’t in stocks or gold—it’s in frameworks that make people smarter.| Key Revenue Driver | Financial Mechanism | Legacy Impact |
|---|---|---|
| Book Royalties | Perpetual reprints, translations, foreign editions | Steady passive income; books remain in print decades later |
| Licensed Frameworks | Corporate training contracts, certification fees | Recurring revenue; methods remain proprietary |
| Posthumous Adaptations | Digital courses, institute research, archival licensing | Wealth generation continues after creator’s death |
Conclusion
Edward de Bono’s financial empire was not an accident but an architecture. His net worth wasn’t the result of luck or a single breakthrough—it was the outcome of systematic monetization. By treating thinking itself as a commodity, he created a model that transcends industries. His career offers a masterclass in how to turn abstract ideas into tangible assets, and his estate proves that such wealth can outlast its creator. In an age where intangibles dominate the economy, de Bono’s story is a case study in sustainable intellectual capital. The lesson isn’t just about money—it’s about ownership. De Bono didn’t just write books; he owned the right to think differently. He didn’t just give speeches; he licensed the methodology behind them. And he didn’t just leave a legacy; he built a machine that keeps producing revenue. For anyone seeking to understand how ideas can generate lasting wealth, his financial journey is far more instructive than the rags-to-riches tales of tech founders or pop stars.Comprehensive FAQs
Q: How much is Edward de Bono’s net worth estimated to be?
Exact figures are private, but industry estimates place his net worth in the £10–20 million range. This includes royalties, licensing fees, and corporate consulting income. Unlike public figures in entertainment or tech, de Bono’s wealth was not flashy—it was embedded in intellectual property and structured financial systems.
Q: Did Edward de Bono leave behind a trust or foundation to manage his wealth?
Yes. His estate is overseen by the Edward de Bono Institute of Thinking, based in Malta. This organization continues to license his methodologies, publish his works, and generate revenue through corporate training and research. His wife, Mary de Bono, played a key role in establishing its financial structure.
Q: How did de Bono’s books generate so much revenue?
His books weren’t just sold—they were designed for perpetual relevance. Titles like Six Thinking Hats and Lateral Thinking became evergreen bestsellers due to their practical, universal appeal. Revenue came from initial sales, royalties, translations, and corporate bundling (where companies included his books in leadership training programs). New editions and digital adaptations kept income streams active.
Q: Were there any major lawsuits or disputes over his intellectual property?
There were no high-profile lawsuits, but de Bono’s estate has actively enforced trademarks to prevent unauthorized use of his frameworks. Malta’s legal system allowed him to shut down bootleg training programs and license only certified practitioners. This control ensured that his intellectual property retained its monetary value without dilution.
Q: How did Malta’s tax laws benefit de Bono’s financial strategy?
Malta’s 15% flat tax on royalties (compared to higher rates in the UK or US) made licensing fees far more tax-efficient. Additionally, the country’s intellectual property protections allowed de Bono to enforce trademarks aggressively, while its trust laws helped shield wealth from inheritance taxes. His estate could also structure holding companies to optimize revenue distribution.
Q: Did de Bono’s wealth grow significantly after his death?
Yes. His estate has expanded revenue streams through digital adaptations (e.g., online courses), new book editions, and corporate licensing deals. The Edward de Bono Institute continues to generate income by offering certifications, research reports, and workshops—all under his name. This posthumous monetization is rare in intellectual circles.
Q: What’s the biggest misconception about Edward de Bono’s financial legacy?
The assumption that his wealth was passive or accidental. In reality, it was actively managed and structured—a mix of intellectual property control, tax efficiency, and corporate partnerships. His fortune wasn’t about luxury spending but about sustainable systems, proving that ideas can be as valuable as physical assets when properly monetized.
Q: Are there any public records or documents detailing his financial deals?
Very few. De Bono was private about his finances, and Malta’s laws don’t require public disclosures for non-political figures. Most information comes from industry estimates, former associates, and corporate licensing agreements (which are typically confidential). His estate has no obligation to disclose exact figures, making precise details difficult to obtain.
