Where It All Began
Ulrich Körner’s path to the top of Credit Suisse was not the conventional one. Unlike many of his predecessors, who cut their teeth in the bank’s legendary private banking division, Körner rose through the ranks of corporate and investment banking—a division that, by the 2000s, was becoming synonymous with risk. His early career at Credit Suisse in the 1990s coincided with the bank’s aggressive expansion into global markets, a strategy that would later backfire spectacularly. By the time he became CEO, the bank’s balance sheet was bloated with toxic assets from the 2008 financial crisis, and its reputation had been battered by the Archegos and Greensill Capital collapses—scandals that exposed deep flaws in its risk management. The early signs of Körner’s leadership were mixed. His appointment in 2015 was seen as a stabilizing force, but the bank’s problems were systemic. Share prices remained depressed, and the CEO of Credit Suisse net worth—while never disclosed in detail—was likely tied to the bank’s underperformance. Industry estimates at the time suggested his compensation was modest compared to peers at Goldman Sachs or JPMorgan, reflecting the bank’s constrained financial state. Yet Körner’s real challenge was not just turning around earnings but restoring trust in an institution that had become synonymous with failure.The Early Signs
Körner’s first major test came in 2016, when Credit Suisse was forced to pay a $4.9 billion fine for its role in the 1-I Bank fraud scandal—a case that exposed the bank’s lax oversight in the U.S. The fallout was immediate: investor confidence plummeted, and the CEO of Credit Suisse net worth took another hit, as stock-based compensation became a liability. The bank’s market capitalization sank below CHF 10 billion, a fraction of its pre-crisis peak. Analysts at the time speculated that Körner’s personal wealth, heavily tied to Credit Suisse shares and deferred bonuses, had shrunk by as much as 40% since his appointment. Yet Körner’s response was methodical. He launched a cost-cutting drive, shedding thousands of jobs and divesting underperforming units like the investment bank. The strategy paid off in the short term—net income stabilized, and by 2018, the bank reported its first profitable year in a decade. But the gains were fragile. The CEO of Credit Suisse net worth began to recover, though not enough to match the fortunes of his counterparts at healthier institutions. The bank’s reliance on private banking—its last bastion of profitability—meant Körner’s compensation remained tied to a volatile asset class, where client withdrawals could trigger another crisis overnight.The Turning Point
The inflection point arrived in March 2023, when Credit Suisse’s liquidity crisis erupted. A single run on the bank’s AT1 bonds—considered among the safest in finance—sent shockwaves through global markets. Overnight, the bank’s solvency was called into question, and the CEO of Credit Suisse net worth became a liability in its own right. As depositors fled and regulators scrambled to contain the damage, Körner’s leadership was put under the microscope. The Swiss National Bank’s emergency intervention, followed by the forced merger with UBS, effectively ended his tenure—and with it, any hope of a traditional exit package. The turning point wasn’t just financial; it was psychological. For years, Körner had operated under the assumption that Credit Suisse could right itself through gradual reform. The 2023 crisis proved otherwise. The bank’s collapse was swift, and the CEO of Credit Suisse net worth—whatever it had been—was now irrelevant. In the aftermath, Körner’s compensation was slashed, and his future in banking was uncertain. The merger with UBS, structured as a hostile takeover, ensured that no golden parachute would soften the blow."You don’t rebuild trust in a bank by cutting costs. You rebuild it by proving you won’t fail again. We didn’t get that chance." — Anonymous former Credit Suisse executive, reflecting on Körner’s tenure.

The Build-Up, Year by Year
| Period | Key Events | Impact on CEO of Credit Suisse Net Worth | |------------------|---------------------------------------------------------------------------------|-------------------------------------------------------------------------------------------------------------| | 2015–2017 | Appointment as CEO; $4.9B fine for 1-I Bank scandal; cost-cutting begins. | Estimated decline of 30–40% due to stock underperformance and deferred bonus losses. | | 2018–2019 | First profitable year post-crisis; focus on private banking. | Partial recovery, but wealth remains tied to volatile assets. | | 2020–2021 | Pandemic recovery; Greensill Capital collapse exposes risk management failures. | Minimal growth; compensation tied to underperforming investment bank. | | 2022 | Rising inflation; AT1 bond concerns emerge. | Wealth stabilizes but remains below pre-2015 levels. | | March 2023 | Liquidity crisis; SNB intervention; forced UBS merger. | Net worth effectively wiped out; no traditional severance package. |Lessons From the Journey
- The wealth of a bank CEO is a lagging indicator. Körner’s net worth never reflected Credit Suisse’s true struggles until the crisis hit.
- Stock-based compensation is a double-edged sword in troubled banks. When shares collapse, so does personal wealth.
- Regulatory fines and scandals can erase years of accumulated wealth overnight.
- The private banking model, once a safe haven, became a liability as client trust eroded.
- In a forced merger, even the CEO’s financial survival is at the mercy of regulators—not the board.
Where Things Stand Today
As of 2024, Ulrich Körner’s financial standing remains a subject of speculation. Unlike his predecessor, Tidjane Thiam—who left with a reported net worth in the hundreds of millions—Körner’s exit was abrupt and uncompensated. Industry estimates suggest his personal wealth, once tied to Credit Suisse stock and bonuses, has been significantly diminished. The bank’s merger with UBS, structured to avoid shareholder dilution, ensured that no traditional severance or retention bonuses would materialize. Körner’s post-Credit Suisse future is unclear; he has not taken on a public role since leaving, and his name no longer appears in discussions of Swiss banking’s elite. The broader lesson is that the CEO of Credit Suisse net worth was never just about personal gain. It was a reflection of an institution’s health—and in Körner’s case, a cautionary tale about the limits of leadership in an era of systemic risk. The bank’s collapse didn’t just cost shareholders; it cost its CEO the one thing no executive can insure against: control over their own financial destiny.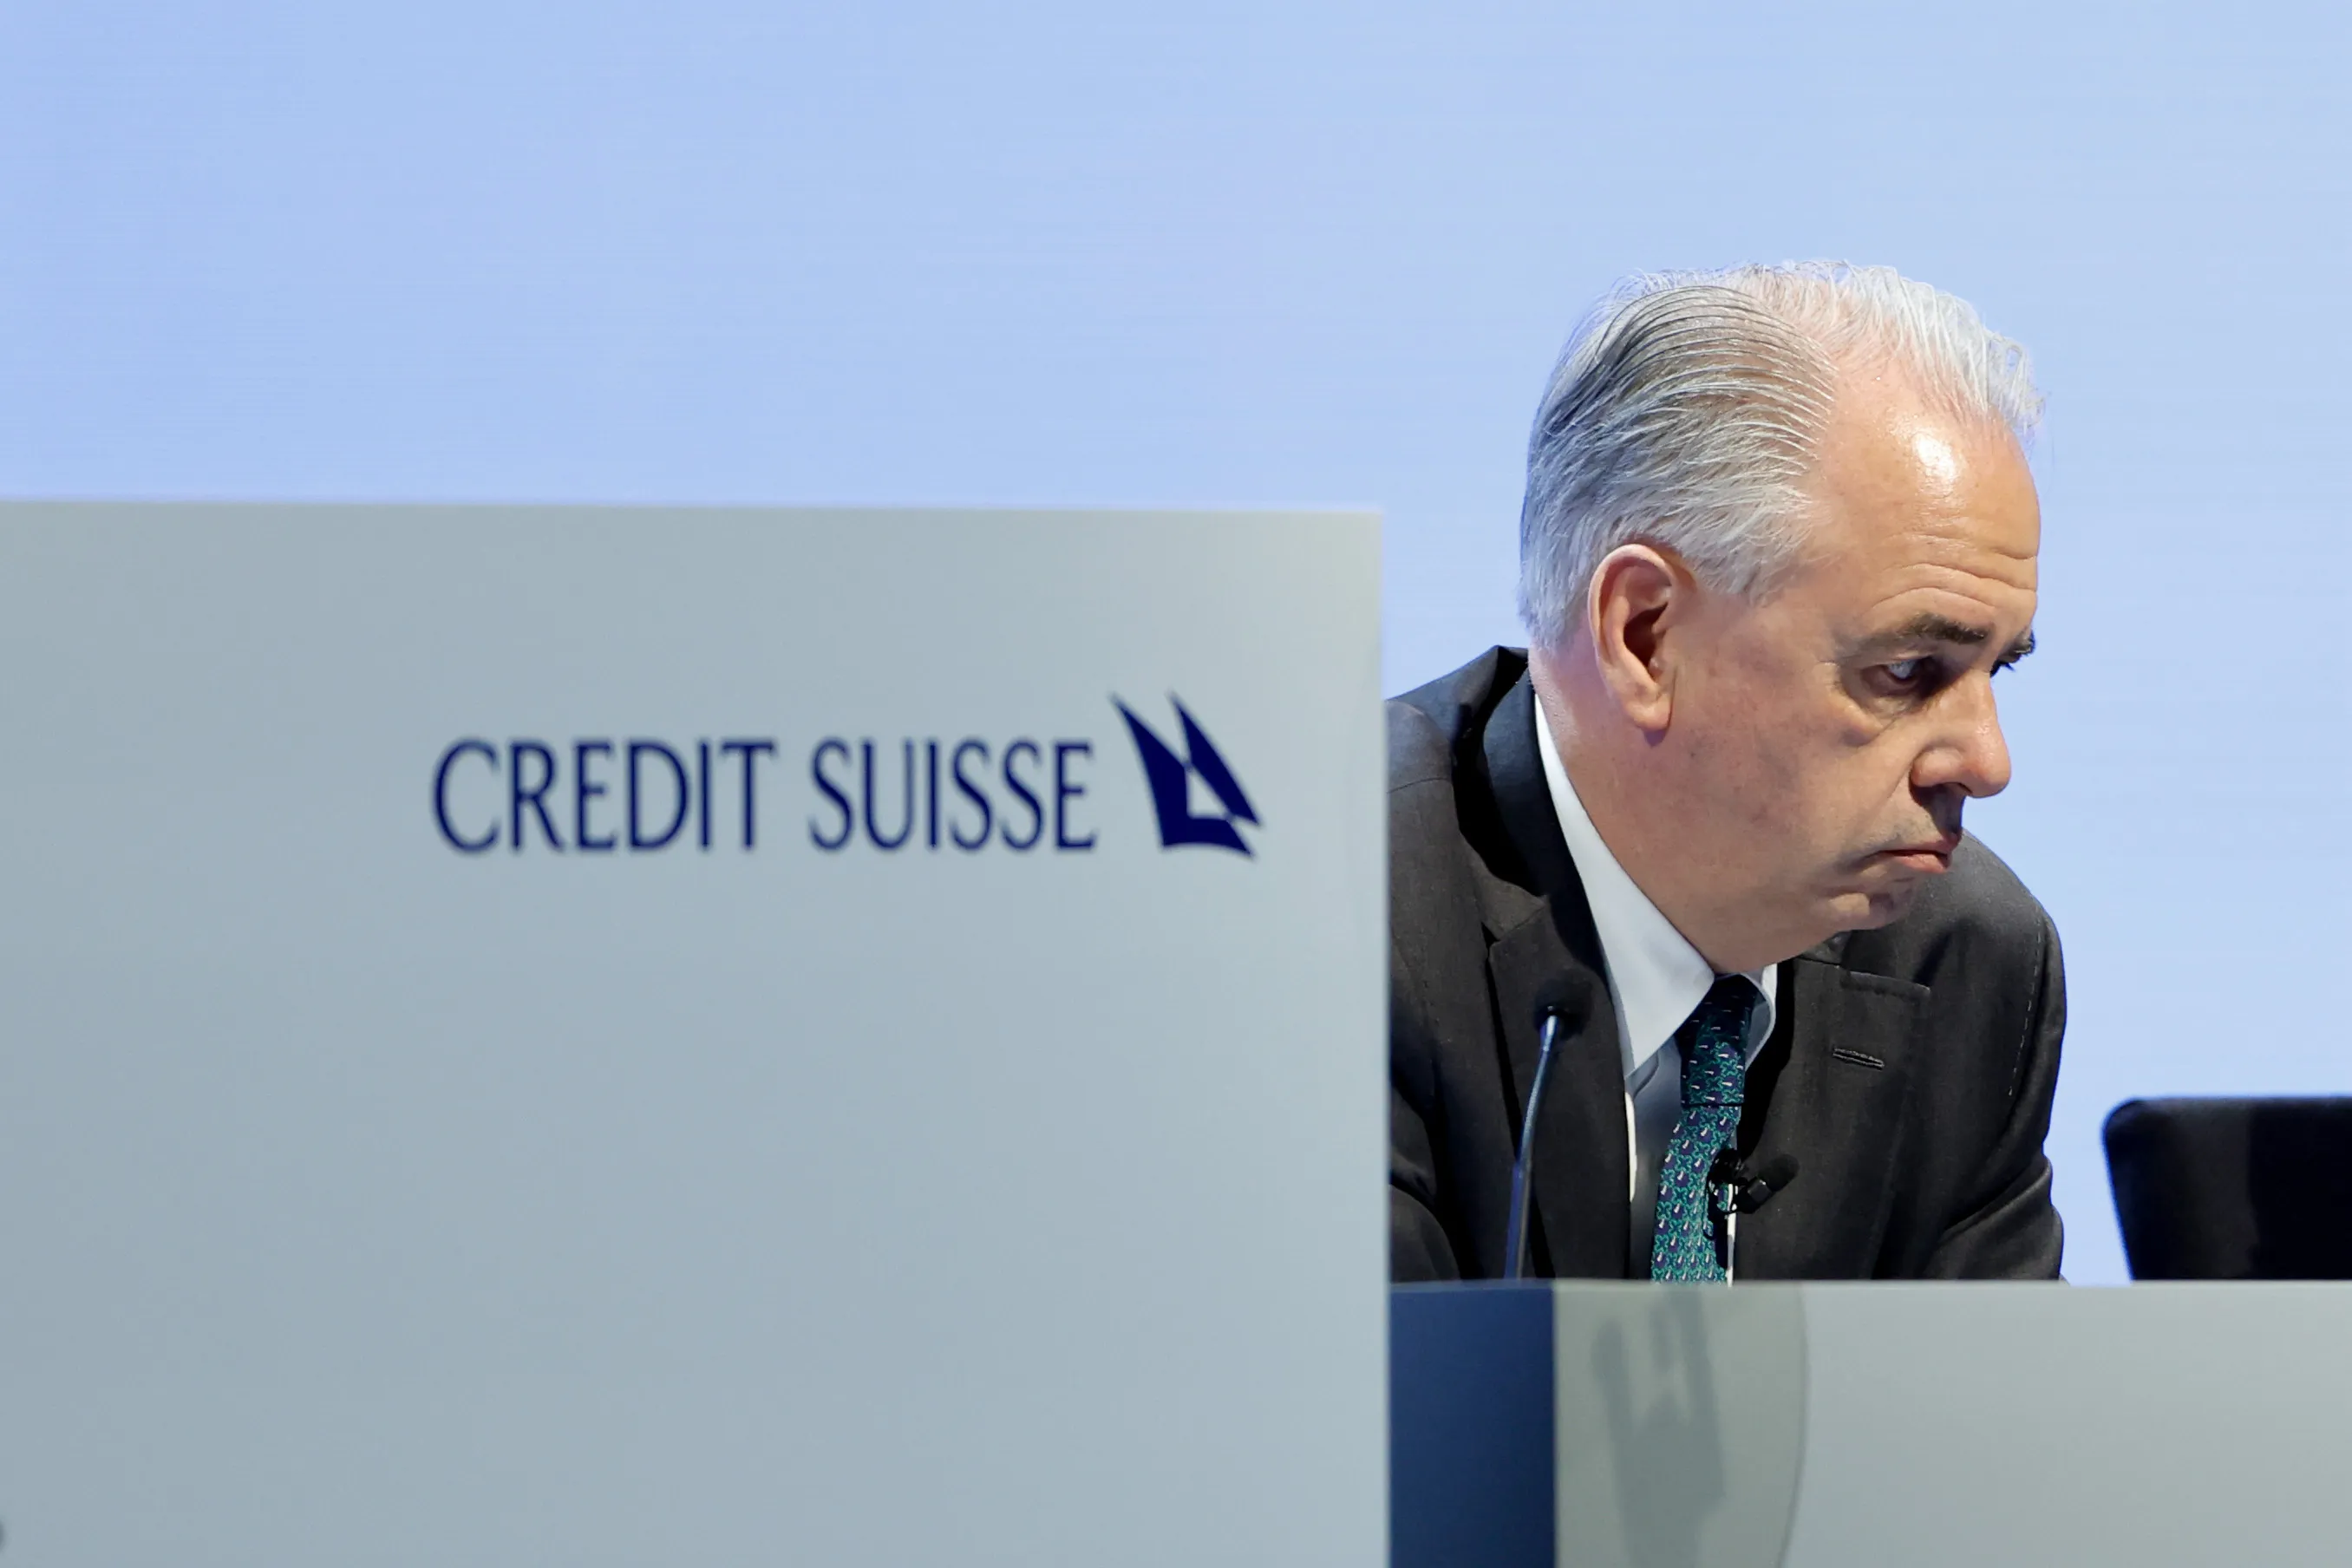
Conclusion
Ulrich Körner’s story is not one of extravagant wealth, but of the quiet unraveling of a career built on the assumption that stability was guaranteed. The CEO of Credit Suisse net worth was never a headline-grabbing figure, but its fluctuations told a story of an industry in transition—where even the most disciplined executives could be undone by forces beyond their control. Körner’s tenure at Credit Suisse was a masterclass in how personal finance and institutional fate are intertwined, and how quickly fortunes can shift when the system itself is under siege. For those who followed Swiss banking, Körner’s exit marked the end of an era. The question now is whether his successor—or any future CEO at Credit Suisse’s successor institution—will fare any better. The answer may lie not in personal wealth, but in whether the lessons of 2023 have been learned. One thing is certain: in banking, the CEO of Credit Suisse net worth is never just a number. It’s a warning.Comprehensive FAQs
Q: What was Ulrich Körner’s reported net worth at the height of his tenure?
Exact figures are not publicly disclosed, but industry estimates in 2019–2020 suggested his net worth was in the £50–£100 million range, primarily tied to Credit Suisse stock and deferred compensation. This was modest compared to peers at global banks but reflective of the bank’s constrained financial state.
Q: Did Körner receive a severance package after leaving Credit Suisse?
No. Unlike many forced exits in banking, Körner’s departure was structured with no traditional severance or retention bonuses. The UBS merger was designed to minimize liabilities, leaving his financial settlement minimal.
Q: How did the 2023 crisis affect the CEO of Credit Suisse net worth?
The crisis effectively wiped out any remaining value in Körner’s Credit Suisse-linked wealth. AT1 bond losses, stock devaluations, and the collapse of the bank’s market capitalization ensured that his personal net worth took a catastrophic hit.
Q: Were there rumors of a "golden parachute" for Körner?
Speculation arose in March 2023 that Körner might negotiate a substantial exit package, but these claims were quickly dismissed by regulators. The Swiss Financial Market Supervisory Authority (FINMA) ensured no such arrangements were made.
Q: How does Körner’s wealth compare to other former Credit Suisse CEOs?
Körner’s reported net worth is significantly lower than that of Tidjane Thiam, who left in 2017 with an estimated £200–£300 million. This reflects both the bank’s decline under Körner’s watch and the harsh terms of his exit.
Q: Could Körner’s personal wealth recover in the future?
Possible, but unlikely in the near term. Without a new banking role or substantial external investments, his financial recovery would depend on the performance of any remaining Credit Suisse/UBS-related assets—though these are now minimal.
Q: Did Körner’s compensation structure change during his tenure?
Yes. Early in his tenure, his pay was heavily tied to stock performance and risk-adjusted returns. By 2022, as AT1 bond concerns grew, the structure shifted toward fixed salaries and performance-linked bonuses—though these became irrelevant after the 2023 crisis.
Q: Is there any public record of Körner’s post-exit financial moves?
No. Körner has not taken on a public role, and there are no verified reports of new business ventures or high-profile investments. His financial activities, if any, remain private.
