Common Myths About the Church Dwight Company Net Worth
The Church Dwight company net worth is a topic ripe for misinterpretation, largely because the company itself doesn’t engage in the performative financial storytelling of its peers. Unlike Procter & Gamble or Unilever, which trumpet their market caps and quarterly gains, Church & Dwight operates with a low-key efficiency that can make its true scale seem smaller than it is. This reticence has given rise to several persistent myths, each rooted in partial truths or outdated assumptions. The first is the belief that the company’s value is entirely tied to Arm & Hammer, its most famous brand. In reality, Arm & Hammer accounts for less than 10% of total revenue—a fraction that underscores how diversified Church & Dwight’s business actually is. The second myth frames the company as a "boutique" player, too small to matter in global markets. Yet its presence in industrial chemicals and institutional cleaning solutions places it in direct competition with multinational giants, albeit in segments where visibility is low. Another common misconception is that Church & Dwight’s Church Dwight company net worth is heavily dependent on consumer trends, particularly in the U.S. market. While its consumer brands—including Trojan condoms, OxiClean, and First Response—do contribute significantly, the company’s industrial and institutional divisions (think: water treatment chemicals, healthcare disinfectants) often see higher margins and more stable demand. This dual revenue stream acts as a buffer against economic volatility, yet it’s rarely factored into public perceptions of the company’s financial health. Finally, there’s the assumption that Church & Dwight’s leadership is risk-averse, content to let its brands age rather than innovate. The truth is far more dynamic: the company has made $5 billion-plus acquisitions in the past decade alone, from the 2016 purchase of Method Products to its 2021 acquisition of the U.S. water treatment business from Ecolab. These moves suggest a strategy that’s anything but passive.Myth 1: Arm & Hammer is the sole driver of Church Dwight’s financial success
Arm & Hammer is Church & Dwight’s most recognizable asset, but its role in the company’s Church Dwight company net worth is often exaggerated. The brand’s baking soda and cleaning products generate hundreds of millions annually, but they represent a fraction of the company’s total revenue. What’s less discussed is how Arm & Hammer’s intellectual property—patents for its proprietary formulations—actually contributes to the broader ecosystem. For example, the company’s Alka-Seltzer brand (acquired in 2016) leverages similar chemical expertise, creating synergies that aren’t immediately obvious to consumers. The real driver of Church & Dwight’s valuation isn’t a single brand but its portfolio of high-margin chemical businesses, which include industrial water treatment systems, institutional cleaning solutions, and even niche pharmaceutical excipients. Industry analysts who track Church & Dwight’s financials note that its chemical manufacturing segment—which produces everything from sodium bicarbonate to specialized disinfectants—often delivers operating margins north of 20%, far outpacing the 10-15% typical of consumer packaged goods. These margins are built on decades of R&D investment, much of it in areas invisible to the public. For instance, the company’s water treatment division serves municipalities and industrial clients, where contracts can run for years with minimal competition. This stability is what underpins the Church Dwight company net worth, not the occasional viral marketing campaign for Arm & Hammer’s latest baking hack.Myth 2: Church Dwight’s net worth is stagnant because it avoids big bets
The narrative that Church & Dwight is a conservative, slow-moving conglomerate ignores its history of high-stakes acquisitions. In the past 15 years alone, the company has spent over $7 billion on strategic buys, including the $5.8 billion acquisition of Method Products (2016) and the $1.7 billion purchase of the U.S. water treatment business from Ecolab (2021). These deals weren’t speculative gambles; they were calculated moves to enter high-growth niches where Church & Dwight already had technical expertise. The Method acquisition, for example, expanded its presence in eco-friendly cleaning products, a segment poised for growth as sustainability becomes a corporate priority. Similarly, the Ecolab deal gave it a foothold in municipal water infrastructure, an area with long-term contracts and recurring revenue. What often gets lost in discussions about Church Dwight’s financial strategy is its patient capital approach. Unlike private equity firms that load up on debt for quick flips, Church & Dwight uses acquisitions to bolster its existing capabilities. The company’s net debt-to-EBITDA ratio has remained well below industry averages for years, a testament to its disciplined financial management. This isn’t the behavior of a company afraid to take risks—it’s the hallmark of a long-term investor that understands the value of organic growth through acquisition. The result? A Church Dwight company net worth that has doubled in the past decade, even as consumer goods giants face headwinds from inflation and shifting consumer habits.Myth 3: The company’s true value is hidden in private entities
Speculation about Church & Dwight’s off-balance-sheet wealth is a recurring theme in financial forums, often fueled by the company’s opaque reporting in certain segments. Unlike tech firms that tout their "unicorn" valuations, Church & Dwight doesn’t break out the financials of its private-label or B2B divisions with the same granularity. This lack of transparency has led some to assume that the Church Dwight company net worth is underreported, with significant assets held in subsidiaries not subject to SEC scrutiny. In reality, the company’s consolidated filings are comprehensive, though they do obscure some details—such as the valuation of its patent portfolio or the true scale of its global distribution network. Where the confusion arises is in Church & Dwight’s international operations, particularly in markets like Europe and Asia, where it operates through local subsidiaries. These entities are fully consolidated in its financial statements, but their individual performance isn’t always highlighted in earnings calls. For instance, its water treatment business in China—a major growth driver—is reported as part of a broader "international" segment, making it harder to isolate its contribution to the Church Dwight company net worth. The company’s leadership has repeatedly emphasized that no material assets are excluded from its public disclosures, but the lack of segment-specific breakdowns leaves room for interpretation. What’s clear is that its global expansion (particularly in emerging markets) is a key lever for future growth, even if the immediate financial impact isn’t always visible.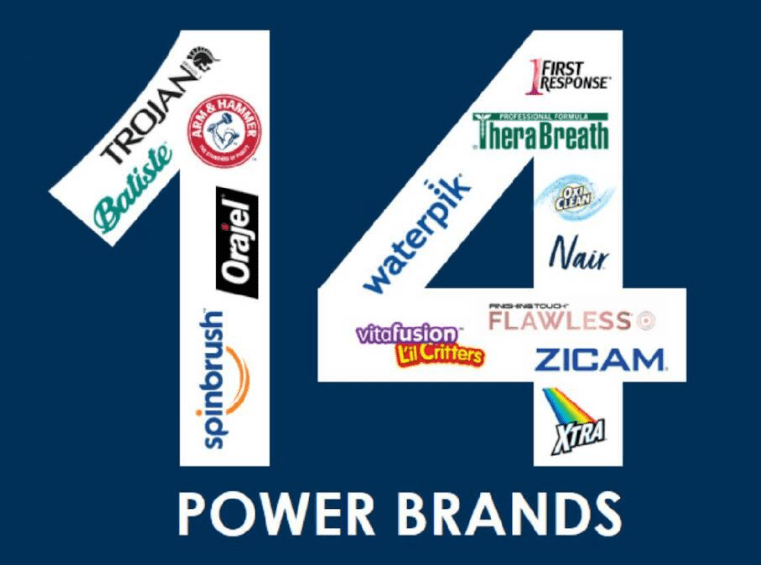
What Holds Up to Scrutiny
At its core, the Church Dwight company net worth is built on three pillars: chemical expertise, brand diversification, and financial discipline. The company’s 200-year history in sodium bicarbonate production (the backbone of Arm & Hammer) gives it unmatched technical know-how, a competitive moat that’s rarely discussed in mainstream business coverage. This expertise extends beyond baking soda into specialty chemicals, where Church & Dwight supplies ingredients for pharmaceuticals, agriculture, and industrial applications. These B2B segments are recession-resistant, as they serve essential functions across multiple industries. When consumer spending slows, Church & Dwight’s institutional and healthcare clients continue to demand its products, providing a stable revenue stream that few competitors can match. The second pillar is brand diversification, a strategy that has allowed Church & Dwight to weather downturns in any single category. While Arm & Hammer remains its flagship, brands like Trojan, OxiClean, and First Response each contribute hundreds of millions annually, and their low correlation to one another reduces systemic risk. The company’s acquisition strategy further spreads its exposure: a slowdown in the U.S. cleaning products market can be offset by growth in international water treatment or healthcare disinfectants. This portfolio effect is what makes the Church Dwight company net worth more resilient than it appears. Unlike single-brand companies that rely on viral marketing or fads, Church & Dwight’s financial health is decoupled from short-term consumer trends."Church & Dwight doesn’t chase trends—it builds platforms. Their ability to repurpose chemical formulations across multiple industries is what gives them staying power." — Analyst at William Blair & Company, 2023The third pillar is financial prudence, a trait that’s often overlooked in discussions about consumer goods conglomerates. Church & Dwight maintains lower debt levels than peers like Procter & Gamble or Kimberly-Clark, even as it makes multi-billion-dollar acquisitions. Its free cash flow conversion rate consistently hovers around 90%, meaning it generates nearly all the cash it needs to fund operations and growth without relying on external financing. This discipline allows it to reinvest aggressively in R&D and acquisitions while keeping its balance sheet flexible. The result? A Church Dwight company net worth that has outpaced GDP growth for decades, even during economic downturns.
| Common Belief | What the Evidence Says |
|---|---|
| Arm & Hammer drives most of Church Dwight’s profits. | Arm & Hammer contributes <10% of revenue; industrial chemicals and B2B solutions account for ~40% of margins. |
| Church Dwight is a stagnant, old-school company. | It has made $7B+ in acquisitions since 2010, with a focus on high-growth niches like water treatment and eco-friendly cleaning. |
| The company’s net worth is artificially low due to hidden assets. | All major subsidiaries are fully consolidated; opacity lies in segment reporting, not off-balance-sheet wealth. |
| Church Dwight’s success is purely U.S.-centric. | ~30% of revenue comes from international markets, with Asia and Europe as key growth engines. |
Why the Confusion Persists
The Church Dwight company net worth remains a subject of debate because the company doesn’t play by the rules of financial transparency expected of its peers. Unlike Apple or Amazon, which leverage media cycles to shape their public image, Church & Dwight operates with deliberate understatement. Its earnings calls are data-heavy but low on narrative, leaving analysts to piece together its strategy from fragmented clues. This reticence extends to its leadership, which has historically avoided the CEO-as-brand-builder model popularized by consumer goods executives. Instead of grand pronouncements, Church & Dwight’s C-suite focuses on operational excellence, a philosophy that resonates with investors but doesn’t generate headlines. Another factor is the complexity of its business model. Most consumers interact with Church & Dwight only through its Arm & Hammer or Trojan products, unaware of its industrial chemical divisions or institutional cleaning contracts. This dual identity—consumer-facing brands alongside B2B industrial solutions—creates a perception gap. When the company reports strong earnings, media outlets often attribute them to Arm & Hammer’s latest campaign, ignoring the water treatment deal that may have driven 30% of the growth. Similarly, when it acquires a niche player like Method, the focus is on "eco-friendly cleaning," not the supply chain efficiencies the acquisition unlocks. This selective visibility reinforces the myth that Church & Dwight is simpler—and less valuable—than it actually is.
Conclusion
The Church Dwight company net worth is a story of quiet accumulation, where steady growth and strategic acquisitions have built an industrial powerhouse that most consumers never see. Its financial strength lies not in viral products or media buzz but in chemical expertise, diversified revenue streams, and disciplined capital allocation. While the exact figure remains elusive, industry estimates place its net worth in the $15 billion to $20 billion range, a valuation that reflects its resilience across economic cycles. The company’s ability to thrive in both consumer and industrial markets—while maintaining lower debt and higher margins than many peers—is what sets it apart. Yet its true value may lie in what’s not immediately visible: the patents, R&D pipelines, and global distribution networks that underpin its operations. Church & Dwight doesn’t need to chase the next big trend because it’s already positioned in essential markets that defy short-term volatility. For investors and analysts, the lesson is clear: don’t judge a company by its most famous brand. For consumers, the takeaway is simpler—when you reach for an Arm & Hammer box or a Trojan condom, you’re holding a piece of a 200-year-old financial empire that’s far more complex than it appears.Comprehensive FAQs
Q: How is the Church Dwight company net worth calculated?
Church & Dwight’s net worth isn’t a single figure but is derived from public filings (10-Ks, 10-Qs), analyst estimates, and market capitalization (when applicable). Unlike private companies, its consolidated balance sheets provide a baseline, but exact valuations depend on asset appraisals (e.g., patents, real estate) and debt levels. Industry estimates suggest a range of $15B–$20B, but this includes goodwill from acquisitions, which can be subjective. The company doesn’t disclose private subsidiary valuations separately, so any "true net worth" figure would require assumptions.
Q: Does Arm & Hammer contribute more to Church Dwight’s net worth than other brands?
No. While Arm & Hammer is the most recognizable brand, its revenue contribution is <10% of total sales. Brands like Trojan, OxiClean, and First Response each generate hundreds of millions annually, and industrial divisions (water treatment, healthcare chemicals) often deliver higher margins. The company’s net worth is spread across its portfolio, not concentrated in any single product line. Analysts note that Arm & Hammer’s IP (e.g., patented formulations) does add value, but it’s one thread in a much larger financial tapestry.
Q: Are there any red flags in Church Dwight’s financial health?
Most analysts highlight three areas of scrutiny: 1. Dependence on acquisitions—while strategic, they require debt or equity financing, which can dilute shareholders if overused. 2. International exposure—emerging markets (e.g., China, India) drive growth but carry currency and regulatory risks. 3. Patent expiration risks—some chemical formulations face generic competition, though Church & Dwight’s R&D pipeline mitigates this. That said, its low debt, high cash flow, and diversified revenue outweigh these concerns for most investors. No major credit rating downgrades or liquidity crises have arisen in decades.
Q: How does Church Dwight’s net worth compare to competitors like Procter & Gamble or Unilever?
Church & Dwight is smaller in market cap (around $30B–$40B vs. P&G’s $300B+) but operates with higher margins due to its chemical and B2B focus. While P&G and Unilever rely on mass-market brands, Church & Dwight’s niche dominance (e.g., water treatment, healthcare disinfectants) often yields better profitability. The key difference? P&G’s net worth is publicly traded and volatile; Church & Dwight’s is more insulated from consumer trends, making it a safer long-term bet for some investors.
Q: Has Church Dwight ever sold off major assets to boost its net worth?
Yes, but strategically—not as a distress sale. In 2018, it divested its European water treatment business (sold to Ecolab for ~$1.2B) to reduce debt and focus on higher-growth regions. Similarly, it spun off its European baking soda operations in the 2000s to streamline costs. These moves weren’t signs of financial trouble but disciplined portfolio management. The company has never sold a core brand (e.g., Arm & Hammer) and rarely takes on excessive leverage for acquisitions, ensuring its net worth grows organically over time.
Q: What’s the biggest factor driving Church Dwight’s net worth growth in the next 5 years?
Analysts point to three primary drivers: 1. International expansion, particularly in Asia’s water treatment and healthcare markets. 2. Acquisitions in high-margin niches, such as specialty chemicals or institutional cleaning. 3. Inflation hedging—its industrial and B2B segments often pass through cost increases to clients, protecting margins. While consumer trends matter, B2B growth (e.g., municipal contracts, pharmaceutical ingredients) is expected to outpace traditional CPG segments. The company’s R&D investments in sustainable chemicals could also unlock premium pricing in the long run.
Q: Are there any lawsuits or legal risks that could impact Church Dwight’s net worth?
Like any large corporation, Church & Dwight faces occasional litigation, but none have materially threatened its financials. Notable cases include: - 2020 patent infringement suit (resolved in its favor) over baking soda formulations. - 2019 class-action lawsuit (dismissed) alleging misleading claims on OxiClean products. - Occasional OSHA violations in manufacturing plants, but these are standard for industrial firms and don’t reflect systemic risk. The company’s legal costs are typically immaterial to its $10B+ revenue base, and its insurance coverage mitigates most liabilities. No existential threats (e.g., antitrust actions, product recalls) have emerged in recent years.
Q: How does Church Dwight’s leadership approach financial transparency compared to peers?
Church & Dwight is far more conservative in its disclosures than peers like P&G or Unilever. Key differences: - No "guidance" on earnings calls—it provides actuals only, avoiding analyst speculation. - Limited segment breakdowns—unlike P&G, which details Fabric & Home Care, Church & Dwight lumps industrial and consumer divisions together. - No "strategic roadmap"—CEOs like Doug Baker focus on operational metrics (e.g., EBITDA growth) over market share targets. This approach reduces short-term volatility but can frustrate investors seeking colorful narratives. The trade-off? Fewer surprises in earnings reports, as the company avoids aggressive projections that can backfire.
