
5 Things Worth Knowing About Beef Production USA Net Worth
The beef production USA net worth ecosystem operates on principles that differ sharply from other sectors. Unlike tech startups where valuation hinges on growth potential, beef wealth is tied to tangible assets: land, cattle, and infrastructure. Yet even these assets are subject to forces beyond a rancher’s control—from global protein demand to climate litigation risks. Below are five foundational truths about how this wealth is generated, preserved, or eroded.1. Land Values Drive 60% of Ranch Net Worth
For most cattle operations, the land isn’t just a workspace—it’s the primary store of value. In Texas and Nebraska, where feedlots dominate, pastureland can account for 70% of a ranch’s total net worth. According to USDA data, the average value of U.S. farm real estate in 2023 hovered around $3,800 per acre, with prime grazing land in Montana or Wyoming fetching $5,000–$8,000 per acre. This isn’t just about soil quality; it’s about water rights, zoning laws, and proximity to feed markets. A single drought can slash land values by 30% overnight, as seen in 2012 when the Ogallala Aquifer depletion forced ranchers to sell off acreage at fire-sale prices. The catch? Land appreciation isn’t guaranteed. While corporate agribusinesses can leverage debt to expand, family operations often lack the liquidity to ride out downturns. This creates a wealth gap: the top 10% of beef-producing operations control roughly 70% of the nation’s cattle inventory, while small ranches—those with fewer than 500 head—struggle to pass land down to heirs due to inheritance taxes and development pressures.2. Corporate Processors Hold the Financial Leverage
When discussing beef production USA net worth, the conversation quickly turns to the "Four Horsemen"—Tyson Foods, Cargill, JBS, and National Beef. These companies don’t just slaughter cattle; they control the entire supply chain, from feed purchases to retail distribution. Their market dominance isn’t just about scale—it’s about vertical integration. Tyson, for example, owns everything from feed mills to food-service distribution, allowing it to dictate prices at every stage. In 2022, the combined revenue of these four firms exceeded $120 billion, with net profits often eclipsing $2 billion annually. This concentration of power has financial ripple effects. Independent ranchers often sign contracts locking in prices months before cattle are sold, leaving them vulnerable to processor buyouts or sudden market shifts. During the 2020 COVID-19 disruptions, when packing plants temporarily shut down, ranchers faced losses of $10,000–$20,000 per head due to unprocessed inventory. Meanwhile, the processors weathered the storm by pivoting to ground beef production for retail, underscoring their ability to absorb risk while shifting it downstream.3. Export Markets Are the Wild Card in Net Worth Calculations
The beef production USA net worth isn’t just about domestic consumption—it’s heavily influenced by global trade dynamics. The U.S. is the world’s second-largest beef exporter, with shipments to Japan, South Korea, and Mexico accounting for roughly 25% of total production. A single trade deal, like the USMCA, can add billions to industry valuations overnight. For instance, when Japan lifted its ban on U.S. beef imports in 2017 after lifting its mad cow disease restrictions, exports surged, boosting processor margins by 15–20%. Yet this reliance on foreign markets introduces volatility. Tariffs, disease outbreaks, or shifts in consumer preferences (like China’s pivot to pork) can decimate export revenues. In 2019, African Swine Fever in China created a temporary boom for U.S. beef exports, but the effect was short-lived. For ranchers, this means net worth isn’t just about herd size—it’s about geopolitical foresight. Those with contracts tied to specific export markets can see their assets appreciate during trade surges, while others face write-downs when demand dips.4. The Grass-Fed Premium Is Redefining Wealth Metrics
While conventional beef production focuses on maximizing yield, a subset of the industry is betting on premiumization. Grass-fed and organic beef now command prices 2–3 times higher than conventional cuts, with niche markets like Wagyu or dry-aged ribeyes fetching $50–$100 per pound at retail. This shift is altering the beef production USA net worth calculus: smaller operations with access to organic certification or pastureland can achieve profitability with far fewer head of cattle than industrial feedlots. The catch? Scaling this model is difficult. Certification costs, feed quality control, and limited processing capacity create barriers. Yet the trend is undeniable: sales of grass-fed beef grew by 40% between 2015 and 2020, driven by health-conscious millennials and sustainability concerns. For ranchers, this means diversifying revenue streams—some lease land to organic producers, while others partner with direct-to-consumer platforms like Crowd Cow or ButcherBox. The result? A two-tiered net worth system where land value alone no longer dictates success."Ten years ago, we sold cattle at auction. Now, 60% of our revenue comes from pre-sold contracts with restaurants and subscription boxes. The margin isn’t just about the animal—it’s about the story behind it." — James McCarthy, owner of McCarthy Family Farms (Colorado)
5. Climate and Regulation Are the Silent Wealth Eroders
No discussion of beef production USA net worth is complete without addressing external risks. Methane emissions from cattle have made the industry a target for carbon taxes and ESG investors. In 2021, California’s proposed $1.50 per head methane fee would have added $300 million in costs to the state’s beef sector alone. Meanwhile, water scarcity in the West—where 80% of U.S. cattle are raised—threatens grazing permits and feed production. A 2022 study by the USDA estimated that climate-related losses in the beef sector could reach $1.2 billion annually by 2030. Regulatory uncertainty compounds these risks. The USDA’s new "climate-smart" commodity programs offer subsidies for sustainable practices, but adoption requires upfront investment. Ranchers who fail to adapt may see their net worth stagnate while competitors who embrace precision agriculture or renewable energy credits gain a competitive edge. The message is clear: future beef production USA net worth will depend less on brute force and more on resilience to environmental and policy shocks.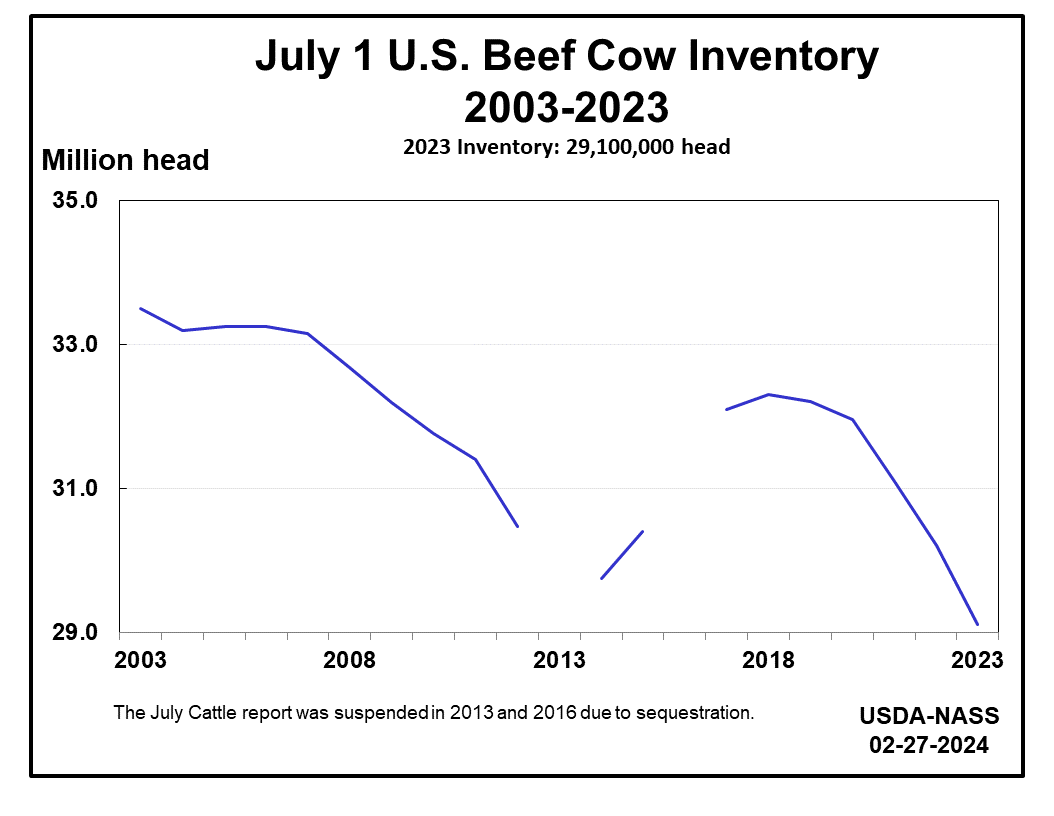
How These Facts Connect
The beef production USA net worth isn’t a static number—it’s a dynamic interplay of asset classes, market forces, and external pressures. Land values and corporate leverage form the backbone of traditional wealth, while export markets and premiumization represent growth opportunities. Yet climate risks and regulation act as wildcards, capable of reshaping the industry’s financial landscape overnight. The most successful operations today are those that balance these elements: leveraging scale where possible, diversifying revenue streams, and hedging against volatility. Consider the contrast between a 5,000-acre Texas feedlot and a 200-acre organic ranch in Vermont. The former’s net worth is tied to cattle inventory and feed contracts, while the latter’s depends on certification costs and direct consumer relationships. Both face climate risks, but their paths to adaptation differ. The feedlot might invest in methane-capture technology, while the organic ranch could pivot to agritourism. The key takeaway? Beef production USA net worth is no longer a one-size-fits-all metric. | Factor | Traditional Model | Premium/Niche Model | |--------------------------|-----------------------------------------------|---------------------------------------------| | Primary Asset | Land and cattle inventory | Certification and brand equity | | Revenue Streams | Auction sales, feed contracts | Direct-to-consumer, restaurant partnerships | | Biggest Risk | Feed costs, processor consolidation | Certification costs, market saturation | | Climate Adaptation | Methane reduction tech | Agrotourism, regenerative grazing | The table above illustrates how the industry’s financial DNA is splitting into distinct pathways. For investors, this means opportunities in both legacy agribusiness and disruptive protein alternatives. For ranchers, it’s a call to specialize—or risk obsolescence.
Conclusion
The beef production USA net worth story is one of contradictions: an industry that’s both a bastion of tradition and a proving ground for innovation. It’s a sector where family legacies collide with corporate efficiency, and where environmental stewardship can either erode or enhance financial health. The numbers don’t lie—this is a $100 billion industry with profound economic and cultural stakes—but they also don’t tell the whole story. Behind every balance sheet are real people making real choices: whether to expand into export markets, invest in sustainability, or hold onto land as a hedge against uncertainty. What’s clear is that the future of beef production USA net worth won’t belong to the largest players alone. It will belong to those who can navigate the tension between scale and specialization, between risk and resilience. The industry’s next chapter may well be written by ranchers who treat cattle not just as livestock, but as a financial instrument in a rapidly changing world.Comprehensive FAQs
Q: How much of the U.S. beef industry’s net worth is controlled by the top 10% of producers?
A: Industry estimates suggest the top 10% of beef-producing operations—those with 1,000+ head of cattle—control roughly 70% of the national cattle inventory. This concentration is driven by economies of scale in feed efficiency, processing contracts, and land ownership. Smaller operations (under 500 head) often struggle with debt service and passing land to heirs, further consolidating wealth at the top.
Q: Can a small rancher realistically build significant net worth in today’s market?
A: Yes, but it requires strategic diversification. While traditional models rely on land appreciation, smaller operations are increasingly turning to value-added products (grass-fed, grass-finished), agritourism, or direct-to-consumer sales. Success stories often involve partnerships with chefs, farmers’ markets, or online platforms. However, the barrier to entry remains high due to certification costs and limited processing capacity.
Q: How do trade policies (like tariffs) impact beef production USA net worth?
A: Trade policies can swing net worth by billions overnight. For example, when the U.S. imposed tariffs on Brazilian beef in 2018, U.S. exports to China surged, boosting processor margins by 15–20%. Conversely, retaliatory tariffs on U.S. beef have cost ranchers hundreds of millions in lost sales. The industry’s net worth is thus tied to geopolitical stability—ranchers with export contracts are particularly vulnerable to policy shifts.
Q: Are there any beef production sectors where net worth is growing faster than conventional models?
A: Yes. The fastest-growing segments are grass-fed/grass-finished beef (CAGR of ~12% annually) and halal-certified beef (driven by Muslim consumer demand). Lab-grown and plant-based alternatives are also encroaching on traditional net worth calculations, though they remain a small fraction of the $100B+ industry. For ranchers, the key is accessing these premium markets before consolidation reduces margins.
Q: What’s the biggest financial threat to beef production USA net worth in the next decade?
A: Climate-related risks—particularly water scarcity and regulatory pressure on methane emissions—pose the most systemic threat. Droughts in the Ogallala Aquifer region could reduce cattle inventories by 20% by 2035, while carbon pricing could add $0.50–$1.00 per pound to production costs. The industry’s ability to adapt through technology (e.g., feed efficiency tools) or policy lobbying will determine whether these risks become liabilities or opportunities.
Q: How do beef processors like Tyson or JBS maintain their dominance over ranchers?
A: Their power stems from vertical integration—owning feed mills, processing plants, and retail distribution channels—along with contractual leverage. Many ranchers sign forward contracts locking in prices months before cattle are sold, giving processors pricing control. During crises (like COVID-19 plant shutdowns), this structure allows them to absorb losses while shifting risk to suppliers. Independent ranchers often lack the bargaining power to renegotiate these terms.
Q: Can investing in beef production (e.g., buying cattle or land) still be profitable?
A: Historically, cattle have been a hedge against inflation, with land appreciating over time. However, profitability depends on timing and scale. Small investors may fare better by partnering with established ranchers or investing in beef REITs (like Cattlemen’s Beef REIT). Larger investors can leverage tax incentives for conservation easements or renewable energy credits on pastureland. The key is treating beef assets as a long-term play, not a speculative bet.
