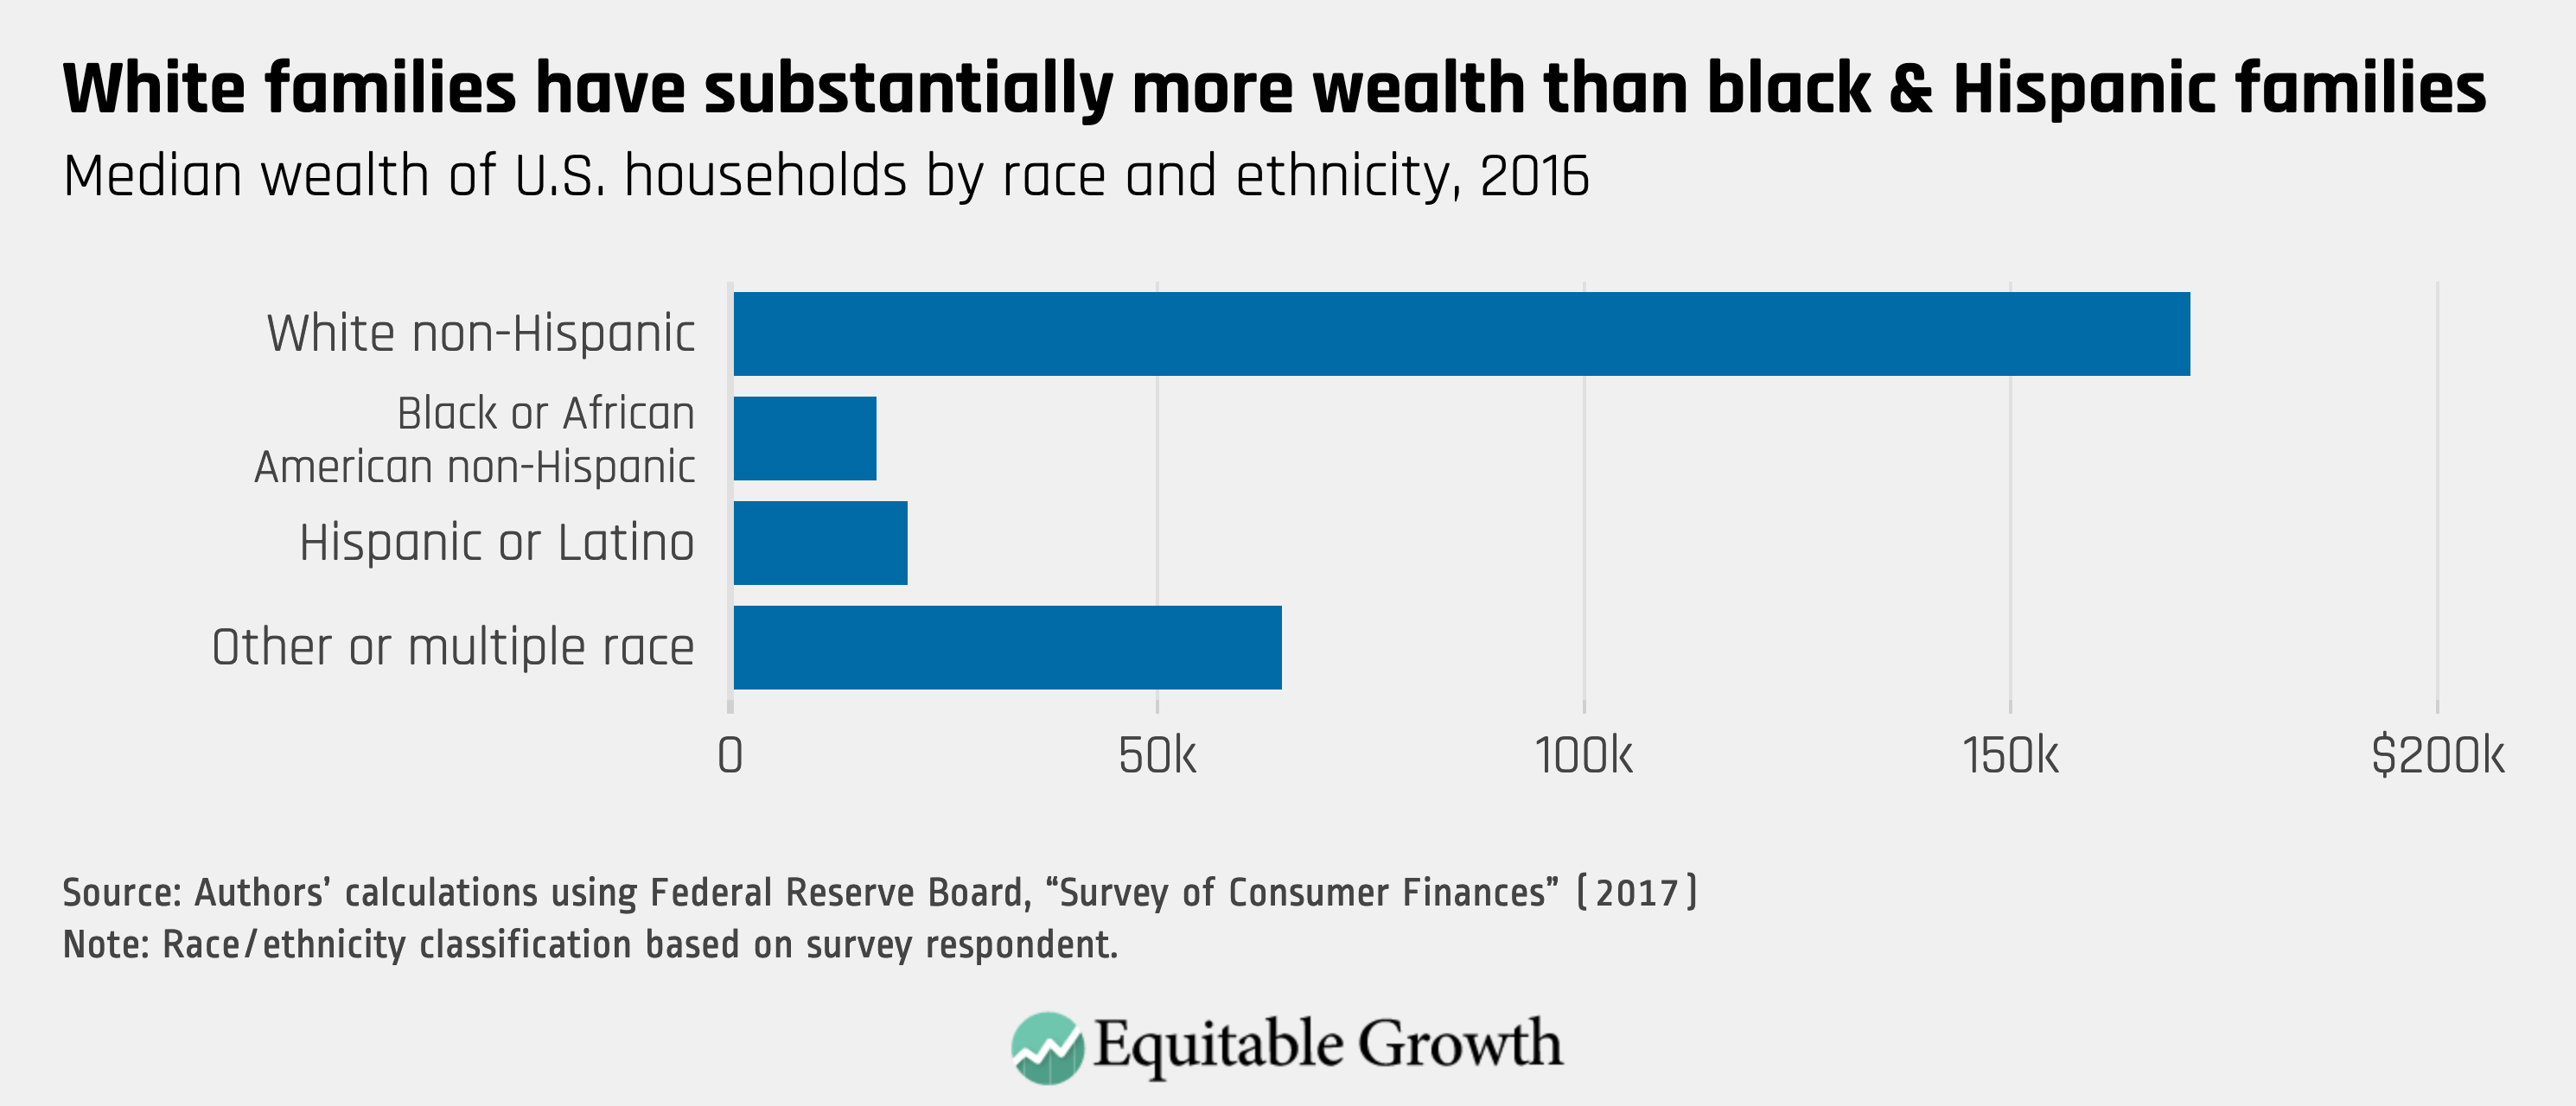
Where It All Began
The story of usa family net worth begins not with Wall Street but with the farm. In the early 20th century, most American families measured wealth in land, livestock, and tools. The Great Depression shattered that world, but it also forced a reckoning: financial security required more than self-sufficiency. The New Deal’s Social Security Act and the GI Bill of 1944 didn’t just provide aid—they created the infrastructure for wealth accumulation. Veterans who could afford college degrees entered professions that paid steadily, while homeownership rates soared. By the 1950s, the usa family net worth was rising faster than at any time in history, not because of speculative bets but because of stable employment, union protections, and a tax code that favored savings. The early signs of this shift were subtle but unmistakable. In 1945, the average American family had a net worth of around $48,000 in today’s dollars—mostly tied up in homes and farms. By 1960, that figure had doubled. The key driver wasn’t stock market gains but the usa family net worth effect of compounding assets: a home purchased in 1950 could be sold in 1960 for twice its original value, thanks to suburban expansion. Pensions and 401(k)s were still rare, but employer-sponsored retirement plans were emerging, and the idea that ordinary workers could build generational wealth was becoming mainstream. The post-war economy wasn’t just creating jobs; it was creating usa family net worth in ways that previous generations couldn’t have imagined.The Early Signs
The first red flags appeared in the 1970s, when inflation outpaced wage growth. Families who had relied on steady increases in take-home pay found themselves stretched thin. The usa family net worth that had grown effortlessly in the 1950s now required active management—budgeting, side hustles, even second incomes. The shift from manufacturing to service jobs meant fewer union protections and more precarious employment. By the 1980s, the usa family net worth gap between white-collar and blue-collar households was widening, not because of policy but because of structural changes in the economy. The Reagan era accelerated these trends. Tax cuts favored the wealthy, and deregulation allowed financial institutions to take bigger risks—risks that would later be borne by ordinary families. The usa family net worth of the top 1% soared, but for the bottom 90%, the gains were modest at best. The 1980s also saw the rise of consumer debt as a way to maintain lifestyles that wages couldn’t support. Credit cards, home equity loans, and student debt became tools for bridging the gap between ambition and reality. The usa family net worth figures that had once been a source of pride now carried the weight of obligation.The Turning Point
The 1990s brought a false dawn. The dot-com boom inflated asset prices, and for a moment, it seemed the usa family net worth could rise indefinitely. Stock ownership became democratized, with employers offering 401(k) matches and mutual funds becoming household names. The median usa family net worth hit record highs, and for the first time, many families felt financially secure. But the bubble was built on speculation, not fundamentals. When it burst in 2000, the fallout was sharp but contained—until 2008. The Great Recession was the turning point. The collapse of the housing market didn’t just destroy homes; it wiped out decades of usa family net worth for millions. Retirement accounts shrank, home values plunged, and for the first time since the Depression, a generation saw its financial future called into question. The recovery that followed was slow and uneven. While the stock market rebounded, wages stagnated, and the usa family net worth gap yawned wider than ever. The era of shared prosperity had ended, replaced by one where wealth accumulation depended less on hard work and more on luck—inheritance, timing, or access to capital."Wealth isn’t just about money. It’s about who gets to play by the rules—and who gets left out." — Rachel Sherman, sociologist and author of Uneasy Street

The Build-Up, Year by Year
| Period | What Happened |
|---|---|
| 1945–1960 | Post-war boom lifts usa family net worth via homeownership, pensions, and wage growth. The median household wealth doubles. |
| 1970s–1980s | Stagflation and deregulation slow growth. The usa family net worth gap widens as top earners benefit from tax cuts and financialization. | 1990s | Dot-com boom inflates asset prices, pushing usa family net worth higher—but the crash exposes vulnerabilities. |
| 2008–Present | Great Recession devastates usa family net worth, particularly for minorities and lower-income households. Recovery favors asset owners. |
Lessons From the Journey
- Wealth isn’t just income. The usa family net worth of a family earning $70,000 can vary wildly based on debt, home equity, and inheritance.
- Policy matters more than personal effort. Tax breaks for the wealthy in the 1980s didn’t just benefit the rich—they reshaped the usa family net worth landscape for decades.
- Crisis reveals inequalities. The 2008 crash didn’t just hurt homeowners—it exposed how racial wealth gaps persist across generations.
- Asset ownership is the new security. In the 21st century, usa family net worth depends less on stable jobs and more on stocks, real estate, and education.
Where Things Stand Today
As of 2023, the median usa family net worth stands at roughly $188,000, according to Federal Reserve data—but the numbers tell only part of the story. The top 10% hold nearly 70% of the wealth, while the bottom 50% own just 2.6%. The pandemic exacerbated these divides: stimulus checks and remote work boosted asset prices for those who owned stocks or property, while renters and gig workers saw little change in their usa family net worth. The current economy is a paradox—record-low unemployment coexists with record-high inequality. The conversation around usa family net worth today is less about averages and more about access. Who gets to inherit? Who can afford a down payment? Who has the time to invest? The answer isn’t just about personal responsibility—it’s about systemic barriers. Student debt, healthcare costs, and stagnant wages have made it harder for younger generations to build usa family net worth at the same rate as their parents. The American Dream isn’t dead, but it’s no longer a guarantee.
Conclusion
The history of usa family net worth is a story of cycles—booms and busts, inclusion and exclusion. What’s clear is that wealth isn’t static; it’s shaped by policy, luck, and the choices of those in power. The families who thrived in the 1950s did so because the system was designed to reward them. Today, that system is broken for many. The question isn’t whether the usa family net worth can rise again—it’s whether the next generation will have the same opportunities as the last. The data tells one story. The lived experience tells another. Bridging that gap won’t happen with more spreadsheets or tax cuts. It’ll require a reckoning with how wealth is created—and who gets to share in it.Comprehensive FAQs
Q: How does the usa family net worth compare to other developed nations?
The U.S. has one of the highest median usa family net worth figures among developed nations, but the gap between rich and poor is wider than in most European countries. For example, Sweden’s wealth distribution is more equal, with less concentration in the top 1%. However, the U.S. leads in absolute wealth due to higher asset ownership (stocks, real estate) and lower taxes on capital gains.
Q: Why do some families struggle to build usa family net worth even when they earn decent salaries?
Several factors play a role: high student debt, healthcare costs, stagnant wages, and the cost of housing. Many families spend more on essentials than they can save, while others face barriers like lack of access to credit or family wealth to leverage. The usa family net worth gap is also racial—Black and Hispanic families typically have far less wealth than white families, even at similar income levels.
Q: How does homeownership affect usa family net worth?
Homeownership is the single biggest driver of usa family net worth in the U.S. A home isn’t just shelter—it’s an asset that appreciates over time. Families who own homes build equity, which can be tapped for retirement or emergencies. Renters, meanwhile, pay money that doesn’t contribute to long-term wealth. The 2008 crash showed how vulnerable homeowners can be to market downturns, but historically, real estate remains the best wealth-building tool for most Americans.
Q: Are there policies that could improve usa family net worth for struggling families?
Yes. Expanded child tax credits, student debt relief, and stronger labor protections could help. Some economists argue for wealth taxes or inheritance reforms to reduce inequality. Others push for housing policies that make homeownership more accessible. The key is addressing structural issues—like the racial wealth gap—that prevent families from accumulating assets in the first place.
Q: How does the usa family net worth differ between generations?
Baby Boomers entered a strong economy with rising wages and home values, allowing them to build significant usa family net worth. Gen X saw slower growth due to stagflation and the 2000 crash. Millennials and Gen Z face higher costs (housing, education) and stagnant wages, making it harder to accumulate wealth at the same rate. The usa family net worth of younger generations is also more volatile, tied to stock market performance and gig economy instability.
