
Breaking Down the Numbers
The most cited benchmark for what is the median net worth of a 50-year-old comes from the Federal Reserve’s triennial Survey of Consumer Finances (SCF). As of the 2022 report—the most recent available—the median net worth for households headed by someone aged 45–54 was $255,000. This figure includes all assets—primary residences, investments, business equity—and subtracts liabilities like mortgages and student loans. For context, the median net worth for all U.S. households was $120,000 in the same period, underscoring how wealth typically accelerates in one’s 40s and 50s. But this median masks critical variations. A single homeowner in a high-cost metro area could see net worth in the $500,000–$800,000 range, while a renter with no retirement savings might struggle to reach $50,000. The SCF also reveals that 40% of households in this age group have no retirement account balances whatsoever, a figure that jumps to 60% for those with incomes under $40,000. This isn’t just a wealth gap—it’s a retirement gap, with profound implications for Social Security dependency in later years.The Verified Baseline
The Federal Reserve’s data is the only nationally representative source for these figures, but it has limitations. The SCF relies on self-reported data, which may understate debt or overstate assets. Additionally, the survey excludes military households and some rural populations, potentially skewing results. Despite these caveats, the 2022 median of $255,000 for 45–54-year-olds aligns with trends from the Pew Research Center, which tracks wealth accumulation over time. What’s less discussed is the debt burden at this stage. The median net worth figure assumes liabilities are already managed, but for many, credit card debt or co-signed loans persist well into middle age. A 2023 Urban Institute analysis found that one in five 50-year-olds carries non-mortgage debt, often due to medical expenses or caregiving costs. This debt erodes the headline net worth number, sometimes by 20–30%. The verified baseline, then, isn’t just about assets—it’s about the net position after accounting for obligations that don’t disappear with age.What the Estimates Suggest
Beyond the SCF, industry estimates paint a nuanced picture. The wealth management firm Spectrem Group suggests that high-net-worth individuals (HNWIs) at 50—those with investable assets over $1 million—represent about 5% of this demographic. For the remaining 95%, net worth clusters around three tiers: 1. Homeowners with modest investments: Estimated at $200,000–$400,000, depending on location. 2. Dual-income households with retirement savings: Figures around the $400,000–$700,000 range, assuming consistent 401(k) contributions. 3. Single earners or those with student debt: Often below $150,000, with some dipping into negative net worth if debt exceeds assets. These estimates align with regional data. In states like Massachusetts or Maryland, where home values and education costs are high, the median net worth for 50-year-olds can exceed $350,000. In contrast, states like Mississippi or West Virginia see medians closer to $150,000–$200,000. The estimates also reflect the gender wealth gap: Women at 50 hold 30% less median net worth than men, largely due to career interruptions and longer lifespans.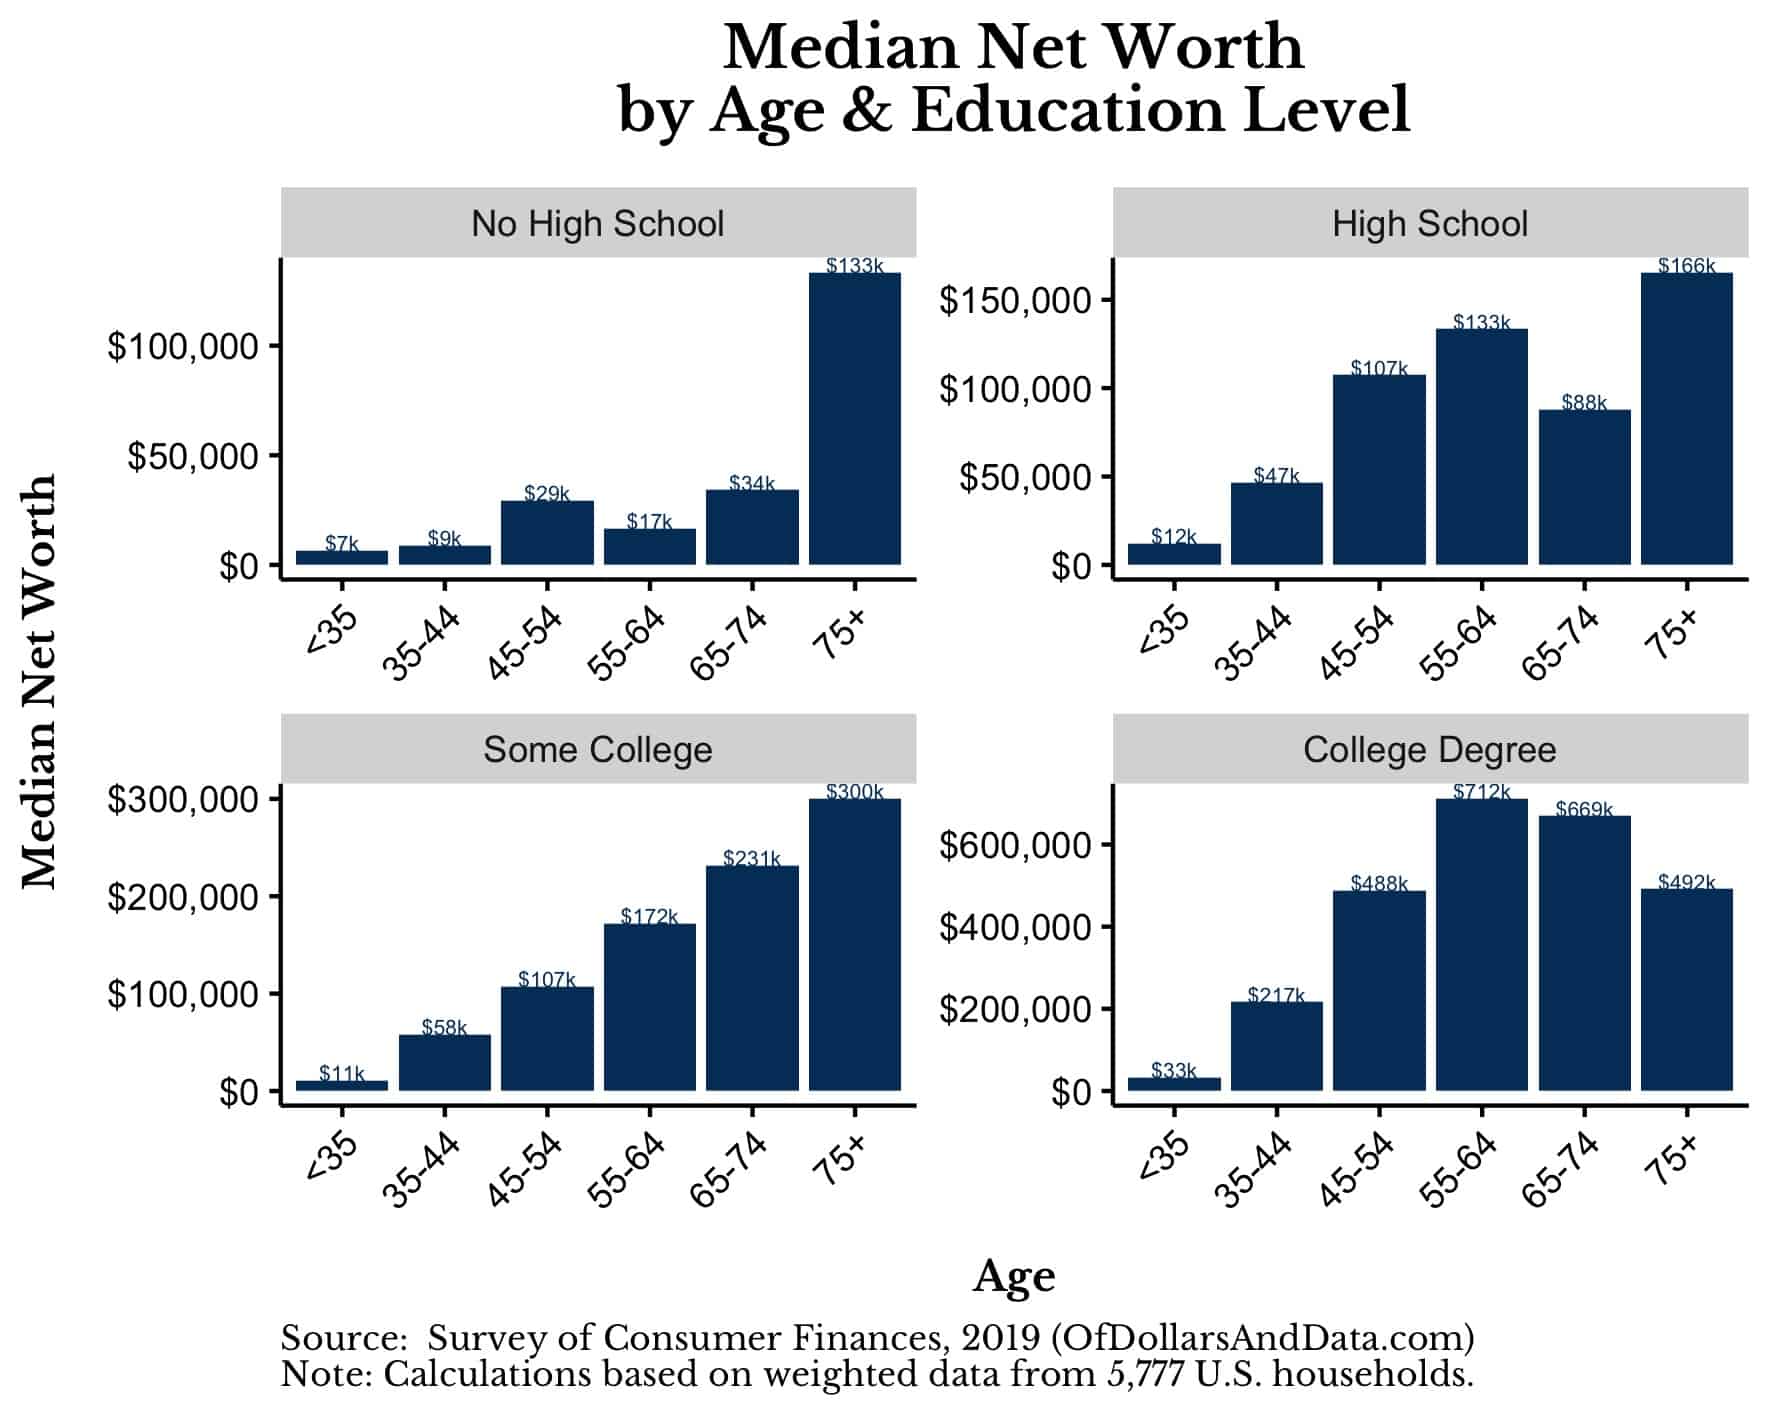
Case Study: A Closer Look
Consider the case of a 50-year-old teacher in Atlanta with a $300,000 home, $50,000 in a 401(k), and $20,000 in student loans. Their net worth—$330,000—places them above the national median, but their liquidity is constrained. A sudden job loss or medical bill could force them to tap home equity, a risk that persists even at this stage. This scenario highlights how what is the median net worth of a 50-year-old doesn’t account for vulnerability. The teacher’s situation also illustrates the role of opportunity cost. Had they invested aggressively in the 1990s or 2000s, their net worth might now be double. Instead, they prioritized stability—paying off loans, saving for college tuition, and avoiding market volatility. This trade-off is common, but it underscores a harsh truth: median wealth at 50 is less about income and more about timing and risk tolerance. > "You can’t out-earn bad decisions, but you can outlast them." —Financial planner based in Dallas, analyzing client portfolios for 20 years | Factor | Estimated Impact on Net Worth | |--------------------------|--------------------------------------------------------------------------------------------------| | Homeownership | +$200,000–$400,000 (varies by market; equity builds over 25+ years) | | Retirement contributions | +$100,000–$300,000 (assuming 7% annual return; early contributions compound significantly) | | Student debt | –$20,000–$100,000+ (repayment timelines extend into 50s for many) | | Caregiving expenses | –$50,000–$200,000 (unplanned costs for aging parents or dependents) |What This Means Going Forward
For those at or near the median, the next decade is critical. The 401(k) to IRA rollover window opens at 59½, but RMDs (required minimum distributions) begin at 73, forcing taxable withdrawals. A 50-year-old with $500,000 in retirement accounts could see $20,000–$40,000 in annual RMDs by 2034, altering their tax bracket. Planning for this shift—whether through Roth conversions or charitable giving—can mean the difference between comfort and financial strain. The median net worth at 50 also sets expectations for legacy planning. Many in this age group become caregivers for aging parents while supporting adult children, a sandwich generation dynamic that depletes assets faster than anticipated. Studies show that 30% of 50-year-olds provide financial support to both parents and children, often without adjusting their own retirement timelines. This intergenerational transfer, while noble, can reduce net worth by 15–25% over five years if unmanaged.
Conclusion
The median net worth of a 50-year-old is more than a number—it’s a reflection of economic participation, policy outcomes, and personal agency. The $255,000 figure from the Federal Reserve is a starting point, not a destination. For some, it’s a launchpad for early retirement; for others, it’s a precarious foundation. What’s clear is that wealth at this stage is rarely passive; it’s the result of navigating housing booms, recessions, and shifting employer benefits. The data also exposes uncomfortable truths. The median obscures racial wealth gaps, the gender pay gap’s compounding effect, and the fact that one-third of 50-year-olds have no emergency savings. As life expectancy rises, the question isn’t just what is the median net worth of a 50-year-old, but whether it’s enough to sustain 20–30 more years of financial independence. The answer depends less on age and more on adaptability—something no survey can measure.Comprehensive FAQs
Q: How does divorce affect the median net worth of a 50-year-old?
The median net worth for divorced individuals at 50 drops by 40–50% compared to married peers, according to the National Bureau of Economic Research. This reflects asset division, alimony payments, and the loss of dual-income stability. Women, in particular, see median net worth fall by 60% post-divorce, often due to unequal splits in homes or pensions.
Q: Can I increase my net worth significantly between 50 and 60?
Yes, but the strategies shift. The most effective levers are home equity conversion (HECM loans), downsizing to invest the difference, and tax-efficient withdrawals from retirement accounts. For those with high-earning potential, consulting or freelance work can add $100,000–$300,000 over a decade. However, market risk increases—timing a real estate sale or stock market entry becomes more critical.
Q: Why do some 50-year-olds have negative net worth?
Negative net worth at this age typically stems from student debt, medical bankruptcy, or predatory lending. A 2023 Federal Reserve study found that 8% of 45–54-year-olds have liabilities exceeding assets, often due to co-signed loans for adult children or reverse mortgages taken out to cover healthcare costs. Unlike younger borrowers, defaults at this stage can’t be reset with time—Social Security benefits may be garnished.
Q: How does location impact the median net worth of a 50-year-old?
Location matters more than income. In high-cost coastal cities (e.g., San Francisco, NYC), the median net worth for 50-year-olds can exceed $400,000 due to home equity, but liquid assets may be lower after housing costs. In rural or low-cost states (e.g., Iowa, Ohio), the median might be $150,000–$200,000, but retirees face lower healthcare costs and property taxes. The "wealth premium" of urban living doesn’t always translate to financial security.
Q: What’s the biggest mistake people make with their net worth at 50?
Assuming they’ve "made it." The most common error is underestimating longevity risk—the chance of outliving savings. A 50-year-old with $500,000 in assets has a 30% chance of depleting those funds before age 85, per Society of Actuaries projections. Others overlook long-term care insurance or fail to adjust their portfolio for lower risk tolerance as they near retirement. The median net worth at 50 is a milestone, not a finish line.
