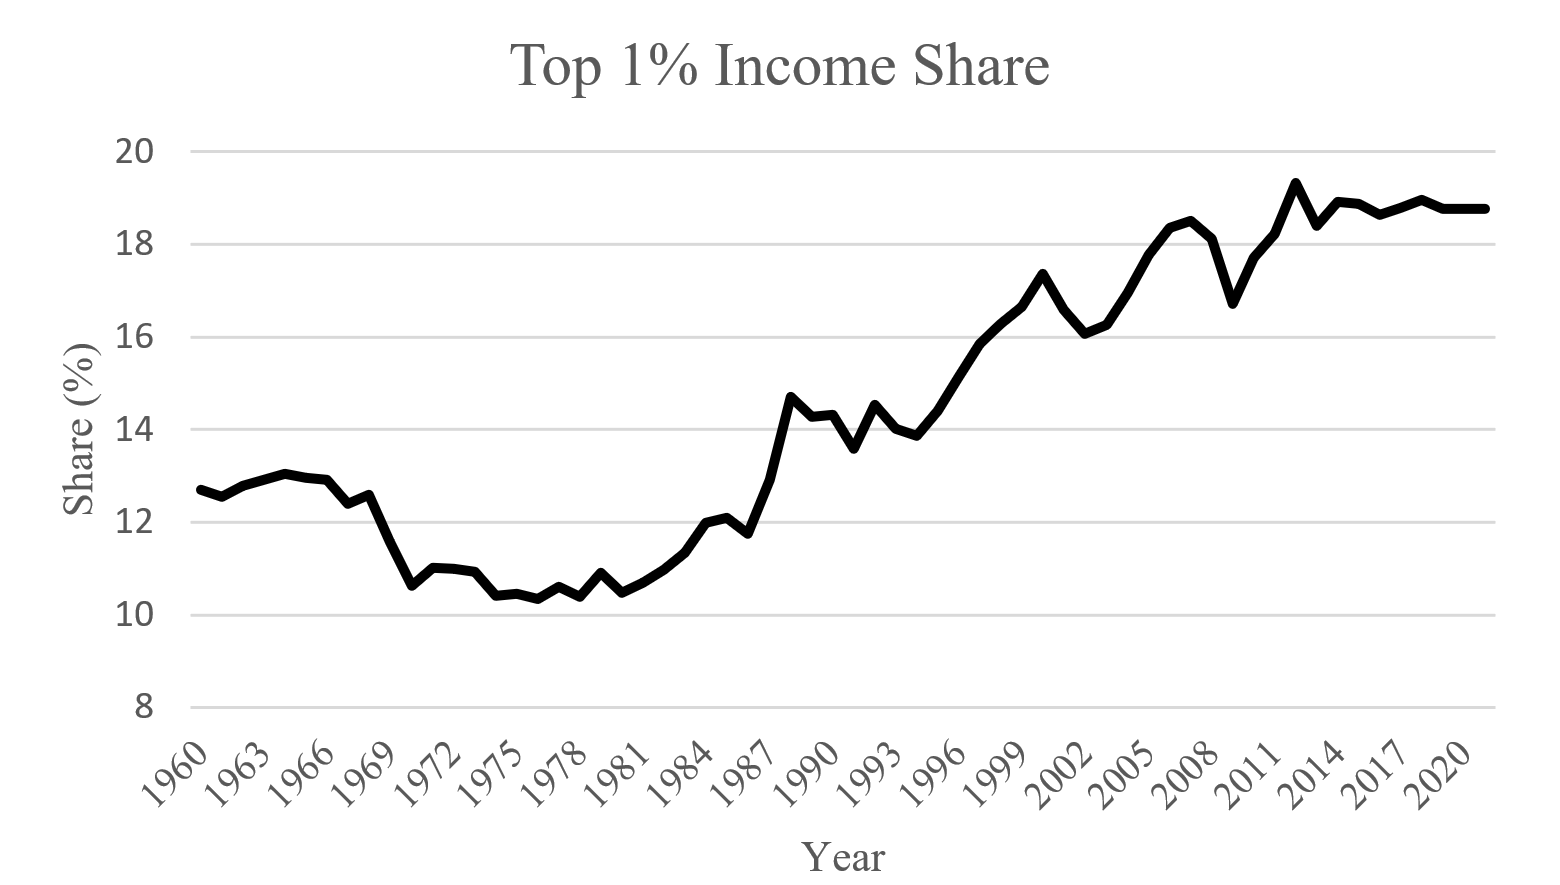
Breaking Down the Numbers
The top 1 percent income of 30 year olds net worth isn’t a fixed benchmark, but a moving target shaped by geography, inflation, and the cost of living. In the U.S., for example, the threshold for a 30-year-old to be in the top 1% of net worth is estimated to start around $2.5 million, though this figure varies by city—San Francisco or New York push it higher, while lower-cost regions like Dallas or Austin may lower the bar slightly. Income-wise, the cutoff is more volatile: a 30-year-old earning $350,000+ annually from a combination of salary, bonuses, and passive income is likely in the top decile, but net worth tells a different story. The disconnect arises because wealth accumulation at this age is less about steady paychecks and more about leverage: real estate, private equity, or early-stage venture stakes that appreciate exponentially. The data becomes murkier when examining global comparisons. In London, a 30-year-old with a net worth of £1.8 million–£2.5 million might qualify for top-tier tax brackets and elite social circles, while in Singapore or Hong Kong, the threshold could be $3 million–$5 million due to higher asset prices. What’s consistent across markets is the role of illiquid assets. A 30-year-old software engineer with a $200,000 salary may not crack the top 1%, but the same engineer who co-founded a SaaS company—even if it’s pre-profit—could see their net worth skyrocket overnight if they secure a strategic acquisition. The key variable isn’t just income, but asset velocity: how quickly capital can be reinvested into higher-yielding opportunities.The Verified Baseline
Publicly available data on the top 1 percent income of 30 year olds net worth is scarce, but a few sources provide anchor points. The Federal Reserve’s Survey of Consumer Finances (SCF) offers snapshots, though it lags by years. For 30-year-olds in 2022, the median net worth was $110,000, while the 90th percentile sat at $1.2 million. The top 1% threshold isn’t explicitly broken out by age, but extrapolating from broader wealth distribution studies suggests that by 30, the top 1% net worth begins at roughly $2.5 million–$3 million, depending on household structure. Income data from the IRS’s Statistics of Income (SOI) shows that 30-year-olds in the top 1% of adjusted gross income (AGI) earn $300,000+, but this includes capital gains, which can distort the picture. The most reliable proxies come from high-net-worth databases like Wealth-X or Credit Suisse’s Global Wealth Report. These sources confirm that by age 30, individuals in the top 1% of wealth typically hold multiple income streams: a primary job (often in finance, tech, or healthcare), equity stakes in private companies, and real estate holdings. The Forbes 30 Under 30 list provides case studies, though it skews toward entrepreneurs and celebrities. A 2023 analysis of the list found that while some entrants had $10 million+ net worth, others—like quant traders or niche consultants—reached $1 million–$5 million through specialized skills. The pattern is clear: liquidity isn’t the goal; asset appreciation and tax-efficient structuring are.What the Estimates Suggest
Industry estimates paint a picture where the top 1 percent income of 30 year olds net worth is less about traditional employment and more about high-concentration risk. Private equity analysts at top firms (e.g., Blackstone, KKR) may earn $500,000–$1 million base + carry, pushing their net worth into the $3 million–$10 million range by 30 if they’ve been with the firm since their 20s. Similarly, early-stage venture capitalists or angel investors who back unicorns before IPOs can see their portfolios balloon—though the downside risk is severe. A 2022 report by UBS and PwC suggested that 30% of ultra-high-net-worth individuals under 35 had $30 million+ in assets, primarily from family offices, crypto holdings, or inherited wealth. However, these figures are self-reported and prone to exaggeration. The most speculative—but plausible—estimates come from compensation data in niche fields. For instance, a top-tier hedge fund analyst might earn $250,000–$400,000 by 30, but with performance bonuses and carried interest, their net worth could exceed $5 million if they’ve been in the business for a decade. In tech, a former FAANG engineer who pivoted to AI startups might see their equity vesting hit $10 million+ if their company is acquired. The common thread? Accelerated compounding. A 30-year-old with $1 million in net worth who reinvests aggressively in assets with 15–20% annualized returns (private equity, venture, or real estate) can double their wealth every 4–5 years. The challenge isn’t earning the money; it’s preserving and scaling it before traditional markets catch up.
Case Study: A Closer Look
Take the example of a quantitative researcher who joined a proprietary trading firm at 25. By 30, they’ve transitioned from trading algorithms to managing a $500 million hedge fund. Their salary alone—$800,000 base + 20% carry—puts them in the top 0.1% of earners for their age. But their net worth isn’t just tied to their paycheck. They’ve been allocating 30% of their income into: - Private credit deals (illiquid, high-yield loans to businesses) - Pre-IPO equity in fintech startups - Commercial real estate in secondary markets (where yields exceed 8%) Their estimated net worth by 30? $12 million–$18 million, though much of it is illiquid. The trade-off? Liquidity risk and the need to hold assets for 5–10 years to realize gains. Their strategy relies on asymmetric bet placement: small upfront capital for outsized potential returns, with stop-losses in place to limit downside."The difference between a six-figure earner and a nine-figure net-worth individual at 30 isn’t just how much they make—it’s how they deploy capital before it becomes someone else’s problem." — Former Blackstone principal (anonymized)
| Factor | Estimated Impact on Net Worth |
|---|---|
| Carried Interest (Hedge Fund) | Adds $3 million–$8 million over 5 years if fund outperforms benchmarks. |
| Private Equity Stakes | Early investments in $100K–$500K can become $5M–$20M if exited via acquisition. |
| Tax Optimization (Offshore Structures) | Reduces effective tax rate by 15–25%, preserving $1M–$3M in capital gains. |
What This Means Going Forward
For the average professional, the top 1 percent income of 30 year olds net worth serves as a warning and an aspiration. The warning: the path isn’t linear. It requires specialized skills, network access, and a tolerance for illiquidity. The aspiration: if structured correctly, even a $150,000 salary can become a $10 million net worth in a decade with the right leverage. The barrier isn’t intelligence—it’s opportunity cost. Every dollar spent on rent, student loans, or consumer goods is a dollar not compounding in assets. The bigger trend is the fragmentation of wealth accumulation. In the past, the top 1% at 30 were almost exclusively heirs, entrepreneurs, or Wall Street insiders. Today, crypto traders, AI consultants, and even YouTube ad arbitrageurs can crack the threshold if they hit a home run. The risk? Volatility. A single bad bet—whether in a failed startup or a crypto winter—can wipe out years of gains. The resilience of this cohort isn’t just financial; it’s psychological. They treat wealth like a scalable business, not a static number.
Conclusion
The top 1 percent income of 30 year olds net worth isn’t a mystery—it’s a system. It rewards those who understand that income is a means, not an end. The most successful 30-year-olds in the top 1% don’t chase titles; they chase asset multipliers. Whether it’s through equity stakes, high-conviction bets, or tax-efficient structures, their playbook is the same: convert labor into capital, then let capital do the work. The takeaway for outsiders isn’t to copy their strategies—most require insider access or risk tolerance beyond the average. Instead, it’s to recognize that wealth at this scale is a product of environment as much as effort. A 30-year-old in Silicon Valley has a different playing field than one in Detroit. The goal isn’t to become a millionaire by 30; it’s to design a system where wealth compounds automatically. For the rest, the lesson is simpler: start early, reinvest aggressively, and avoid lifestyle inflation. The top 1% didn’t get there by accident—they got there by playing by different rules.Comprehensive FAQs
Q: What’s the fastest way for a 30-year-old to reach the top 1% net worth?
A: The fastest paths typically involve high-leverage opportunities: founding or joining a scalable business (tech, SaaS, or niche consulting), securing equity in a high-growth industry, or entering high-income professions (quant trading, private equity, or specialized medicine). Inheritance or strategic marriages also accelerate the process, but asset-based growth (real estate, private equity) is the most reliable for most. Timing matters—entering a field before it peaks (e.g., AI in 2015 vs. 2025) can mean the difference between $1M and $10M by 30.
Q: Is a $200,000 salary enough to join the top 1% net worth by 30?
A: No, not on its own. A $200,000 salary is solid for middle-class accumulation, but breaking into the top 1% requires additional income streams or asset appreciation. For example, a software engineer earning $200K could reach $1M–$2M net worth by 30 if they reinvest bonuses into stocks, real estate, or a side business. However, to hit $2.5M+, they’d need equity stakes, carried interest, or a successful exit from a startup. The math only works if >70% of income is deployed into appreciating assets.
Q: Do most top 1% 30-year-olds come from wealthy families?
A: No, but a significant portion have family advantages. Studies suggest that ~40% of ultra-high-net-worth individuals under 35 have some form of inherited wealth or family connections (e.g., parents in finance, real estate, or entrepreneurship). However, 60%+ built their wealth independently through high-income skills, early career moves, or lucky breaks. The key difference? Access to capital. A 30-year-old with a wealthy parent can leverage credit or angel investments to scale faster, but self-made top 1% earners often over-index in tech, finance, or high-margin trades where leverage is available.
Q: What’s the biggest mistake 30-year-olds make when trying to build wealth?
A: Lifestyle inflation and lack of asset diversification. Many high earners spend like their income matches their net worth—buying luxury cars, expensive homes, or funding lavish social lives—only to realize they’ve no liquid savings or appreciating assets. The second mistake is over-concentration: putting 80% of net worth into a single stock, business, or real estate deal. The top 1% at 30 balance risk: they hold cash reserves, diversified equities, and high-growth illiquid assets simultaneously. The third? Not starting early enough. Compound interest favors those who begin deploying capital in their 20s, not 30.
Q: Can someone in a non-tech, non-finance field reach the top 1% net worth by 30?
A: Yes, but it requires extreme specialization or high-margin work. Fields like orthopedic surgery, patent law, or niche consulting (e.g., M&A advisory for biotech) can generate $500K–$1M+ incomes by 30, especially with partnership tracks or equity ownership. Even in non-finance roles, professionals who monetize expertise—such as high-end coaches, authors, or influencers—can build $1M–$5M net worth through digital assets, royalties, or course sales. The common thread? Scalable income streams that aren’t tied to hourly rates.
Q: How do taxes affect the net worth of top 1% 30-year-olds?
A: Taxes are the silent wealth killer for high earners. A 30-year-old with $500K in capital gains could owe $100K–$200K in taxes if not structured properly. The top 1% mitigate this through: - Tax-loss harvesting (offsetting gains with losses) - Qualified Small Business Stock (QSBS) exemptions (up to $10M in gains tax-free) - Offshore trusts or private placement life insurance (PPLI) (for ultra-high-net-worth individuals) - Real estate depreciation and 1031 exchanges (deferring capital gains) The most aggressive use a mix of C-corps, LLCs, and foreign entities to reduce effective tax rates to <20% on investment income. The IRS scrutinizes these strategies, so compliance is critical.
Q: What’s the most underrated asset class for 30-year-olds targeting top 1% net worth?
A: Private credit and direct lending. While stocks and real estate dominate discussions, private credit—lending to businesses at 8–12% yields—is illiquid, high-yield, and uncorrelated to public markets. Platforms like Cadre, Fundrise, or direct angel investing allow 30-year-olds to deploy $50K–$500K into loans or equity with asymmetric upside. Another underrated play? Collectibles with provenance (rare art, wine, or trading cards), which can appreciate 10–30% annually if curated properly. The catch? Liquidity risk—these assets can’t be sold quickly, making them ideal for long-term holders.
