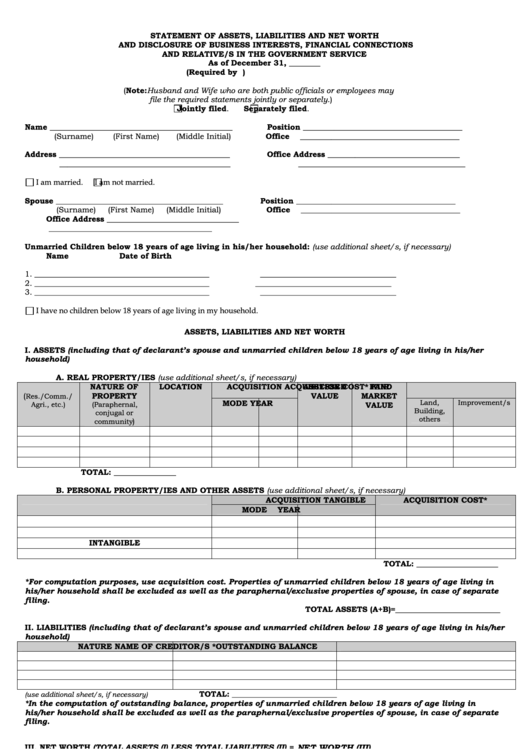
The Complete Overview of the 2018 Statement of Assets, Liabilities and Net Worth
The statement of assets, liabilities and net worth 2018 functioned as a dual-purpose document: a compliance tool and a strategic asset. For individuals subject to Schedule 7 filings in the UK or FBAR requirements in the US, it was a legal obligation with teeth. For others, it was a private ledger—one that could be used to secure loans, negotiate settlements, or even influence political narratives. The year 2018 was particularly notable for the way these statements intersected with geopolitical events. The Panama Papers fallout had already forced some to recalibrate their offshore structures, while the Common Reporting Standard (CRS) began exchanging data between jurisdictions, making evasion harder but not impossible. Yet the real story lay in the net worth calculations themselves. Valuations in 2018 were a moving target. Bitcoin’s price swung from $20,000 to $3,200 within months, forcing filers to choose between fair-market valuations and cost-basis reporting. Meanwhile, commercial real estate in London and New York saw sharp corrections, leaving some property portfolios suddenly less liquid than their appraisals suggested. The liabilities section became equally revealing—debts taken on to acquire assets during the 2016-2017 rally now looked riskier, and leverage ratios that had seemed prudent in hindsight appeared reckless. For the first time, many filers faced the prospect of their statement of assets and liabilities being used not just for tax purposes, but as a lens into their financial resilience. The 2018 statement of assets, liabilities and net worth also exposed a quiet revolution in wealth tracking. Firms like Wealth-X and Forbes began publishing more granular data on ultra-high-net-worth individuals (UHNWIs), while fintech tools like YNAB and Mint made basic net worth tracking accessible to the middle class. The disparity between these two worlds—where a billionaire’s offshore entities might be valued in broad strokes, while a small-business owner’s equipment depreciation was itemized down to the cent—highlighted a systemic issue: transparency was a privilege, not a standard.Historical Background and Evolution
The modern statement of assets, liabilities and net worth traces its roots to the Tax Reform Act of 1986, which introduced Schedule M in the US and forced individuals to reconcile income with actual cash flow. But 2018 marked a turning point. The Cayman Islands’ decision to join the CRS in 2017 meant that even traditionally opaque jurisdictions were now sharing data with 100+ countries. For the first time, a liabilities and net worth statement filed in Switzerland could indirectly influence an audit in Singapore. This global synchronization turned what had been a fragmented system into a web of interconnected disclosures. Domestically, the UK’s 2016 Offshore Accounts Disclosure Facility had already prompted thousands to come forward, but 2018 was the year enforcement became proactive. HMRC began cross-referencing statement of assets and liabilities filings with beneficial ownership registers, making it harder to hide behind nominee structures. The result? A net worth statement that wasn’t just a snapshot, but a potential red flag. For example, a sudden spike in cash holdings without corresponding income could trigger a Money Laundering Reporting Officer (MLRO) review. The era of passive compliance was over.Core Mechanisms: How It Works
At its core, the 2018 statement of assets, liabilities and net worth followed a deceptively simple framework: what you own, what you owe, and what remains. But the devil was in the details. Assets were categorized into tangible (property, vehicles), intangible (intellectual property, goodwill), financial (cash, securities), and cryptocurrency—a new addition that forced filers to grapple with volatility. Liabilities, meanwhile, included secured debts (mortgages, loans), unsecured debts (credit cards, personal loans), and contingent liabilities (guarantees, legal judgments). The net worth figure emerged from the difference, but the real work lay in valuation methodologies. For publicly traded stocks, market value was straightforward. For private businesses, discount rates and control premiums became contentious. Real estate appraisals could vary by 20% depending on the valuer. And then there were the offshore entities—where a statement of assets and liabilities might list a Panamanian shell company with a single line item: "Investment in subsidiary, valuation per independent report: $X." The lack of granularity here was deliberate, but it also made the document ripe for interpretation. Tax authorities, creditors, and ex-spouses all read these statements differently, and 2018 saw an uptick in disputes over net worth calculations in divorce cases.Key Benefits and Crucial Impact
The statement of assets, liabilities and net worth 2018 served as more than a compliance exercise—it was a financial passport. For high-net-worth individuals, it determined eligibility for private banking tiers, insurance underwriting, and even political candidacy. A clean net worth statement could unlock elite club memberships; a flawed one might trigger due diligence that led to asset freezes. Meanwhile, for businesses, these statements became critical in M&A due diligence, where a buyer’s statement of assets and liabilities could make or break a deal. The psychological impact was equally significant. Filing a liabilities and net worth statement forced individuals to confront their financial reality in a way few other documents did. A tech founder might realize their restricted stock units were suddenly worth less after a funding round collapse. A trustee might discover that appreciated assets in a family trust had pushed them into an unexpected tax bracket. The 2018 filings acted as a mirror—one that reflected not just wealth, but risk exposure."A net worth statement isn’t just numbers—it’s a narrative. And in 2018, that narrative was being written under a microscope." — Richard Murphy, tax justice campaigner
Major Advantages
- Tax optimization leverage. A well-structured statement of assets, liabilities and net worth could highlight deductions (e.g., capital losses, charitable donations) that reduced taxable income.
- Creditworthiness validation. Lenders used these statements to assess debt-to-asset ratios, making them essential for securing private credit lines.
- Divorce and estate planning clarity. Courts increasingly relied on net worth statements to equitably divide assets, while trusts used them to prove solvency.
- Investor confidence signals. Public companies often referenced asset-liability disclosures in annual reports to reassure shareholders about solvency.
- Offshore transparency compliance. Filing accurate liabilities and net worth statements mitigated risks from CRS data exchanges and common reporting standards.
- Wealth preservation strategies. The document’s structure allowed filers to identify illiquid assets (e.g., art, collectibles) that could be revalued or sold to meet liquidity needs.
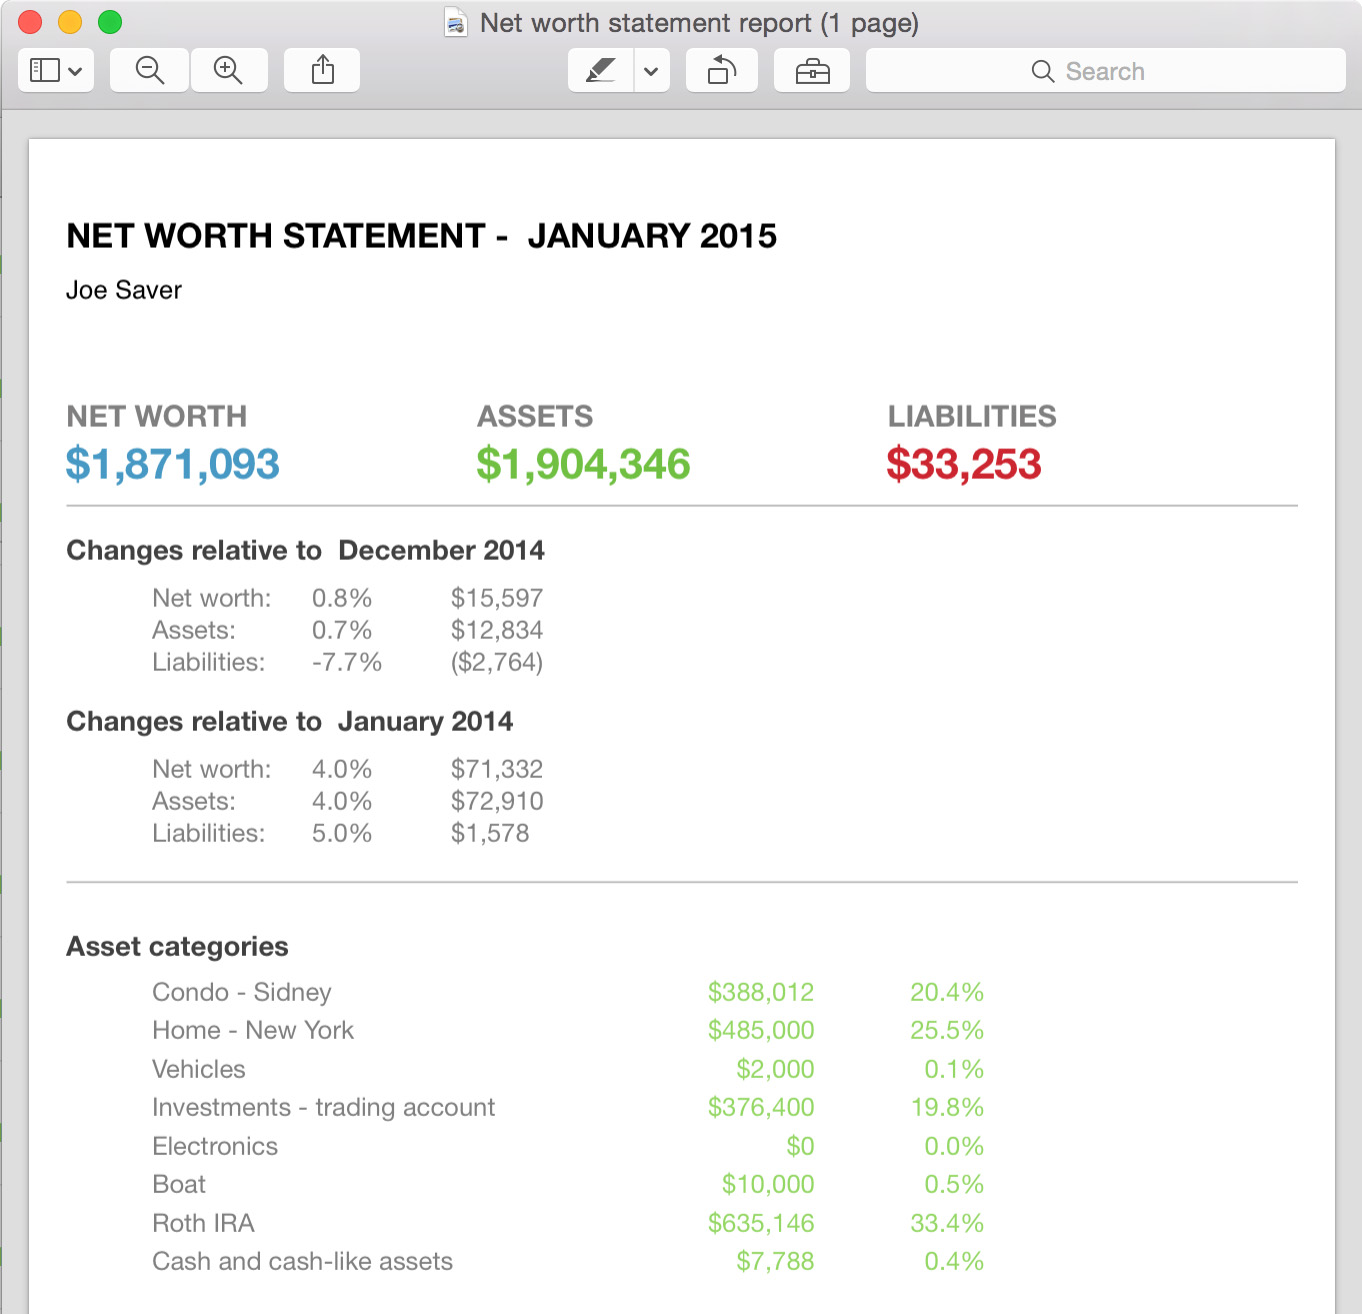
Comparative Analysis
| 2018 Filing Requirements | 2023 Filing Requirements |
|---|---|
| Cryptocurrency valuations often excluded or estimated via cost basis. | Digital asset reporting now mandatory under MiCA (EU) and IRS Form 8949. |
| Offshore entities frequently valued as single-line items ("investment in subsidiary"). | Beneficial ownership registers require detailed sub-asset breakdowns for entities. |
| Real estate appraisals conducted every 3–5 years; market downturns led to disputes. | Automated valuation models (AVMs) now used for real-time adjustments, reducing disputes. |
| Net worth statements primarily for tax/legal use; private wealth tracking was niche. | Fintech integration means real-time net worth dashboards are standard for HNWIs. |
Future Trends and Innovations
The statement of assets, liabilities and net worth is evolving into a dynamic, not static document. Blockchain-based smart contracts could soon automate asset revaluations, while AI-driven fraud detection will make discrepancies harder to hide. For individuals, biometric authentication for digital filings may replace manual signatures, reducing errors. The biggest shift, however, will be in global standardization. As jurisdictions adopt OCED’s Crypto-Asset Reporting Framework (CARF), the 2018-style statement—with its patchwork of local rules—will give way to a unified wealth disclosure protocol. The implications are profound. A liabilities and net worth statement filed in 2030 might include carbon footprint valuations, ESG compliance scores, and algorithmic risk assessments—turning what was once a tax form into a sustainability and governance tool. The question for 2018 filers isn’t just what was declared, but how those disclosures will shape the next generation of wealth reporting.
Conclusion
The statement of assets, liabilities and net worth 2018 was more than a snapshot—it was a financial time capsule. It revealed how wealth was structured at the cusp of regulatory upheaval, technological disruption, and economic uncertainty. For some, it was a shield; for others, a vulnerability. What’s clear is that the net worth statement has ceased to be a passive document. Today, it’s a strategic asset, a compliance battleground, and a window into power. As we move beyond 2018, the lessons are stark: transparency is no longer optional, and the liabilities section carries as much weight as the assets. The filings from that year serve as a warning—what you declare today will define your options tomorrow.Comprehensive FAQs
Q: Were there any major changes to how cryptocurrency was reported in the 2018 statement of assets, liabilities and net worth?
A: In 2018, cryptocurrency was often treated as a catch-all "other assets" line item, with valuations based on cost basis rather than fair market value. The IRS had only just issued Notice 2014-21 clarifying virtual currency as property, so many filers underreported or omitted crypto entirely. By 2023, Form 8949 and Schedule D became mandatory for capital gains reporting.
Q: How did Brexit affect the 2018 statement of assets, liabilities and net worth for UK residents with EU assets?
A: The 2018 filings reflected a wait-and-see approach—many UK filers delayed revaluing EU-held assets pending clarity on post-Brexit transfer rules. Some used envelope companies in Ireland or Luxembourg to mitigate currency risks, while others hedged exposure by converting euros to sterling ahead of the transition. The HMRC’s "no-deal" guidance in late 2018 forced last-minute adjustments.
Q: Can a 2018 net worth statement be used in court today for divorce settlements?
A: Yes, but with significant caveats. Courts may accept a 2018 statement of assets and liabilities as evidence, but they’ll cross-reference it with bank statements, appraisals, and tax filings from later years. If the filer’s wealth has appreciated or depreciated significantly, the net worth figure may be adjusted retroactively. Always consult a financial forensic accountant before relying on old filings.
Q: Were there industry-specific differences in how assets were valued in 2018?
A: Absolutely. Tech founders often used 409A valuations for restricted stock, while private equity managers relied on IRR-based projections. Art collectors faced subjective appraisals, with some using auction house estimates and others insurer valuations. Commercial real estate was particularly volatile—cap rates shifted post-2017 tax reforms, leading to 10–15% valuation swings depending on the market.
Q: How did the 2018 statement of assets, liabilities and net worth handle intangible assets like patents or trademarks?
A: Intangible assets were rarely detailed in personal filings, often lumped under "goodwill" or "other assets." Business owners used DCF (Discounted Cash Flow) models or royalty relief methods for patents, but without third-party appraisals, these valuations were highly disputable. Trademarks were typically valued at acquisition cost unless sold, leading to underreporting in many cases.
Q: What happens if you file an inaccurate 2018 statement of assets, liabilities and net worth today?
A: Retroactive penalties apply under IRS Revenue Procedure 2014-55 (for offshore disclosures) and UK’s GAAR rules. If the inaccuracy was negligent, you may face 20% accuracy-related penalties; if willful, 75% of the underreported tax. Some jurisdictions allow voluntary disclosures to mitigate risks, but statute of limitations varies—US: 6 years for fraudulent omissions; UK: 20 years for criminal tax evasion. Always seek legal counsel before correcting old filings.
