Where It All Began
The origins of world industries current net worth tracking lie in the 19th century, when railroads and steel mills became the first industrial titans. Before standardized accounting, valuations were rough estimates tied to physical assets: miles of track, tons of steel, or barrels of oil. The Pennsylvania Railroad’s 1875 valuation of $200 million (over $5 billion today) wasn’t just about infrastructure—it was about the industrial net worth of an entire region’s economy. Investors understood that a railroad’s value wasn’t in its trains but in the cities it connected. This was the first lesson: industry worth was never static; it was a function of what it enabled. The turn of the 20th century brought the first corporate monopolies, and with them, the need for more sophisticated valuation methods. J.P. Morgan’s financing of U.S. Steel in 1901—creating a company worth $1.4 billion at the time—required financial engineering beyond balance sheets. For the first time, global industry net worth was tied to market perception, not just tangible assets. The panic of 1907 exposed the fragility of this system: when confidence faltered, even the mightiest industries could collapse overnight. The response? The Federal Reserve, designed to stabilize the very valuations that had just imploded.The Early Signs
By the 1920s, the world industries current net worth landscape had fractured into two camps: those that thrived on mass production (automotive, chemicals) and those clinging to craftsmanship (textiles, shipbuilding). Ford Motor Company’s $1 billion valuation in 1929 wasn’t just about cars—it was about the industrial net worth of an assembly-line economy where workers became interchangeable cogs. Meanwhile, European industries like Germany’s IG Farben (precursor to modern pharma giants) were quietly amassing global industry net worth through patents and synthetic materials, laying the groundwork for post-war dominance. The Great Depression revealed the flaw in these valuations: they assumed growth would continue indefinitely. When it didn’t, industries that had seemed untouchable—like railroads—saw their worth evaporate. The lesson was clear: industry net worth wasn’t just about scale; it was about resilience. The recovery efforts of the 1930s and 1940s shifted focus to diversification. Companies that had bet everything on one commodity (oil, steel) were forced to expand into services, finance, or even entertainment. This was the birth of the modern conglomerate—a model that would later define the world industries current net worth of the late 20th century.The Turning Point
The 1970s marked the inflection point where global industry net worth began to decouple from physical assets. The oil shocks of 1973 and 1979 proved that even the most stable industries could be upended by geopolitics. Exxon’s valuation, once tied to proven reserves, now had to account for regulatory risk and public backlash. Meanwhile, Japanese manufacturers like Toyota and Sony were redefining industrial net worth through quality and innovation, not just output. The shift was subtle but irreversible: industries were no longer valued primarily for what they produced, but for how they adapted. The 1980s accelerated this trend with the rise of financialization. Leveraged buyouts, junk bonds, and the deregulation of markets turned industry net worth into a speculative asset class. Companies like RJR Nabisco, bought by KKR in 1989 for $25 billion, became symbols of a new era where debt could inflate valuations beyond traditional metrics. The dot-com bubble of the late 1990s took this further, proving that global industry net worth could be detached entirely from profitability—at least temporarily. When Amazon’s market cap briefly exceeded Walmart’s in 1999, it wasn’t just a stock market quirk; it was a statement that the future belonged to industries that could dominate digital infrastructure, not brick-and-mortar sales.“Valuation isn’t about numbers on a page. It’s about who believes in the story—and how badly they want to be part of it.” — Warren Buffett, 2008

The Build-Up, Year by Year
| Period | Key Development |
|---|---|
| 1950–1970 | Post-war boom: Industrial net worth concentrated in U.S. and European manufacturing. Ford, GM, and Siemens dominated, with valuations tied to wartime production capacity. |
| 1980–1990 | Financialization era: Debt-driven acquisitions (e.g., RJR Nabisco) redefined global industry net worth. Private equity firms emerged as major players in reshaping valuations. |
| 2000–2010 | Tech disruption: The dot-com crash exposed the volatility of industry net worth in digital sectors, but survivors (Apple, Google) redefined growth through intangible assets like IP and user data. |
| 2020–Present | AI and geopolitics: World industries current net worth now hinges on access to data, semiconductors, and rare earth minerals. State-backed industries (e.g., China’s tech giants) challenge Western dominance. |
Lessons From the Journey
- Valuation is a narrative. Industries rise or fall based on what investors are willing to believe—whether it’s the promise of the railroad age or the hype around AI today.
- Physical assets are no longer the primary driver. The global industry net worth of Apple is tied to its ecosystem (iPhone, App Store, services) far more than to its hardware inventory.
- Risk is asymmetric. A single regulatory decision (e.g., antitrust action) can erase decades of industrial net worth overnight, while compliance can propel a company into new valuation tiers.
- Geopolitics dictates liquidity. Sanctions, tariffs, and trade wars don’t just hurt earnings—they distort how world industries current net worth is perceived across markets.
- The future belongs to hybrid models. Companies that straddle physical and digital (e.g., Tesla in energy + tech) command higher industry net worth multipliers than pure-play firms.
Where Things Stand Today
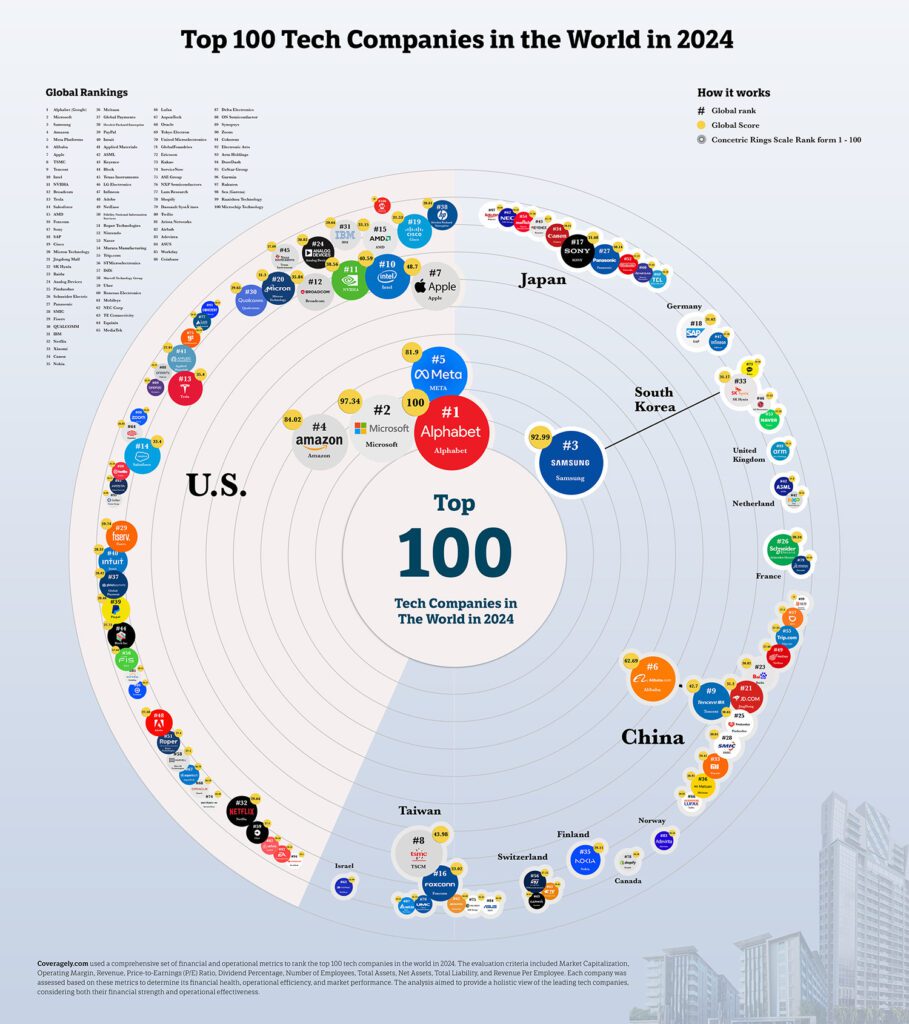
The world industries current net worth in 2024 is a patchwork of extremes. On one side, legacy industries like automotive and aerospace still command trillions, but their valuations are increasingly tied to software and data analytics. On the other, private markets—where companies like SpaceX or Rivian operate—have valuations that dwarf their public peers, yet remain invisible to traditional indices. The gap between public and private industrial net worth has never been wider, creating a two-tiered economy where only insiders see the full picture. What’s undeniable is the shift toward global industry net worth concentrated in a handful of sectors: tech (especially AI and cloud computing), biotech (with mRNA therapies redefining pharmaceutical valuations), and green energy (where subsidies and ESG pressures inflate or deflate worth based on policy whims). The old rules—where a company’s value was a multiple of its revenue—are obsolete. Today, industry net worth is a function of network effects, regulatory moats, and the ability to monetize attention (as seen in the $2 trillion+ valuation of the combined "Big Tech" quintet). The question for investors isn’t what an industry is worth, but how long that worth will last before the next disruption.
Conclusion
The history of world industries current net worth is a story of power—who controls the levers that define value, and who gets left behind when those levers shift. From Rockefeller’s oil empire to today’s AI-driven monopolies, the common thread is the same: industrial net worth has always been less about what a company owns and more about what it controls. The current era is no different. The difference now is that the control isn’t just over pipelines or factories, but over algorithms, supply chains, and the data that fuels them. The risk? When global industry net worth becomes concentrated in a few hands—or a few nations—the system grows brittle. The next crisis won’t be a stock market crash; it’ll be a collapse of trust in how value is measured. The lesson from every past cycle is the same: the industries that survive aren’t the ones with the highest valuations today, but those that can redefine what worth means tomorrow.Comprehensive FAQs
Q: Which industry holds the highest world industries current net worth today?
As of 2024, the global industry net worth leader is the tech sector, with combined valuations of major firms (Apple, Microsoft, Alphabet, Amazon, Meta) exceeding $10 trillion. However, private markets—including space, biotech, and AI startups—hold industrial net worth that dwarfs public listings but remains opaque.
Q: How do geopolitical tensions affect industry net worth?
Sanctions (e.g., on Russia’s energy sector) and trade wars (e.g., U.S.-China tariffs) directly impact industrial net worth by restricting access to markets, supply chains, or capital. For example, Huawei’s valuation plummeted after U.S. restrictions, while European firms like Siemens gained from reduced competition in certain sectors.
Q: Can an industry’s net worth be accurately measured?
No. Traditional metrics (market cap, book value) fail to capture intangibles like brand equity, talent pools, or regulatory goodwill. Even audited figures can be manipulated—witness WeWork’s 2019 valuation collapse, where private market hype masked financial reality.
Q: What’s the biggest threat to global industry net worth stability?
The rise of industrial net worth concentrated in a few AI-driven firms creates systemic risk. If a single entity (or algorithm) controls critical infrastructure—like cloud computing or drug discovery—the failure of that entity could trigger a cascading devaluation across sectors.
Q: How do emerging markets factor into world industries current net worth?
Emerging markets contribute to industrial net worth through manufacturing (e.g., Vietnam’s textiles, India’s IT services) and commodities (e.g., Congo’s cobalt). However, their industry net worth is often undervalued due to perceived risks, despite being vital to global supply chains.
