
The Complete Overview of Average Household Net Worth by Zip Code
The concept of average household net worth by zip code has evolved from a niche economic curiosity into a critical lens for understanding inequality. Before the 1980s, wealth data was aggregated at the county or state level, obscuring the granularity of urban poverty and suburban affluence. The rise of digital mapping tools and the Fed’s consumer surveys in the 1990s changed that, allowing researchers to pinpoint wealth disparities down to the postal code. Today, platforms like Redfin and Zillow overlay net worth estimates with property values, school district boundaries, and crime rates, creating a real-time snapshot of economic segregation. Yet for all the precision, the data still struggles to capture intangible factors—like the cost of childcare in a high-earning zip code or the hidden subsidies (like lower property taxes) that prop up wealthy enclaves. The most striking revelation from this data is how average household net worth by zip code correlates with racial and ethnic demographics. A 2022 Brookings Institution report found that the wealthiest 1% of zip codes—where median net worth often exceeds $10 million—are overwhelmingly white and Asian, while the poorest 10% are majority Black or Latino. This isn’t coincidence; it’s the result of redlining, suburban exclusionary zoning, and the persistent wage gap. Even within the same city, the divide is stark: in Chicago, the median net worth in the wealthy Gold Coast neighborhood hovers around $4.2 million, while in Englewood—just 15 miles away—the figure is closer to $20,000. The gap isn’t just about income; it’s about assets accumulated over generations.Historical Background and Evolution
The roots of wealth disparities by zip code stretch back to the New Deal era, when federal housing policies explicitly excluded Black families from FHA mortgages. The result? White families could build equity in suburban homes while Black families were confined to urban rentals, perpetuating a wealth gap that persists today. By the 1970s, suburban sprawl had cemented this divide, with zip codes in places like Long Island or the Washington, D.C. suburbs becoming wealth reservoirs while inner cities declined. The 1990s brought gentrification, which temporarily boosted some urban zip codes—but often at the cost of displacing long-term residents, further concentrating wealth in new enclaves. More recently, the 2008 financial crisis exposed how fragile this system was. While wealthy zip codes in places like San Francisco or New York saw net worth recover within a decade, many working-class neighborhoods never did. The Fed’s data shows that in the years following the crash, the bottom 25% of households by net worth saw no growth at all in median wealth, while the top 1% saw gains of over 50%. The pandemic exacerbated this: zip codes with high concentrations of essential workers (and thus higher exposure to COVID-19) saw net worth declines of 12-15%, while remote-work hubs in the suburbs saw increases. The result is a modern economic map where average household net worth by zip code has become a proxy for resilience—or vulnerability.Core Mechanisms: How It Works
At its core, average household net worth by zip code is shaped by three interlocking factors: homeownership rates, wage disparities, and access to financial markets. Homeownership is the single biggest driver, accounting for 60-70% of total net worth for most households. In wealthy zip codes, home values appreciate at rates far outpacing inflation—thanks to limited supply, desirable schools, and the "halo effect" of proximity to elite institutions. Meanwhile, in lower-opportunity areas, property values stagnate or decline, trapping residents in a cycle of negative equity. Wage gaps further widen the divide: a teacher in a wealthy suburb might earn $120,000 annually, while one in a struggling district earns $70,000—yet the cost of living in the wealthier area is often lower due to better public services. The third mechanism is access to capital. Wealthy zip codes have higher concentrations of financial advisors, private equity networks, and even family offices that manage multi-million-dollar portfolios. A study by the National Bureau of Economic Research found that households in the top 10% of net worth by zip code are three times more likely to have a financial advisor—someone who can guide them into tax-advantaged investments or real estate syndications. Meanwhile, lower-income zip codes often lack basic banking services, forcing residents to rely on payday lenders or high-fee prepaid cards. The result is a system where average household net worth by zip code isn’t just about current income but about inherited advantages in how wealth is accumulated and preserved.Key Benefits and Crucial Impact
Understanding average household net worth by zip code isn’t just an academic exercise—it’s a tool for policymakers, real estate investors, and individuals navigating economic mobility. For cities, this data helps identify where to target housing subsidies or infrastructure investments. For investors, it reveals which neighborhoods are poised for appreciation—or which are at risk of decline. And for individuals, it exposes the structural barriers that make wealth-building harder in certain areas. The impact isn’t just financial; it’s social. Wealthy zip codes often correlate with better health outcomes, lower crime rates, and stronger political influence—creating a feedback loop where advantage begets more advantage. The data also forces a reckoning with the myth of meritocracy. If average household net worth by zip code varies so dramatically within the same city, it suggests that opportunity isn’t evenly distributed. A child born in a wealthy zip code is far more likely to attend a top college, inherit a home, or receive mentorship—all of which compound into a lifetime of higher earnings. The converse is true for children in lower-opportunity areas, where even high test scores may not translate to admission at elite schools. This isn’t just about money; it’s about the invisible ledger of opportunity that gets passed down generationally."Wealth isn’t just about what you earn; it’s about where you live. The zip code you’re born into determines not just your income but your ability to build generational wealth." — Raj Chetty, Stanford economist and director of the Equality of Opportunity Project
Major Advantages
- Policy targeting: Cities use zip-code-level wealth data to allocate resources—like school funding or public transit—where they’re most needed.
- Investment insights: Real estate developers and private equity firms analyze average household net worth by zip code to identify undervalued markets before gentrification.
- Financial planning: Wealth managers advise clients on relocating to zip codes with higher net worth growth, often in suburbs with strong school districts.
- Social mobility indicators: Researchers track changes in average household net worth by zip code to measure progress in reducing inequality over time.
- Credit access: Banks use zip-code wealth data to assess risk, often extending better loan terms to borrowers in high-net-worth areas.
- Political influence: Wealthy zip codes have disproportionate representation in local government, shaping policies that benefit property owners over renters.

Comparative Analysis
| Wealthy Zip Code (e.g., Atherton, CA 94027) | Struggling Zip Code (e.g., Detroit, MI 48217) |
|---|---|
|
|
|
Wealth growth: 8–12% annually (driven by tech stock appreciation, real estate) |
Wealth growth: –1–2% annually (stagnant wages, job losses, medical debt) |
|
Key industries: Tech, finance, private equity (high-paying, asset-building jobs) |
Key industries: Manufacturing, healthcare (low-wage, service-sector jobs) |
Future Trends and Innovations
The next decade will likely see average household net worth by zip code become even more polarized, thanks to automation and remote work. High-skilled workers in tech or finance will cluster in a smaller number of "super-zip codes" (like Austin’s Domain or San Francisco’s Pacific Heights), driving up home values and net worth figures in those areas. Meanwhile, traditional manufacturing hubs—already struggling—will see further decline as jobs disappear, pushing net worth in those zip codes even lower. The rise of geofenced financial services (apps that offer better rates based on your zip code) could either deepen inequality or, if regulated properly, provide a lifeline to underserved areas. Another trend is the growing use of predictive wealth modeling, where algorithms estimate future net worth based on current zip-code data. Companies like Zillow and CoreLogic already use these models to forecast home value appreciation—but critics warn they could reinforce bias if they rely on historical patterns that favor wealthy areas. Meanwhile, cities are experimenting with wealth-based zoning, where tax incentives are tied to preserving affordable housing in high-net-worth neighborhoods. Whether these innovations reduce inequality or simply adapt to it remains an open question.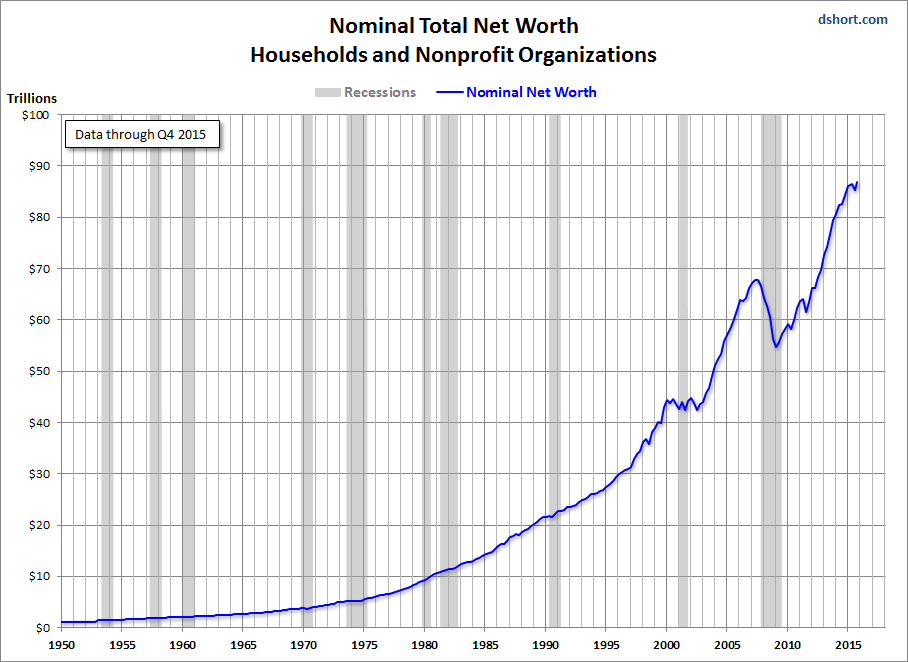
Conclusion
The data on average household net worth by zip code isn’t just numbers—it’s a diagnosis of a system that rewards location as much as effort. The most striking takeaway isn’t the disparities themselves but how stubbornly they persist, even as the economy shifts. Automation, remote work, and financial innovation should, in theory, make wealth more portable. Yet the opposite is happening: geography is becoming an even more critical determinant of financial success. The question isn’t just how to close the gap—it’s whether the political will exists to challenge the forces that created it in the first place. For individuals, the lesson is clear: average household net worth by zip code isn’t just a statistic—it’s a reflection of opportunity. Moving to a wealthier area can accelerate asset-building, but it’s no panacea without systemic change. The real solution lies in policies that break the link between geography and destiny—whether through expanded access to homeownership, stronger unions in low-wage zip codes, or education reforms that don’t rely on property taxes. Until then, the zip code remains the most powerful predictor of financial fate in America.Comprehensive FAQs
Q: How accurate are estimates of average household net worth by zip code?
The most reliable data comes from the Federal Reserve’s Survey of Consumer Finances (conducted every three years) and local tax assessments. However, these are estimates—not exact figures—since not all households report their net worth. Wealthy zip codes are often more accurately measured due to higher reporting rates, while lower-income areas may have gaps. Private companies like Redfin and Zillow use proprietary models to fill in gaps, but these can introduce bias if they rely on outdated data.
Q: Can I use average net worth by zip code to predict home value appreciation?
Yes, but with caveats. Zip codes with consistently high average net worth often correlate with strong home value growth, thanks to limited supply and high demand. However, this isn’t a guarantee—local economic shocks (like a tech bubble burst) can reverse trends. Investors should also consider factors like school district quality, crime rates, and commute times, which aren’t fully captured in net worth data.
Q: Do wealthier zip codes always have better schools?
Not exclusively, but there’s a strong correlation. Wealthy zip codes often fund schools through higher property taxes, leading to better facilities, lower student-to-teacher ratios, and advanced programs. However, some high-poverty areas have outperformed wealthier districts due to strong leadership or charter school initiatives. The relationship is complex—wealth enables good schools, but good schools can also attract wealth.
Q: How does race factor into average household net worth by zip code?
Race is the single biggest predictor of wealth disparities by zip code. Historically redlined neighborhoods—often majority Black or Latino—still show net worth figures 20–30% lower than comparable white neighborhoods, even when incomes are similar. This is due to decades of unequal access to mortgages, predatory lending, and job discrimination. The Fed’s data shows that white households have nearly 10 times the median net worth of Black households in similar zip codes.
Q: Can moving to a wealthier zip code significantly increase my net worth?
Possibly, but it depends on your financial strategy. Moving to a high-net-worth zip code can improve home equity growth and access to better schools (which boosts future earnings). However, the cost of living in those areas is often higher, and the initial move may require selling a home at a loss. Some financial advisors recommend "wealth migration"—relocating to a zip code with strong appreciation potential—but this requires careful planning to avoid debt traps.
Q: Are there zip codes where average net worth is rising faster than others?
Yes. In the past decade, zip codes near tech hubs (like Austin’s Domain or Raleigh’s Research Triangle) have seen net worth growth of 10–15% annually, driven by remote workers and high-paying jobs. Meanwhile, Rust Belt cities like Detroit and Cleveland have seen stagnant or declining net worth in many zip codes due to job losses. The pandemic accelerated this trend, with suburban zip codes near major cities (like Boise or Phoenix) seeing rapid wealth accumulation as urbanites fled high-cost cities.
Q: How do tax policies affect average household net worth by zip code?
Tax policies have a profound impact. Wealthy zip codes often benefit from lower effective tax rates due to deductions (like mortgage interest or capital gains exemptions), while lower-income zip codes pay higher rates in property taxes relative to their income. Additionally, states with no income tax (like Texas or Florida) see higher net worth in wealthy zip codes because residents keep more of their earnings. Conversely, high-tax states like California see wealthier zip codes clustering in areas with strong local tax breaks.
Q: Can governments artificially boost average net worth in struggling zip codes?
Some policies have shown promise. First-time homebuyer grants, expanded public transit to job centers, and wealth-building programs (like those in Baltimore and Chicago) have helped. However, the most effective interventions often require long-term investment—like improving schools or reducing crime—rather than short-term fixes. The challenge is scaling these programs without displacing existing residents or attracting gentrification.
