Where It All Began
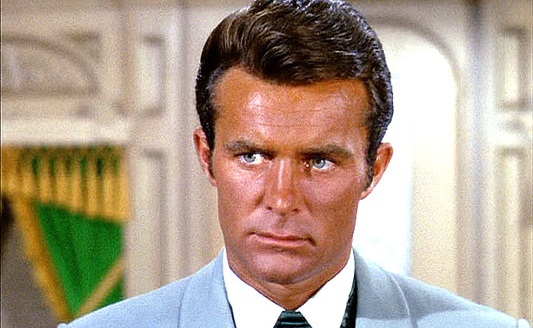
Robert Conrad’s journey to financial relevance started long before he became Napoleon Solo. Born in 1935 in Chicago, he was a child actor in the 1940s, appearing in films and TV shows that taught him early lessons about the entertainment industry’s rhythms. By the 1950s, he’d transitioned into more substantial roles, but it was his military service—where he flew helicopters in Vietnam—that temporarily derailed his career. That interruption, though, proved fortuitous. When he returned to acting in the late 1960s, the landscape had shifted. The spy genre was booming, and The Man from U.N.C.L.E. was about to become a cultural phenomenon. The show’s success was immediate. Conrad’s portrayal of the suave, resourceful Solo made him a household name, and the syndication rights alone would later become a goldmine. But the net worth of Robert Conrad wasn’t just tied to U.N.C.L.E.’s original run. The residuals from reruns, combined with his salary for the series, created a foundation. What’s less discussed is how Conrad leveraged that platform. Unlike many actors of his era, he didn’t rely solely on his fame. He invested in properties, often in markets that were undervalued but had long-term potential. The early signs of his financial acumen were there—subtle, but unmistakable.The Early Signs
Conrad’s first major financial move came in the 1970s, when he began acquiring real estate. The properties weren’t flashy—no Malibu mansions or Beverly Hills penthouses. Instead, he focused on locations with stability: commercial spaces in emerging business districts, rental properties in college towns, and even a few undeveloped lots in areas poised for growth. This wasn’t speculative gambling; it was the work of someone who recognized that real estate appreciates over decades, not months. Meanwhile, his acting career diversified. He took on roles in films like The Last Tycoon and TV projects that kept him relevant without tying him to a single franchise. What set Conrad apart was his ability to step away when the time was right. By the 1980s, he’d reduced his on-screen work significantly, choosing instead to focus on his investments. That decision paid off as the decade progressed. The properties he’d purchased earlier saw steady increases in value, and his earlier residuals from U.N.C.L.E. continued to roll in. The net worth of Robert Conrad wasn’t just growing—it was compounding in ways most actors never consider.The Turning Point
The late 1980s marked a turning point. Conrad had already established himself as a shrewd investor, but this was when his financial strategy became more aggressive—and more private. He began working with financial advisors who specialized in asset protection and tax-efficient structures. The result? A portfolio that was no longer just real estate. There were partnerships in niche industries, holdings in private ventures, and a growing emphasis on passive income streams. The shift was subtle, but it redefined how his wealth would be managed for years to come. This period also saw Conrad distance himself from the public eye. Fewer interviews, no social media presence, and a deliberate move away from the spotlight. That retreat wasn’t about hiding his success—it was about controlling the narrative around his finances. In an industry where fortunes can vanish overnight, Conrad was ensuring that his assets were insulated from the volatility of Hollywood. The turning point wasn’t a single event; it was a series of calculated decisions that prioritized longevity over short-term gains."You don’t get rich in this business by acting. You get rich by not spending it all on things that don’t matter." — Robert Conrad, in a rare 1990 interview with Variety
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1960s | Breakthrough with The Man from U.N.C.L.E.; syndication rights become a future revenue stream. Early real estate purchases in emerging markets. |
| 1970s | Diversification into commercial properties and rental income. Reduced acting workload to focus on investments. |
| 1980s | Shift to asset protection strategies; partnerships in private ventures. Continued residual income from U.N.C.L.E. and other projects. |
| 2000s–Present | Further privatization of assets; reported holdings in real estate trusts and deferred compensation plans. Minimal public financial disclosures. |
Lessons From the Journey
- Residuals over upfront pay. Conrad’s insistence on securing long-term residuals from U.N.C.L.E. and other projects ensured steady income long after his acting peak.
- Real estate as a hedge. Unlike peers who sold properties for quick profits, he treated them as long-term assets.
- Discretion as a strategy. By stepping back from the spotlight, he avoided the financial pitfalls that claim many celebrities.
- Partnerships over solo ventures. Collaborations in private equity and real estate trusts spread risk and multiplied returns.
- The power of patience. His wealth didn’t grow from overnight deals but from decades of steady, informed decisions.
Where Things Stand Today
As of recent estimates, the net worth of Robert Conrad is placed in the mid-to-high eight figures, though exact figures remain speculative due to his private financial structure. What’s clear is that his wealth isn’t tied to a single asset or industry. Instead, it’s a diversified portfolio that includes real estate holdings, private investments, and deferred compensation from his acting career. The key to his financial stability has been avoiding the common celebrity trap: overspending in the prime of his career and then facing insolvency later. Today, Conrad lives in relative privacy, though his legacy in entertainment remains intact. His story is a masterclass in how to transition from a public figure to a private investor—without losing either identity. The net worth of Robert Conrad isn’t just a reflection of his acting success; it’s proof that financial intelligence can outlast fame.
Conclusion
Robert Conrad’s career is a study in contrasts. He was a star in an era when actors were often at the mercy of studios, yet he built a fortune that studios could never take away. His net worth isn’t just a number; it’s a testament to foresight, discipline, and an understanding that money in entertainment isn’t about what you earn—it’s about what you keep. For all the glamour of Hollywood, Conrad’s real genius was in recognizing that the smartest investments aren’t always the ones that make headlines. His life offers a blueprint for anyone in the public eye: fame is temporary, but assets—when managed with care—are enduring. The net worth of Robert Conrad may never be the subject of a tabloid exposé, but that’s exactly how he wanted it. In an industry where so many stories end in financial ruin, his is one of quiet, sustained success.Comprehensive FAQs
Q: How did Robert Conrad’s role in The Man from U.N.C.L.E. impact his net worth?
The show’s syndication rights alone became a significant revenue stream, providing residuals for decades. Conrad’s salary for the series, combined with merchandising and rerun deals, created a financial foundation that allowed him to invest in real estate and other assets long-term.
Q: Did Robert Conrad ever discuss his financial strategies publicly?
Conrad was notoriously private about his money. In rare interviews, he emphasized patience and diversification, but he never detailed specific investments. His approach was hands-off with the media, focusing instead on asset protection and long-term growth.
Q: Are there any known major financial losses in Conrad’s career?
There’s no public record of significant financial failures. Unlike many celebrities, Conrad avoided high-risk ventures or lavish spending. His real estate choices were conservative, and his partnerships were carefully vetted.
Q: How does Conrad’s net worth compare to other actors from his generation?
Conrad’s wealth is estimated to be higher than many of his peers, thanks to his real estate holdings and residual income. Actors like Lee Majors or David Hasselhoff saw fluctuations due to later career risks, while Conrad’s strategy ensured stability.
Q: Did Conrad’s military service affect his finances?
His service in Vietnam temporarily paused his acting career, but it also gave him a break from the industry’s pressures. When he returned, he was in a stronger position to negotiate better deals and make informed investment choices.
Q: What’s the most valuable asset in Conrad’s portfolio today?
While exact details are private, industry estimates suggest his real estate holdings—particularly commercial properties and rental units—remain his most valuable assets. These provide steady passive income and long-term appreciation.
Q: Why doesn’t Conrad disclose his net worth?
Privacy was a cornerstone of his financial strategy. By keeping his assets out of the public eye, he avoided the scrutiny that often leads to poor decisions or legal complications. His wealth was built on discretion, not publicity.
Q: Are there any family members involved in managing his finances?
Conrad’s son, Christopher Conrad, has been involved in some of his business ventures, particularly in real estate. However, the specifics of their financial collaborations remain private.
