
The Complete Overview of White Family Median Net Worth
The white family median net worth in the U.S. has long served as a benchmark for economic health, but its persistence as the highest among racial groups isn’t accidental. Federal Reserve reports consistently show white households holding median net worth figures nearly five times higher than Hispanic families and eight times higher than Black families. These aren’t isolated snapshots; they reflect a century of public policy, housing discrimination, and employment disparities. Even when controlling for income, the racial wealth gap remains stubbornly wide—proof that wealth isn’t just about earnings but about access to assets that appreciate over time. What makes this disparity particularly insidious is its generational transmission. White families pass down wealth through home equity, inheritances, and business ownership at far higher rates than other groups. A 2022 Brookings Institution study found that white families receive 92% of intergenerational wealth transfers, while Black and Hispanic families receive just 5% each. This isn’t just about money; it’s about economic mobility. A child born into a white family with median wealth starts life with a built-in cushion—college funds, emergency reserves, and the ability to weather financial shocks. For families of color, the absence of this cushion means every crisis hits harder.Historical Background and Evolution
The roots of the white family median net worth advantage stretch back to the Homestead Act of 1862, which granted 160 acres to white settlers while excluding Black Americans and Native tribes. Fast-forward to the 20th century, and federal housing policies—like the Federal Housing Administration’s redlining maps—systematically denied mortgages to Black neighborhoods, trapping wealth in white communities. Meanwhile, programs like the GI Bill after World War II provided education and home loans to white veterans while excluding Black soldiers. These weren’t isolated incidents; they were structural policies that created the conditions for white wealth accumulation. Even as overt discrimination faded, its effects lingered. The white family median net worth surged in the post-war era as homeownership became the primary wealth-building tool, thanks to subsidized mortgages and rising property values—benefits largely inaccessible to Black families. By the 1980s, the gap had widened further with the savings and loan crisis, which disproportionately affected minority communities, and the crackdown on predatory lending in Black neighborhoods (while white families benefited from unregulated subprime mortgages later). Today, the white family median net worth reflects not just individual effort but centuries of policy choices that tilted the playing field.Core Mechanisms: How It Works
The white family median net worth isn’t just higher—it’s more resilient. One key mechanism is homeownership rates: white families own homes at nearly double the rate of Black families, and home equity accounts for roughly 70% of median white wealth. This isn’t happenstance; it’s the result of historical barriers to homebuying for families of color, from discriminatory lending to higher down payment requirements. Even when controlling for income, white families are more likely to live in high-appreciation neighborhoods, further amplifying their wealth. Another critical factor is inheritance. White families receive far larger inheritances on average, which they then reinvest in assets like stocks, real estate, and businesses. A 2023 study by the Urban Institute found that white families are 10 times more likely to receive an inheritance than Black families. This cycle of wealth transmission ensures that even if a white family faces a financial setback, they’re more likely to recover—while families of color lack the same safety net. The result? A self-perpetuating wealth gap where advantage begets advantage, and disadvantage begets more disadvantage.Key Benefits and Crucial Impact
The white family median net worth isn’t just a number—it’s a leverage point for economic and social mobility. Higher wealth means better access to education, healthcare, and political influence. White families with median wealth can afford to skip generations of poverty, while families of color often face multi-generational struggles just to achieve the same baseline stability. This isn’t about individual merit; it’s about systemic head starts. The ability to pass down wealth, fund college, or weather job loss isn’t a personal achievement—it’s a structural advantage baked into the economy. Yet the impact of this wealth gap extends beyond individual households. Communities with higher median white wealth tend to have better schools, lower crime rates, and stronger local economies—not because of inherent superiority, but because wealth begets resources. A white family with median net worth can afford to live in a neighborhood with good schools, which then drives up property values, which then increases the wealth of other white families. The cycle is self-reinforcing, and breaking it requires more than individual effort—it demands policy interventions at scale."Wealth inequality is not an accident. It is the result of policies that have systematically favored some groups over others for generations. The question isn’t how to close the gap—it’s how to stop widening it." — Thomas Shapiro, Author of Black Wealth/White Wealth
Major Advantages
The white family median net worth confers several structural advantages that persist across generations: - Asset Accumulation: White families hold far more liquid assets (cash, stocks, bonds) and illiquid assets (home equity, businesses), allowing for easier wealth transfer. - Credit Access: Higher net worth means better credit scores, lower interest rates, and easier access to loans—even for riskier investments like small businesses. - Educational Head Start: Wealthier families can afford private schools, test prep, and college funds, ensuring their children enter the workforce with fewer barriers. - Political Influence: Wealth translates to donations, lobbying power, and policy shaping, ensuring that future economic rules continue to favor asset holders. - Crisis Resilience: During recessions or job losses, white families with median wealth are far more likely to recover due to savings, home equity, and inherited safety nets.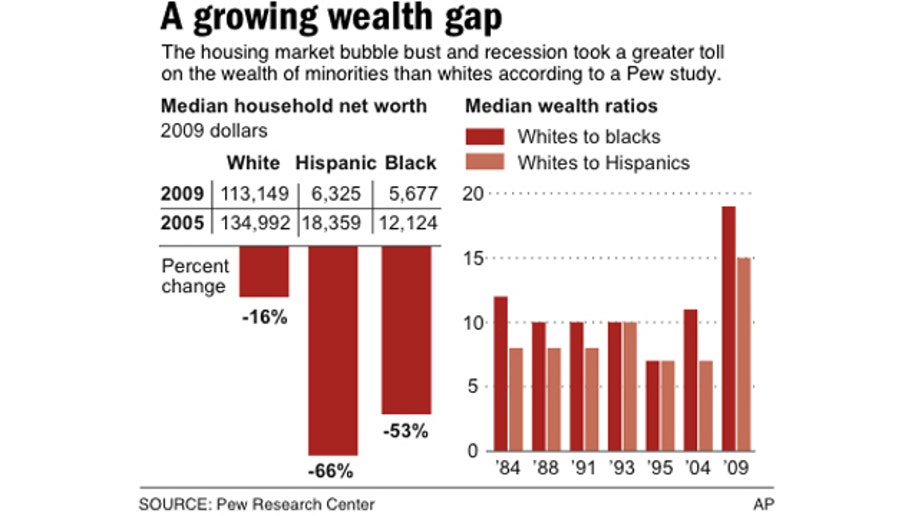
Comparative Analysis
| Metric | White Families | Black Families | |--------------------------|----------------------------------|----------------------------------| | Median Net Worth | ~$188,200 (2022 Fed data) | ~$24,100 | | Homeownership Rate | ~74% | ~44% | | Inheritance Likelihood | ~40% receive inheritance | ~4% receive inheritance | | Student Debt Burden | Lower average debt per capita | Higher average debt per capita | | Intergenerational Wealth Transfer | High | Minimal | Note: Figures are approximate and based on aggregated Federal Reserve and Brookings Institution data.Future Trends and Innovations
The white family median net worth will likely remain the highest in the U.S. for the foreseeable future unless targeted policy changes occur. One potential shift is the expansion of wealth-building tools for marginalized groups, such as baby bonds (government-funded accounts for children) or community land trusts to increase homeownership in underserved areas. However, without direct wealth redistribution—like reparations or aggressive tax reforms—historical disparities will persist. Another trend is the rise of alternative wealth metrics. As traditional homeownership becomes less accessible (due to inflation and high costs), some white families are shifting wealth into private equity, venture capital, and digital assets—further widening the gap. Meanwhile, families of color may see greater access to wealth-building tools through employee stock ownership plans (ESOPs) or cooperative ownership models. The challenge will be ensuring these innovations don’t just benefit the already wealthy.
Conclusion
The white family median net worth isn’t a measure of individual success—it’s a product of systemic design. Understanding this gap isn’t about assigning blame; it’s about recognizing the economic architecture that has shaped it. The goal shouldn’t be to punish white families for historical inequities but to level the playing field so that wealth accumulation isn’t dependent on race. That requires bold policy changes, from student debt relief to expanded homeownership programs for families of color. The alternative is a future where the white family median net worth remains the default benchmark—while other groups continue to play catch-up. The data is clear: wealth inequality isn’t a bug in the economy; it’s a feature. Changing that requires more than good intentions—it demands structural reform.Comprehensive FAQs
Q: Why is the white family median net worth so much higher than other groups?
The gap stems from centuries of discriminatory policies, including redlining, exclusion from the GI Bill, and unequal access to homeownership. Even when controlling for income, white families benefit from inherited wealth, better credit access, and neighborhood advantages that compound over generations.
Q: Does higher white median net worth mean white families work harder?
No. Wealth accumulation is heavily influenced by starting points. A white family with median wealth begins with home equity, inheritances, and generational safety nets—advantages that families of color often lack, regardless of work ethic.
Q: Can the wealth gap ever be closed?
Closing the gap would require aggressive policy interventions, such as wealth redistribution, reparations, and expanded access to homeownership. Without these, the gap will likely persist—though it could narrow with targeted programs like baby bonds or community wealth-building initiatives.
Q: How does student debt affect the white family median net worth?
White families hold less student debt per capita than Black or Hispanic families, partly because they have more wealth to fund education and partly because historically Black colleges (HBCUs)—where many students of color attend—have higher tuition costs. This debt burden reduces future wealth-building potential for families of color.
Q: Are there any white families with low or negative net worth?
Yes, but they are far less likely to be in the median. The white family median net worth is skewed upward by inherited wealth, homeownership, and asset appreciation. Many white families with low net worth still benefit from generational safety nets that families of color lack entirely.
Q: What’s the biggest misconception about white median net worth?
The biggest myth is that it’s purely the result of individual effort. In reality, systemic advantages—like historical homeownership subsidies, inheritance patterns, and workplace discrimination—play a far larger role than personal choices.
