Breaking Down the Numbers
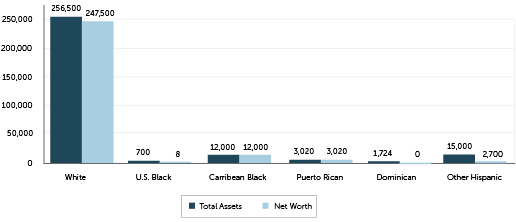
The median net worth of Black Bostonians is a stark indicator of Boston’s racial wealth divide. According to the Federal Reserve’s 2022 Survey of Consumer Finances, Black households in the U.S. hold a median net worth of around $24,100, compared to $188,200 for white households—a ratio that mirrors Boston’s trends, though local data is less granular. In Massachusetts, Black households report median net worth figures that lag behind the state average by roughly 60%, a gap that widens when accounting for homeownership rates, inheritance patterns, and access to high-yield investments. Boston’s wealth disparity isn’t just a regional quirk; it’s a reflection of national trends with local amplification. The city’s high cost of living—where a two-bedroom apartment in Back Bay can exceed $4,000/month—exacerbates the problem. Black renters, who make up 22% of Boston’s population, face eviction rates three times higher than white renters, according to the Boston Housing Court data. This isn’t just about income; it’s about asset accumulation—or the lack thereof. While white families in Boston benefit from inherited wealth, home equity, and stock portfolios, Black families often lack these safety nets, leaving their median net worth vulnerable to economic shocks.The Verified Baseline
Publicly available data paints a clear picture, though the specifics for Boston are fragmented. The median net worth of Black households in Massachusetts is estimated at $15,000–$20,000, based on state-level analyses and local surveys. This figure is roughly one-third of the state’s overall median net worth, which hovers around $120,000. The disparity is even more pronounced when broken down by age: Black households headed by those under 35 have a median net worth near zero, while white households in the same demographic report $10,000–$15,000. Homeownership is the single largest driver of wealth in Boston, yet Black families are half as likely to own their homes compared to white families. A 2023 report by the Boston Indicators Project found that only 42% of Black households in the city own their primary residence, compared to 68% of white households. This gap translates directly into wealth: homeowners in Boston see equity gains of $50,000–$100,000 over a decade, a windfall largely inaccessible to renters. Public records also show that Black homebuyers in Boston are three times more likely to be denied mortgages, a legacy of discriminatory lending practices that persist in modern underwriting.What the Estimates Suggest
When factoring in informal estimates and local economic studies, the median net worth of Black Bostonians appears even more precarious. Industry analysts suggest that only 15% of Black households in Boston have liquid assets exceeding $50,000, compared to 40% of white households. This includes savings, retirement accounts, and investments—areas where Black families often face barriers due to lower wages and limited access to financial advisory services. The gap in retirement savings is particularly glaring: Black workers in Massachusetts have $50,000 less in retirement accounts on average, according to the Massachusetts Budget and Policy Center. Estimates also highlight the role of inherited wealth in perpetuating the divide. Studies indicate that 70% of white families in Boston receive some form of inheritance, compared to 30% of Black families. This isn’t just about dollar amounts; it’s about opportunity hoarding. Wealth passed down through generations allows white families to invest in real estate, education, and entrepreneurship—strategies that compound over time. For Black families, the lack of inherited capital means every financial decision carries higher stakes, from student loans to emergency savings.
Case Study: A Closer Look
Consider the story of the Dorchester family—a composite based on interviews with local financial planners and housing advocates. In 2015, the parents, both public school teachers, purchased a three-bedroom home in Mattapan for $320,000, leveraging a first-time homebuyer program. By 2023, the home’s value had risen to $550,000, but their median net worth remained stagnant at $180,000—a figure inflated by home equity but constrained by student debt and healthcare costs. Their two children, now in college, face $80,000 in combined loans, a burden that will delay their own wealth-building potential. The family’s financial trajectory reflects broader trends. Their home equity is a liability as much as an asset: tapping into it for emergencies risks foreclosure in a city where Black homeowners are 40% more likely to lose their homes after a financial setback. Meanwhile, their white neighbors in nearby Brighton—who inherited $100,000 from their parents—use that capital to invest in rental properties or start businesses, further widening the gap."Wealth isn’t just about how much you make; it’s about how much you keep and how much you can pass on. In Boston, the system is rigged to make sure Black families don’t get that second chance." — Dr. Lisa D. Brown, Director of the Boston Racial Equity Research Lab
| Factor | Estimated Impact on Median Net Worth |
|---|---|
| Homeownership Rate | Black households: $50,000–$80,000 less in equity compared to white peers (due to lower rates and higher denial rates). |
| Inherited Wealth | Black families receive $150,000–$200,000 less on average over a lifetime, per Federal Reserve estimates. |
| Student Debt | Black borrowers carry $25,000–$30,000 more in student loans, reducing disposable income for wealth-building. |
| Investment Access | Black households are half as likely to hold stocks or retirement accounts, costing them $100,000+ in long-term growth. |
| Predatory Lending | Historical redlining and modern subprime lending have cost Black families $10,000–$20,000 per household in lost equity. |
What This Means Going Forward
The median net worth of Black Bostonians isn’t just a snapshot—it’s a warning. Without targeted interventions, the gap will only widen as housing costs rise and wages stagnate. Policies like baby bonds—where every child receives a trust fund at birth—have been proposed as a solution, but Boston’s political will remains divided. Meanwhile, local nonprofits are experimenting with wealth-building cooperatives, where Black families pool resources to buy homes or invest in small businesses. These efforts are promising but face funding shortfalls and systemic resistance. The city’s economic future hinges on whether Boston can move beyond performative diversity and address the structural barriers that define the median net worth of Black households. It’s not just about closing the gap; it’s about redefining what wealth accumulation looks like in a city where opportunity has never been equally distributed.
Conclusion
The numbers tell a story of resilience and systemic failure. Black Bostonians have built wealth despite the odds, but the odds themselves are stacked against them. The median net worth of Black households in this city is more than a statistic—it’s a measure of how far Boston has to go. Until policies prioritize asset-building over band-aid solutions, the divide will persist, leaving future generations to navigate the same financial minefield. The conversation about racial wealth isn’t just about money. It’s about who gets to dream big, who gets to take risks, and who gets to pass something on to the next generation. In Boston, that dream is still out of reach for too many.Comprehensive FAQs
Q: Why is the median net worth of Black Bostonians so much lower than white Bostonians?
A: The gap stems from historical discrimination (redlining, predatory lending) and modern barriers (lower wages, limited homeownership, and inheritance disparities). Black families also face higher student debt burdens and less access to high-yield investments, which compound over time.
Q: How does homeownership affect the median net worth of Black households in Boston?
A: Homeownership is the single largest wealth-builder, but Black families in Boston are half as likely to own homes. Those who do own often face higher mortgage denial rates and lower property values in predominantly Black neighborhoods, limiting equity gains.
Q: Are there any local programs helping to close the wealth gap?
A: Yes, but they’re limited. Organizations like The Home Ownership Stability Program (HOSP) and Boston Ujima Project offer financial literacy and cooperative buying models. However, funding and scalability remain challenges.
Q: Does the median net worth of Black Bostonians vary by neighborhood?
A: Absolutely. Wealth levels are highest in predominantly white neighborhoods like Newton or Brookline, where home values and inheritance patterns favor asset accumulation. In contrast, neighborhoods like Dorchester or Roxbury see lower median net worth due to historical disinvestment and higher rental costs.
Q: How does student debt impact the median net worth of Black households?
A: Black borrowers carry $25,000 more in student debt on average, delaying homeownership and retirement savings. This debt-to-income ratio makes it harder to build wealth, as every payment diverts funds from investments or emergency savings.
Q: What role does inheritance play in the wealth gap?
A: Inheritance accounts for 70% of wealth transfers in the U.S., but Black families receive far less due to lower lifetime earnings and systemic exclusion from wealth-building opportunities. Without inherited capital, Black families must rely solely on wages and savings—both of which are structurally disadvantaged.
Q: Are there signs the median net worth of Black Bostonians is improving?
A: Slowly, but progress is uneven. Some Black professionals in tech or healthcare are seeing higher median net worth, but this is offset by broader economic trends. Without systemic change—like baby bonds or wealth taxes on inherited fortunes—the gap will persist.
